


EN
Colgate-Palmolive (CL) Rallies On Resilient Growth Narrative As Fair Value Debate Heats Up
Colgate-Palmolive (CL) has been back in focus after recent commentary highlighted its steady growth profile, rising dividend, and emphasis on oral care and pet nutrition categories, despite higher input costs.
Recent trading has been supportive for Colgate-Palmolive, with a 1-day share price return of 1.81% and a 30-day gain of 7.43% building on a 28.29% year to date move. That share price strength lines up with a 1-year total shareholder return of 30.76%, extending to 41.35% over three years and 45.40% over five years, which points to momentum that has been sustained rather than fleeting.
Scan beyond Colgate-Palmolive and compare its momentum and defensiveness with a curated group of consumer staples and household peers using our 31 resilient stocks with low risk scores
After a near 30% 1 year return and a move that has pushed Colgate-Palmolive close to its US$101.70 analyst price target, the valuation question gets sharper. Is this a moment to pay up for resilience, or a time to wait for a cleaner entry point as expectations reset?
Most Popular Narrative: 15% Overvalued
On the latest narrative fair value, Colgate-Palmolive at $99.67 trades above an estimated $86.48, which raises a clear pricing question according to rcb9, an investor in the Simply Wall St Community who built that valuation framework.
"This creates a trap worth naming. If you normalise the margin but leave the future multiple at the GAAP-derived figure, you count the adjustment twice and overstate fair value by roughly 45%. The margin and the multiple have to sit on the same basis. That is why 15% pairs with 24x here rather than with 35x."
See why 12 investors see Colgate-Palmolive as 15% overvalued.
The valuation work from rcb9 rests on a few core inputs. It uses a 4% revenue growth rate, a 15% profit margin and a future P/E multiple of 24x, all discounted at 7%, to arrive at a fair value of $86.48. Those assumptions tie closely to Colgate-Palmolive guidance and recent margin history in the narrative, and they sit below the current analyst price target of $101.70 even before layering in any extra optimism.
Readers get a helpful warning here about mixing metrics that do not share the same base. The narrative argues that reported net margin around 10% is distorted by a one off impairment, while a normalised level near the mid teens lines up with cash generation and prior years. If you lift earnings to that higher margin yet keep using a P/E multiple built off compressed GAAP results, you are effectively rewarding the adjustment twice in your spreadsheet.
On that logic, the narrative sees Colgate-Palmolive as a high quality consumer staples group with a strong oral care position, but one where a lot of that quality is already embedded in the share price. The gap between $99.67 and $86.48 is not framed as a bubble. It is presented as a 15.3% premium that relies on what the author describes as "competent continuation" in categories like toothpaste and pet nutrition rather than any radical shift.
Result: Fair Value of $86.48 (OVERVALUED)
Still, this fair value gap could close quickly if North America keeps lagging or if another impairment charge signals deeper trouble in Colgate-Palmolive’s skin health portfolio.
Find out about the key risks to this Colgate-Palmolive narrative.
Another View: Colgate-Palmolive Through A Cash Flow Lens
Where rcb9’s narrative flags Colgate-Palmolive as 15% overvalued on earnings and multiples, the SWS DCF model lands in a different place. On that framework, CL at $99.67 trades about 20.8% below an estimated future cash flow value of $125.78, which frames today’s quote as a potential discount rather than a premium. The question is which lens you trust more when the cash flow model and the earnings multiple are pulling in opposite directions.
Look into how the SWS DCF model arrives at its fair value.
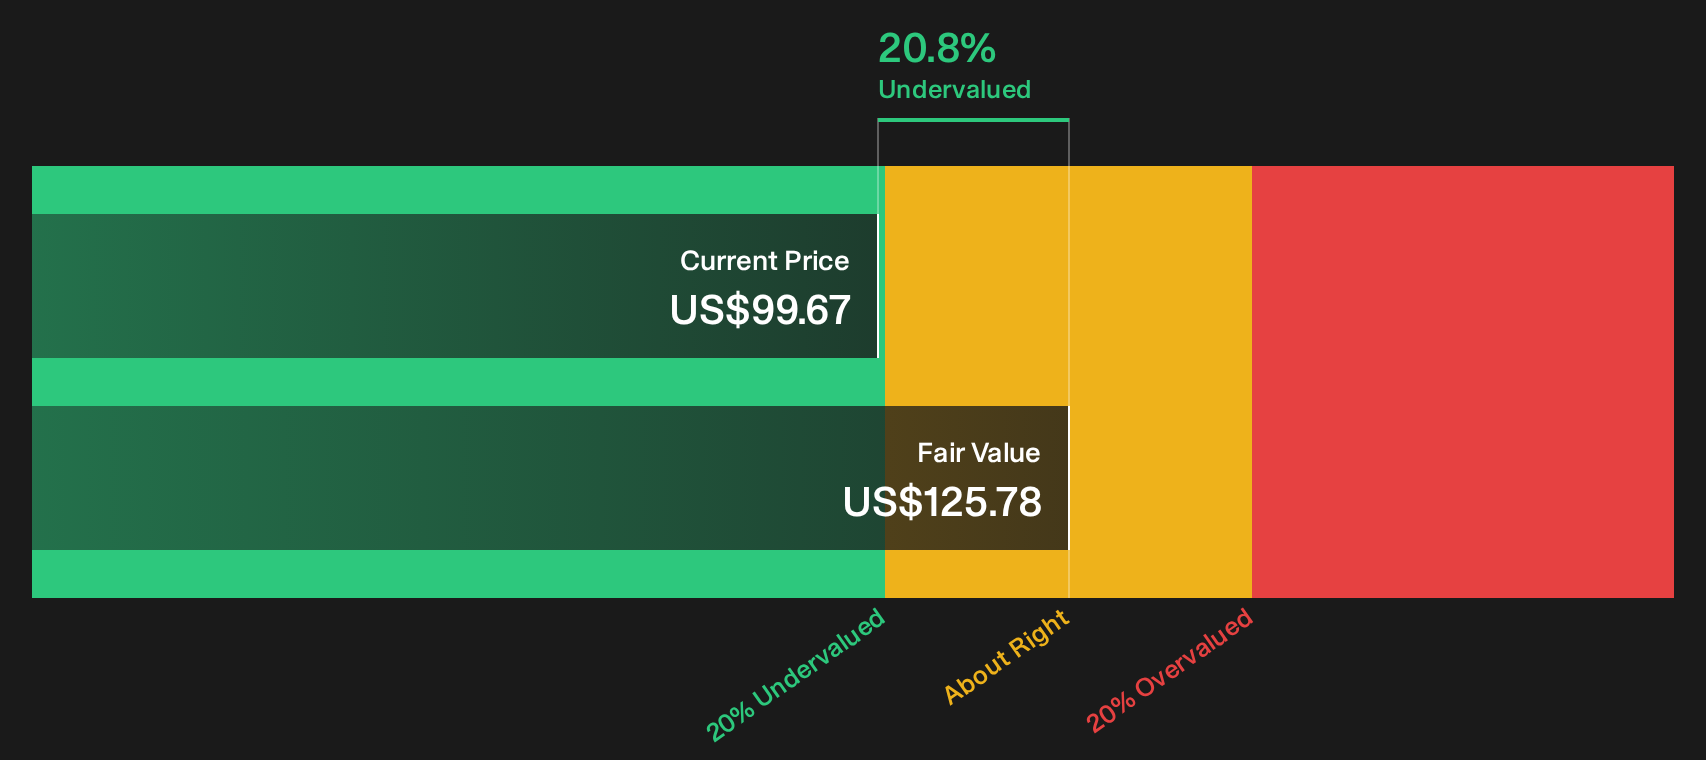
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split sentiment around Colgate-Palmolive leaves you on the fence, treat that as a cue to move fast and pressure test the data for yourself using our 3 key rewards and 4 important warning signs
Looking for more Colgate-Palmolive sized ideas?
You have seen how split opinions on Colgate-Palmolive can be. Do not stop there. Push your watchlist wider using targeted screeners that surface fresh angles fast.
- Target resilient income by reviewing stocks with robust yields and balance sheets through our 6 dividend fortresses.
- Hunt for quality at a discount with our 32 high quality undervalued stocks that filters for strong fundamentals at prices that may still be catching up.
- Spot potential future leaders early by scanning the 20 high quality undiscovered gems before they attract broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com