


EN
PepsiCo (PEP) Cuts 1,000 Jobs, Is The Stock A Bargain?
PepsiCo (PEP) is back in the spotlight after announcing plans to cut about 1,000 jobs across its North American units, a restructuring push shaped by pressure from Elliott Investment Management.
Recent trading suggests investors are reassessing PepsiCo. The 1 month share price return of 12.51% and 7 day gain of 2.90% point to building momentum, even though the 3 year total shareholder return declined 2.81% and the 5 year figure is a modest 4.41%.
Spot opportunities that echo PepsiCo's restructuring story by scanning a curated group of value-focused consumer staples in our 32 high quality undervalued stocks.The share price now trades above the average analyst target while internal models imply a large discount to intrinsic value. Which reference point tells you more about where PepsiCo really belongs?
Most Popular Narrative: 27.3% Undervalued
PepsiCo last closed at $145.44, while the most followed narrative on Simply Wall St places fair value at $200.01, implying a wide valuation gap according to that framework. That assessment, from Lijo, an investor in the Simply Wall St Community, also leans heavily on PepsiCo's income profile and balance between growth and payouts.
PepsiCo [PEP] is a classic growth + income compounder, not a high growth stock.
It is not going to double in 2 years. It is a low-volatility anchor that pays you to wait.
See why 32 investors see PepsiCo as 27% undervalued.
Result: Fair Value of $200.01 (UNDERVALUED)
Still, PepsiCo faces pressure in PepsiCo Foods North America and ongoing health trends that challenge sugary drinks and salty snacks, which could weaken this income-focused thesis.
Find out about the key risks to this PepsiCo narrative.
Another View: What PepsiCo’s P/E Is Telling You
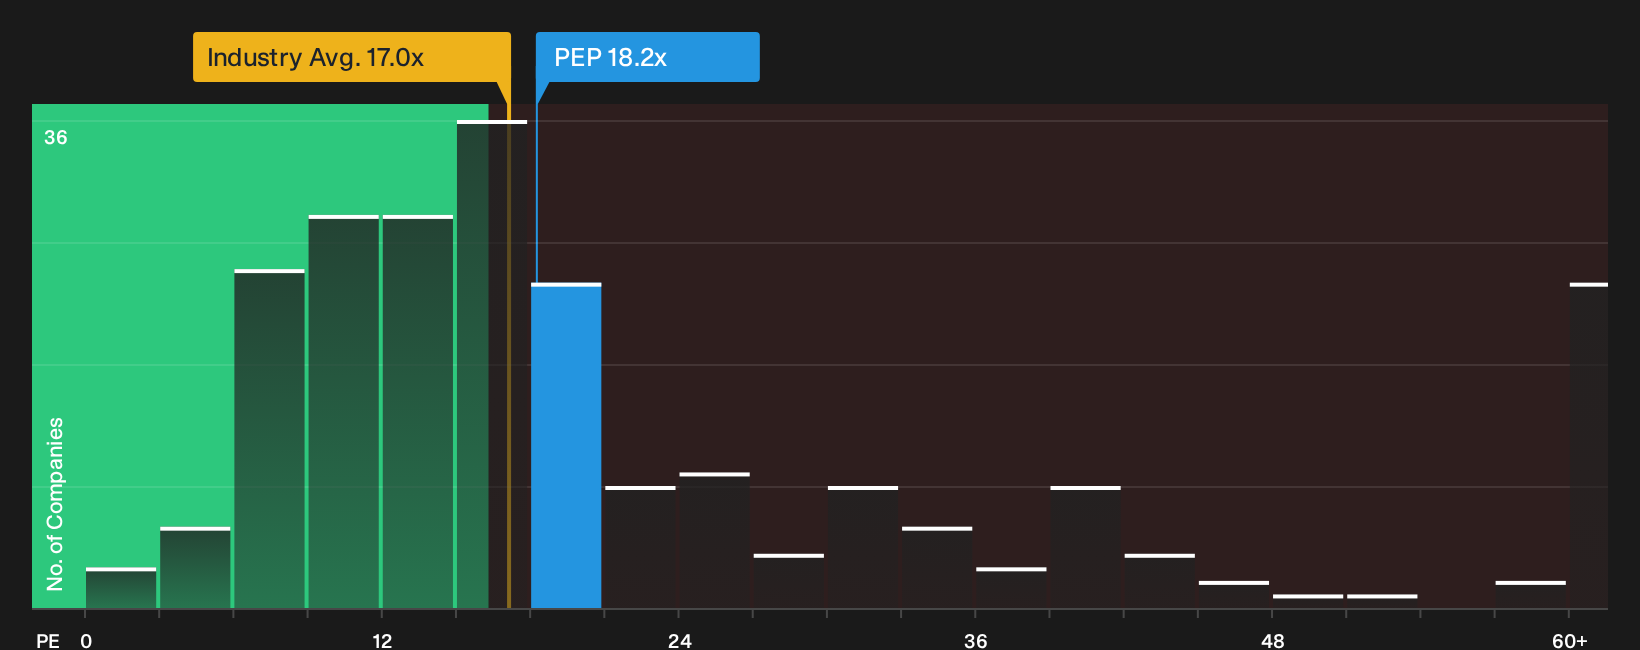
The SWS DCF model points to a large discount, yet the market is not giving PepsiCo away on earnings. The stock trades on a P/E of 18.2x versus 17x for the global beverage group and 31.1x for peers, while the fair ratio sits even higher at 23.8x.
That mix suggests limited room for error if profitability softens, but also leaves a possible upside path if the market edges closer to the fair ratio. Which version of value do you trust when cash flow and earnings send slightly different messages?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on PepsiCo's value story can be useful, not confusing, if you use them as prompts to test your own judgment quickly. To weigh the upside case against the concerns highlighted by the data, start with the 4 key rewards and 1 important warning sign.
Looking for more PepsiCo-sized ideas to research next?
Do not stop at PepsiCo. Use the Simply Wall St screener to quickly surface new opportunities, compare them side by side, and pressure test your own thinking before the crowd moves.
- Zero in on resilient cash generators by scanning a curated list of solid balance sheet and fundamentals (24 results) that can complement a defensive holding like PepsiCo.
- Hunt for potential upside in out of favor stories with a targeted pass through the 20 high quality undiscovered gems before they attract wider attention.
- Dial down portfolio risk by loading up a tailored 31 resilient stocks with low risk scores that filters for sturdier fundamentals when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com