


EN
Why Coherent Stock Is Worth Watching After Raised Revenue Guidance
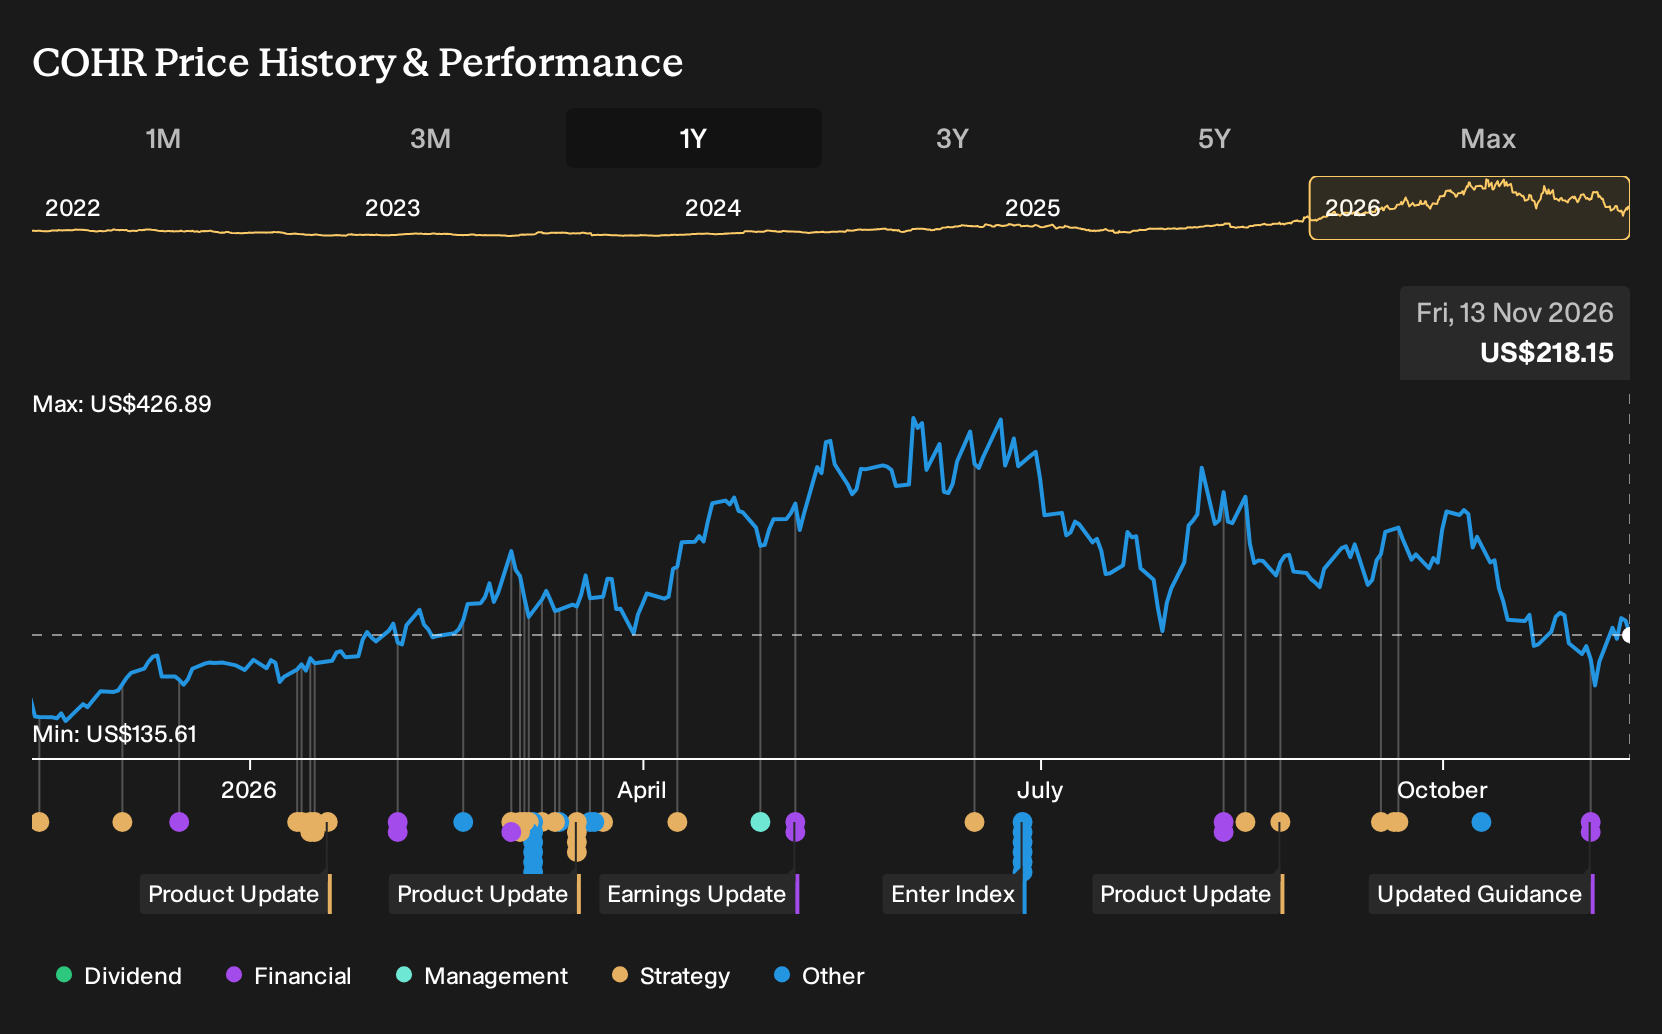
- Coherent reported first quarter fiscal 2027 sales of US$2,370.32 million and net income of US$384.67 million, with both basic and diluted earnings per share from continuing operations higher than a year earlier.
- Management issued second quarter fiscal 2027 revenue guidance of US$2.55 billion to US$2.75 billion and highlighted strong demand for AI datacenter and communications photonics, supported by long term customer agreements and improved cost efficiency.
- The focus now turns to how this stronger AI datacenter driven outlook could reshape Coherent's investment narrative and risk balance.
Coherent Investment Narrative Recap
To own Coherent, you need to believe the build out of AI datacenters and high speed communications can support demand for its photonics portfolio through real cycles, not just one spending spike. The latest quarter showed strong earnings and higher margins, while the new second quarter revenue guide of US$2.55b to US$2.75b keeps that AI centric thesis firmly in play.
The key near term catalyst is execution on that datacom backlog and on long term supply agreements, including scaling indium phosphide and other capacity without eroding profitability. The biggest risk is that heavy capital spending and customer concentration collide with pricing pressure from lower cost rivals, which could squeeze returns if orders slow or mix shifts.
The analyst consensus Narrative on Simply Wall St highlights the AI datacenter build and next generation optics as central to Coherent’s story. That matches what management just pointed to in guidance, where demand for AI datacenter and communications photonics underpins the near term revenue range and recent margin gains.
Against that backdrop, the previously announced multiyear Apple VCSEL agreement looks important to the catalyst mix. It adds another large, long dated demand source that could balance hyperscaler exposure, while also testing Coherent’s ability to keep margins in line as it ramps capital intensive manufacturing and manages competition in high volume optics.
Coherent's narrative projects US$19.3b revenue and US$3.6b earnings by 2029, based on analyst forecasts. That profile assumes 39.4% yearly revenue growth and an earnings increase of about US$2.8b from current earnings of US$769.9m.
Uncover how Coherent's fair value indicates a 78% potential upside to its current price, which could narrow quickly if enthusiasm spreads further across AI hardware plays.
Exploring Other Perspectives
Some of the most bullish analysts focus on PhotonLink as the swing factor for Coherent. They were already pencilling in US$28.6b of revenue and US$5.9b of earnings by 2029, far above the consensus US$19.3b and US$3.6b. You can read this new guidance and earnings beat as a fresh test of which story prevails.
Explore 4 other Coherent fair value estimates, including one that suggests up to 410% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Coherent research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking for more investment ideas beyond Coherent?
Once you have a view on Coherent, it can help to line it up against other stocks that share some of the qualities you care about, whether that is price, balance sheet strength, or risk profile. The Simply Wall St Screener lets you do that quickly so you can see which companies might deserve a spot on your watchlist next.
- If you want to prioritize financial resilience, start with a list of solid balance sheet and fundamentals (24 results) and see which businesses pair strong balance sheets with fundamental support for their operations.
- For readers hunting for potential mispricing, use the 32 high quality undervalued stocks to find companies where current prices sit below their assessed quality and fundamentals.
- If lower risk is your main filter, run a 31 resilient stocks with low risk scores and focus your attention on businesses flagged for more resilient characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com