


EN
How Investors May Respond To Deutsche Börse (XTRA:DB1) Rating Cut
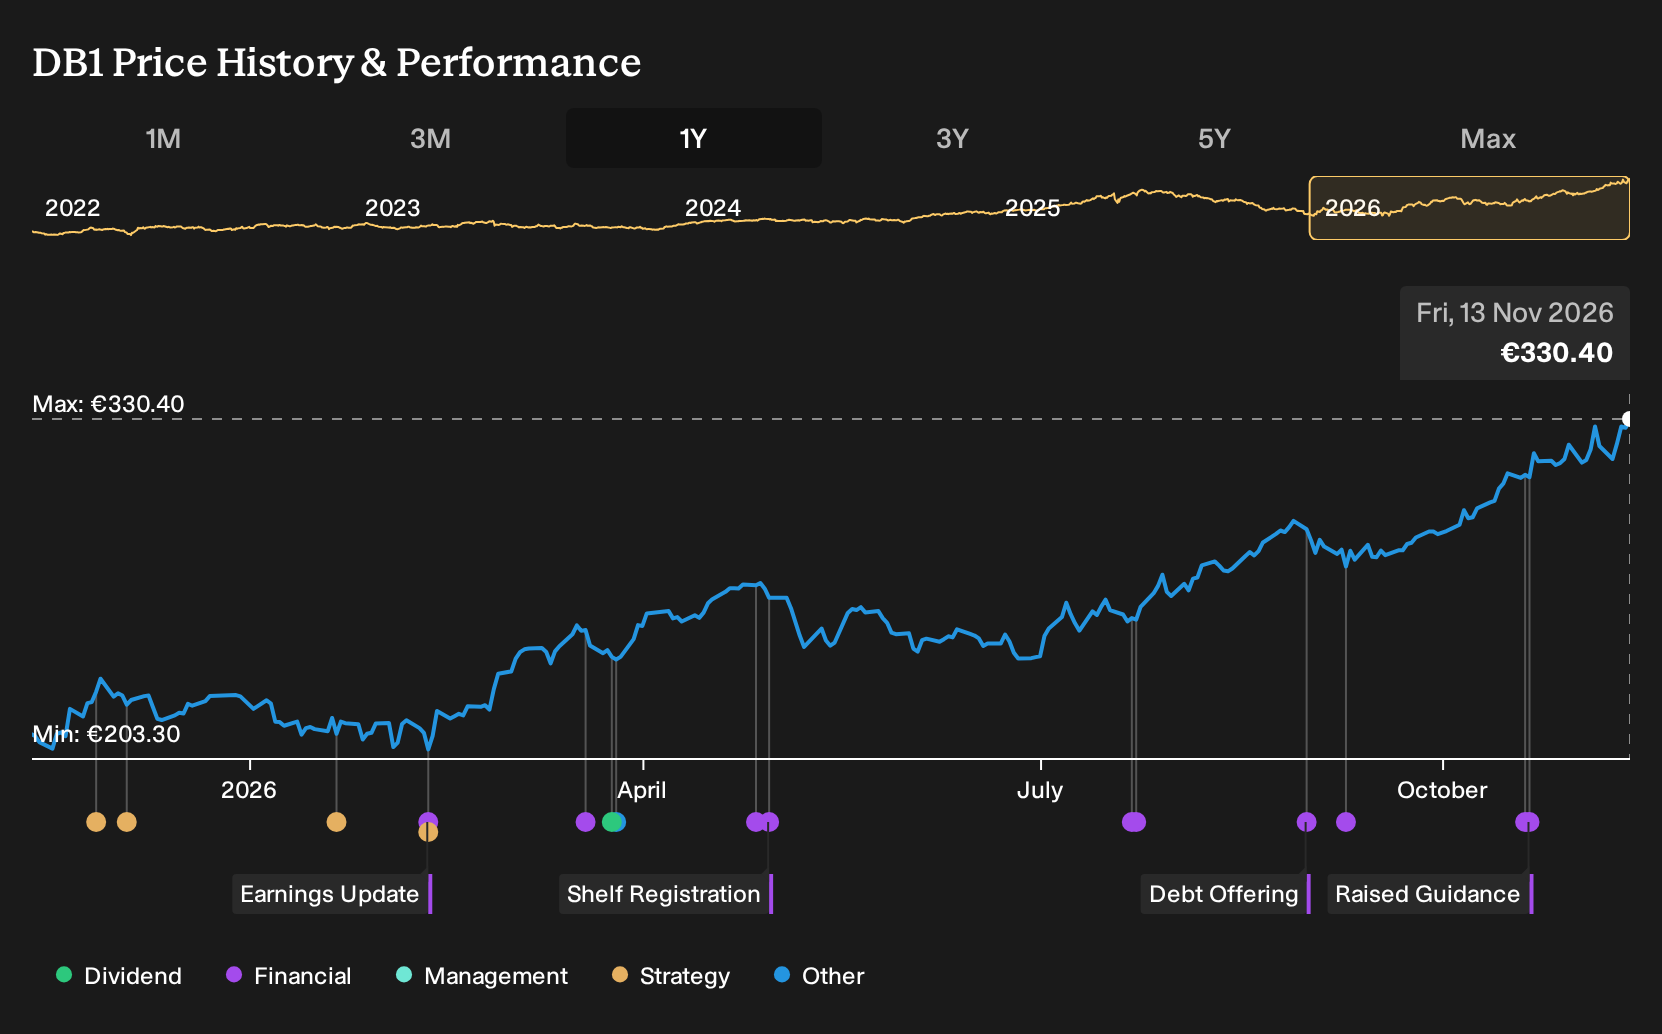
- Barclays recently shifted its rating on Deutsche Börse to equal weight, arguing that recent gains leave the current share valuation reflecting near term growth expectations and a premium multiple.
- The move spotlights how much of Deutsche Börse's expected expansion in technology, data and post trade services may already be embedded in the current pricing.
- This analysis explores how Deutsche Börse's investment narrative aligns with Barclays' view that much of the near term growth is already priced in.
Compare Deutsche Börse's premium valuation story with other potential opportunities by scanning our hand picked 198 high quality undervalued stocks, which the market may be pricing more conservatively.
Deutsche Börse Investment Narrative Recap
To be comfortable as a shareholder in Deutsche Börse, you need to buy into a story of steady earnings, built on market infrastructure, software and data that clients use every single day. The analyst consensus narrative on Simply Wall St leans on earnings that are forecast to grow 8.13% per year and on operating leverage from higher margin post-trade and information services.
That big picture is still intact after the Barclays move. The more immediate swing factor remains trading, repo and collateral volumes, which link directly to fees. The biggest near term risk is that very strong fixed income and repo activity eases, which could soften net revenue growth and make cost control more important.
With no fresh corporate announcements since Barclays’ downgrade, the most relevant reference point for this news is still the planned Allfunds acquisition. Management is targeting €60 million of annual operating cost savings and €30 million of capex savings, which would matter for margins if revenue momentum in areas like ESG indices or fixed income slows.
The way Deutsche Börse executes on Allfunds integration now sits right beside market volumes as a key catalyst. If integration remains complex or synergy capture is delayed, it could be harder to keep underlying cost growth near the 3% framework analysts are watching. That would leave the current premium P/E multiple more exposed to any dip in activity driven income.
Deutsche Börse's narrative projects €7.5b revenue and €2.8b earnings by 2029. This assumes revenue will decrease by 1.2% per year and implies an earnings increase of about €700m from €2.1b today.
Uncover why Deutsche Börse's fair value signals an 8% potential downside to its current price, a premium that may not hold if expectations slip.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about €304.64 and €325.51 per share, which contrasts with Barclays viewing Deutsche Börse as fully pricing in near term growth. When you factor in risks around ESG data demand, fixed income volumes and Allfunds execution, it becomes clear how opinions can diverge sharply. It can be helpful to explore multiple viewpoints before deciding where you stand.
Explore another Deutsche Börse fair value estimate, including one that suggests up to 8% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Deutsche Börse research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Deutsche Börse. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Deutsche Börse's overall financial health at a glance.
Looking for more investment ideas beyond Deutsche Börse?
Once you have a view on Deutsche Börse, it can help to widen the lens and compare it with other companies that meet different return and risk profiles using the Simply Wall St Screener.
- If you want income resilience front and centre, scan for companies that may offer robust payout potential through the 220 dividend fortresses.
- If capital preservation ranks highly for you, consider sharpening your shortlist using the 210 resilient stocks with low risk scores that focuses on businesses with more resilient risk scores.
- If balance sheet strength matters most, build a watchlist around companies highlighted in the list of solid balance sheet and fundamentals (198 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com