


EN
How Expected Earnings Drop At DICK'S Sporting Goods (DKS) Has Changed Its Investment Story
- DICK'S Sporting Goods is approaching its November 24, 2026 earnings release, where analysts expect EPS to decline by 33.33% year over year, while revenue is projected at 21.4% higher than the prior period.
- The combination of lower expected earnings per share and stronger projected sales puts cost structure, promotional intensity, and profit mix under the microscope for DICK'S Sporting Goods.
- This analysis will examine how DICK'S Sporting Goods' investment narrative is shaped by the expected 33.33% EPS contraction despite revenue growth.
Scan how DICK'S Sporting Goods stacks up on earnings pressure and revenue momentum beside hand-picked retailers in our 32 high quality undervalued stocks.
DICK'S Sporting Goods Investment Narrative Recap
An investor in DICK'S Sporting Goods has to believe the core sporting goods chain, plus concepts like House of Sport and GameChanger, can turn solid revenue traction into more consistent profitability again. The expected 33.33% EPS decline alongside 21.4% higher projected sales keeps the focus on cost discipline, mix, and how much margin pressure the business is willing to absorb to support growth.
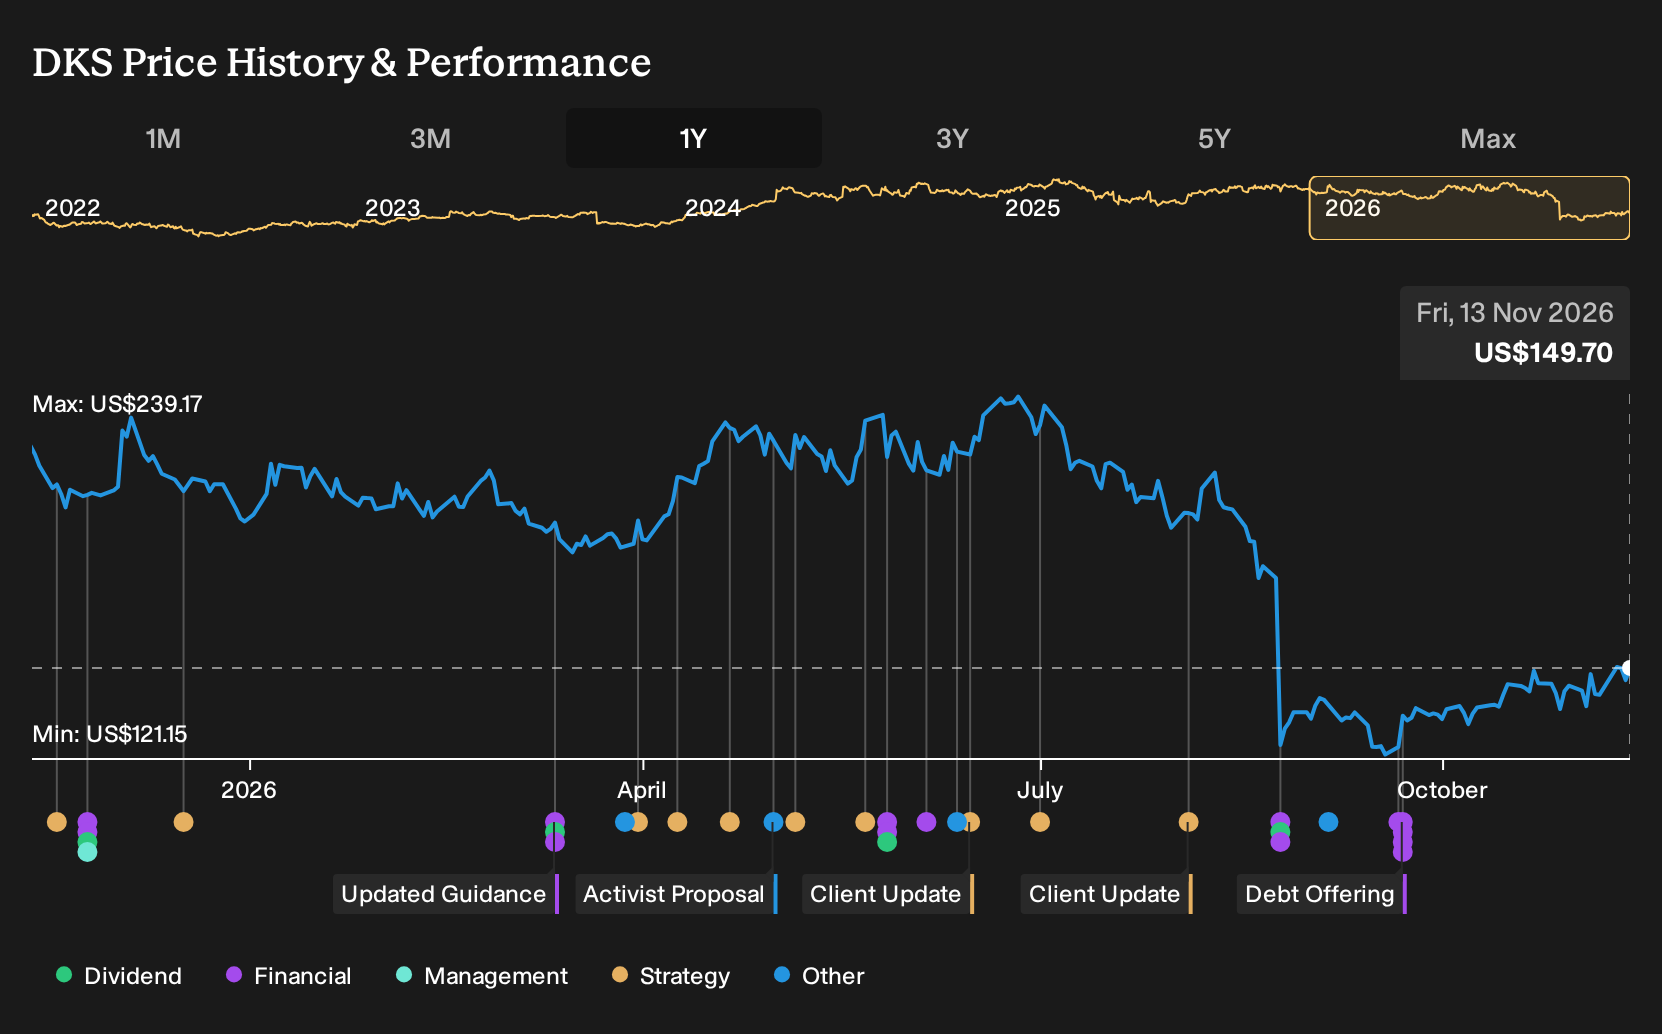
The near term catalyst is simple. Earnings on November 24, 2026 will update you on how the promotional environment, inventory quality, and Foot Locker drag are tracking. A 2.62% share price drop ahead of that report looks more like sentiment noise than a fundamental break in the DICK'S Sporting Goods story.
LunaRodas, a Simply Wall St Community investor who wrote the Narrative, argues that the second quarter 2027 results showed the core DICK'S banner holding up, while Foot Locker and Europe created headwinds. That lens remains useful today. The key question is whether recent promotions in legacy footwear and apparel are still compressing margins or starting to ease off.
LunaRodas also highlighted House of Sport expansion, Fast Break growth, and contributions from GameChanger and the DICK'S Media Network as important revenue and gross margin levers. Those same initiatives sit directly beside the current earnings pressure. Execution in those areas could help offset weaker Foot Locker profitability and give DICK'S Sporting Goods more room to manage promotions without further squeezing returns.
LunaRodas anchors the DICK'S Sporting Goods fair value at $112.77, primarily on the view that the core DICK'S banner, House of Sport, Fast Break, GameChanger, and the DICK'S Media Network collectively justify treating current margin pressure as a temporary cost of sustaining that underlying earnings engine.
Uncover how DICK'S Sporting Goods' fair value indicates a 25% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
Some analysts look at DICK'S Sporting Goods and worry more about ongoing Foot Locker losses than the upcoming earnings date. The most pessimistic cohort modeled up to US$750m in Foot Locker related charges and still only about US$1.0b in earnings on roughly US$23.0b of revenue by 2029. Those estimates were set before this earnings update, so you should expect opinions to shift, and you are encouraged to compare several viewpoints yourself.
Explore 2 other DICK'S Sporting Goods fair value estimates, including one that suggests it could be worth just $157.96.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DICK'S Sporting Goods research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DICK'S Sporting Goods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DICK'S Sporting Goods' overall financial health at a glance.
Looking for more investment ideas beyond DICK'S Sporting Goods?
Once you have formed a view on DICK'S Sporting Goods, it can help to widen the lens and compare it with other opportunities that share similar qualities or offer a different risk profile. The Simply Wall St Screener lets you scan the market quickly using the same kind of fundamentals that underpin this analysis.
- If you want potential upside but still care about quality, start with a curated set of 20 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- If capital preservation and resilience sit higher on your priority list, filter for steadier profiles through a 31 resilient stocks with low risk scores that screens for more defensive characteristics.
- If balance sheet strength matters most to you, focus on companies with cleaner finances using a list of solid balance sheet and fundamentals (24 results) that surfaces firms with healthier debt and liquidity metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com