


EN
Will Earnings Swing Change Genesis Energy's (GEL) Narrative
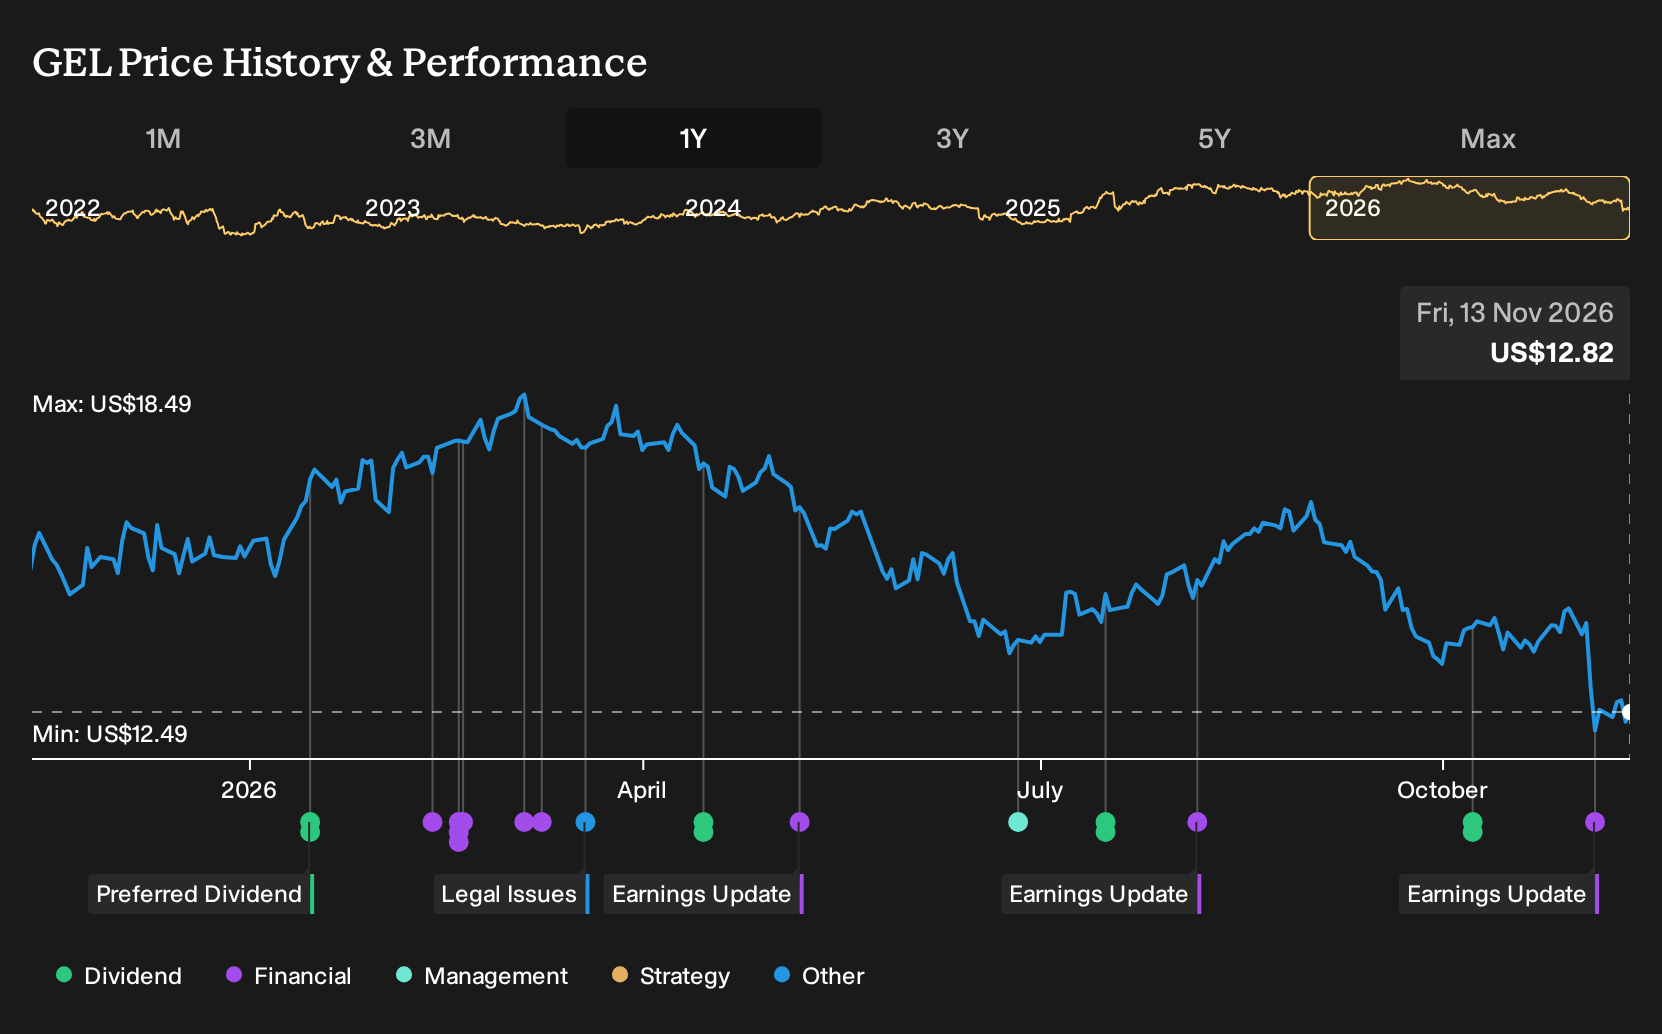
- Genesis Energy reported third quarter 2026 revenue of US$449.25 million and net income of US$2.42 million, with nine month revenue of US$1.43b and net income of US$52.07 million compared with a loss in the prior year period.
- The partnership showed higher sales for both the quarter and year to date, while quarterly profitability tightened and year to date results shifted from loss to profit, presenting a mixed picture of operating momentum and cost control.
- The focus now turns to how Genesis Energy's swing from a year to date loss to profit could reshape the broader investment narrative.
Compare Genesis Energy's earnings swing with a curated short list of infrastructure players that pair meaningful revenue with healthier profit trends using the list of solid balance sheet and fundamentals (24 results).
What Is Genesis Energy's Investment Narrative?
For Genesis Energy, the core belief is that a midstream partnership with offshore pipelines, marine transportation and onshore logistics can turn steady fee based activity into durable cash flows, even if reported earnings stay bumpy. The latest quarter fits that story only partially. Revenue for both the third quarter and the first nine months of 2026 was higher than a year ago, and the swing from a year to date loss to a US$52.07 million profit shows the business can cover its operating footprint when assets are running and pricing holds.
The catch is the quality and resilience of that profit stream. Third quarter net income of US$2.42 million was far lighter than last year and includes the impact of large one off items across the period. At the same time, interest costs and a 6.24% distribution that is not well covered by earnings keep financial risk front and center. In the near term, the key catalysts are fairly straightforward. Investors will watch how consistently Genesis Energy fills its offshore and marine assets, how capital spending is balanced against debt service, and whether recent profitability proves repeatable once those one time gains fade.
Yet tucked inside that apparent turnaround story sits a quieter, structural issue that could matter far more over a full cycle...
There's only one way to know the right time to buy, sell or hold Genesis Energy. Head to Simply Wall St's company report for the latest analysis of Genesis Energy's Fair Value.
Exploring Other Perspectives
Community fair value views on Genesis Energy range from about US$17.67 to US$44.58, based on two independent estimates from the Simply Wall St Community. That wide band reflects how differently private investors weigh the recent swing back to profit. Use those contrasting opinions as a springboard to test your own assumptions.
Explore another Genesis Energy fair value estimate, including one that suggests as much as 248% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Genesis Energy research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Genesis Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Genesis Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Genesis Energy?
If Genesis Energy's mixed earnings story has you thinking more broadly about portfolio construction, it can help to line it up against other businesses with clearer financial profiles. The Simply Wall St Screener lets you filter for the traits that matter most to you, so you can compare this partnership with a wider field of opportunities.
- If capital preservation and steadier profiles are your priority, focus on companies that score well on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for potential mispricings backed by solid business quality, filter for businesses that combine attractive valuations with sound fundamentals using the 32 high quality undervalued stocks.
- If you prefer income at the center of your approach, concentrate on companies with higher yields and more robust payout profiles via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com