


EN
Why ONE Gas (OGS) Is Getting Attention Now
ONE Gas (OGS) set a fresh reference point for investors on November 2 with third quarter earnings, updated full year profit guidance, and a reaffirmed quarterly dividend.
ONE Gas shares have picked up speed around these November results, with a 1-month share price return of 13.25% and a 7-day move of 3.63% taking the stock to $83.86. That short term momentum contrasts with a steadier 1-year total shareholder return of 6.03%, set against much stronger 3-year and 5-year total shareholder returns of 50.22% and 45.77%. This points to a story that has rewarded patient holders more than recent traders.
Scan the utilities space for stocks showing similar earnings momentum and dividend support to ONE Gas by checking our hand picked list of 31 resilient stocks with low risk scores.
After ONE Gas rallied on fresh guidance and a steady dividend signal, the stronger near term share price muddies the picture. Does the current valuation still offer an appealing trade off between risk and reward?
Most Popular Narrative: 1.5% Undervalued
ONE Gas screens as slightly undervalued in the analyst consensus Narrative on Simply Wall St, with a fair value of $85.17 versus the last close at $83.86. This frames a modest potential upside built on regulated growth and capital spending assumptions.
The capital intensive system integrity and expansion plan, including roughly US$800 million of 2026 investments and about US$4.3b over five years with projects such as the 43 mile Western Farmers pipeline, is described as increasing the regulated rate base and supporting future net income and EPS as these assets enter service.
See why 0 investors see ONE Gas as 2% undervalued.
Result: Fair Value of $85.17 (UNDERVALUED)
Still, the ONE Gas story can unravel if heavy capital spending outruns future rate relief, or if operating costs stay elevated relative to management’s 3 to 4% target.
Find out about the key risks to this ONE Gas narrative.
Another View: ONE Gas Looks Priced Richly On Earnings
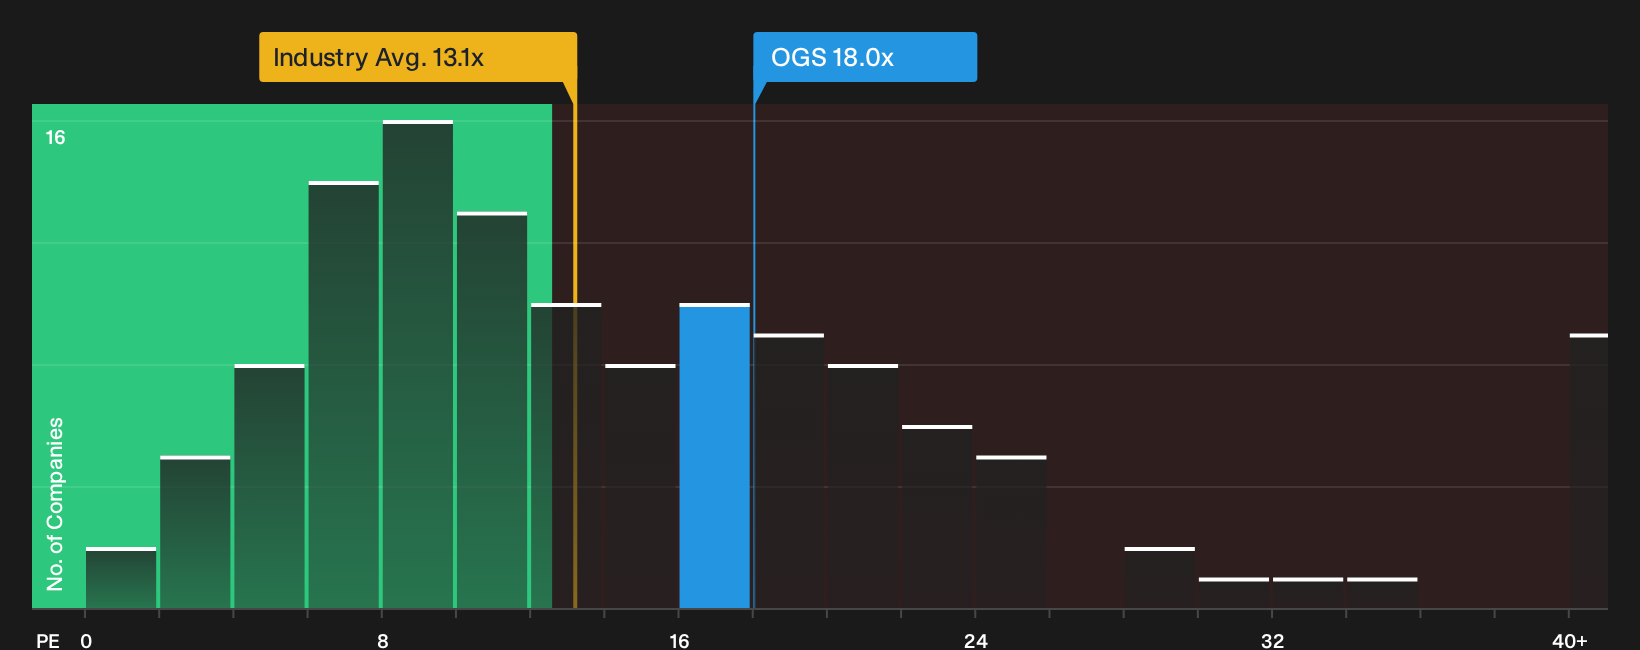
While the Simply Wall St analyst narrative has ONE Gas trading about 1.5% below its $85.17 fair value estimate, the P/E lens tells a harder story. OGS changes hands at 18x earnings, slightly above a 17.9x fair ratio and well above the 12.9x global gas utilities average.
That premium also edges past the 17x peer group level, which means investors are already paying up for the regulated growth story rather than getting it at a discount. If the market eventually leans closer to that fair ratio, how comfortable are you with the valuation risk built into today’s price?
For a closer look at how that earnings multiple stacks up against industry norms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and sentiment can be useful if you are willing to study the details yourself and act before the next inflection point. To evaluate ONE Gas on both sides of the ledger, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ONE Gas?
If ONE Gas sits on your watchlist, treat it as a starting point, not the finish line, and keep widening your opportunity set with fresh candidates.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results), which highlights businesses with fundamentals designed to handle tougher conditions.
- Hunt for pricing gaps using the 32 high quality undervalued stocks to spot companies where market expectations differ from underlying financial strength.
- Build a stronger income stream by reviewing the 6 dividend fortresses and focusing on payouts that align with your tolerance for risk and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com