


EN
What Waters Holders Bought Into
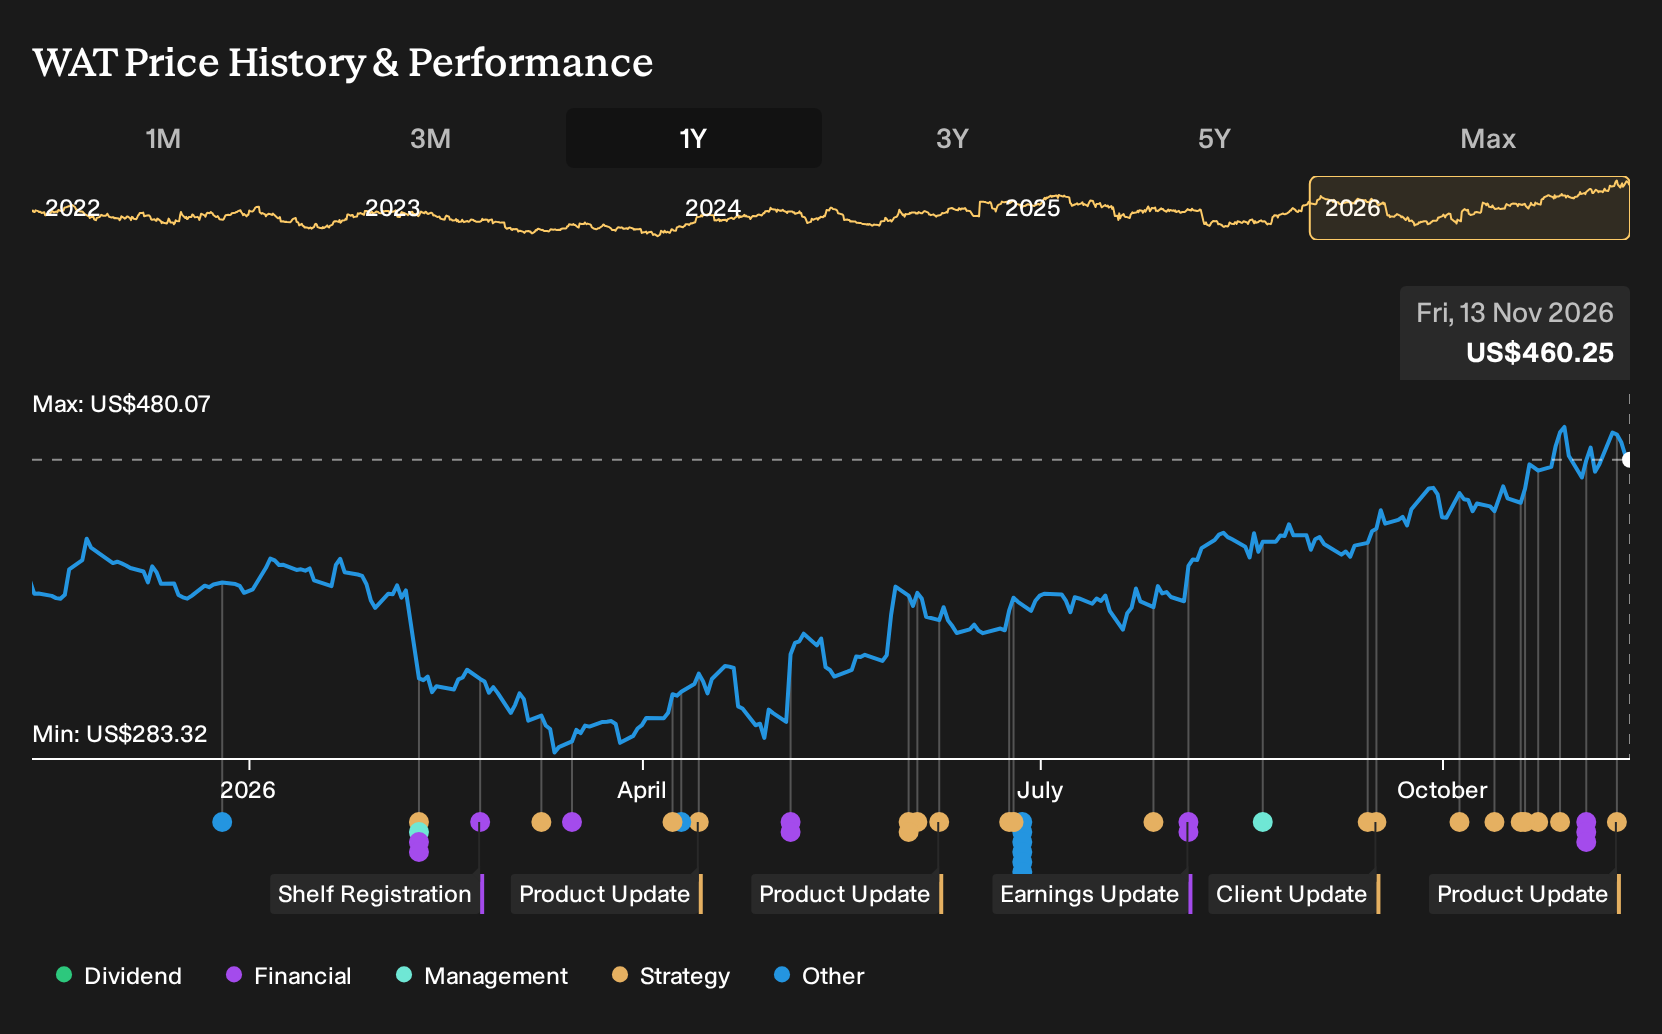
If Waters was on your watchlist rather than in your portfolio, the return may sting. For Waters shareholders, the return over the past year was 21.3%, including dividends. That move arrived as the business pushed deeper into LC-MS and biotech tools, backed by bullish forecasts assuming mid single digit to high single digit revenue growth and higher profit margins. If you were sizing up that expansion into secular healthcare demand back in November 2025, what would have signalled that those assumptions might hold?
This theme extends beyond Waters. See which of 36 healthcare AI stocks may still merit a closer look.
What Waters Investors Were Really Arguing About
The shares cost US$379 at the start of the period, so you were judging whether that price reflected Waters' LC-MS and biotech push or asked too much of it.
The bullish story pointed to a Fair Value of US$424, a price level implied by expectations of 7.0% annual revenue growth and profit margins rising to 25.1%, assuming the expanded workflow portfolio and recurring sales held up.
The more cautious view centred on a Fair Value of US$347, anchored in 6.4% revenue growth, 25.8% margins, and a future P/E of 26.8x as integration and competitive risks stayed front of mind.
What The Waters Evidence Actually Tested
Waters raising full year 2026 revenue guidance after reporting Q3 2026 organic growth of 9% supported the bullish view that LC-MS and biotech tools could sustain higher top line expansion. The same quarter showed revenue at US$1.767b versus US$800m a year earlier, yet net income fell to US$81m and net margin moved from 18.6% to 4.6%. The evidence cut both ways.
The key lesson is simple. When a story leans on margin expansion, do not just track sales or guidance. Watch net income and the reported net margin to see whether scale and acquisitions are actually flowing through to profitability.
What Waters' Run Up Already Assumes
With Waters now at US$460, the bearish analyst Narrative on Simply Wall St places its Fair Value below that level, arguing that the current quote bakes in a lot of execution success across LC and LC-MS, software and the BD carve outs.
At this price you are effectively betting that high single digit organic growth, margin lift from software and synergies, and smoother integration all come through. The question is how those expectations line up with the risks the Narrative highlights around legacy instrument demand, China exposure and complex BD integration.
"The current valuation implies that Waters' multi-year LC/LC-MS replacement and reshoring cycle, Empower and AI software adoption, and the turnaround in acquired BD businesses will translate into durable high single digit growth, expanding margins from synergy capture, and a premium multiple that already prices in these outcomes."
The price and this Narrative do not agree. → Uncover what this Narrative says Waters is actually worth
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 48% below our estimate - targets late-stage therapies for kidney disease, gene editing, acute pain and endocrinology.
- Company 2 - 40% below our estimate - expands biometric eGates and digital identity subscriptions across airports, partners and new use cases.
- Company 3 - 47% below our estimate - channels intensive AI infrastructure spending into ad tools, business messaging and AI hardware experiments.
That is three of the list. See every one of the 32 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com