


EN
Is Kimberly-Clark (KMB) Fully Priced After The Kenvue Deal?
Kimberly-Clark has delivered a 10.6% share price gain over the past year, while reshaping itself through a major acquisition and portfolio changes. With all that activity now reflected in a US$109.43 stock price, the open question is whether the current level is supported by the earnings power of the combined business.
- The 10.6% one year return highlights the idea that Kimberly-Clark's profit stream can justify a higher valuation than investors were willing to pay a year ago.
- The completed Kenvue deal, alongside integration costs and higher leverage, can affect the timing and stability of future earnings, which directly influences how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Kimberly-Clark worth weighing. See what analysts think Kimberly-Clark's shares could be worth.
The issue now is whether Kimberly-Clark's current earnings and their prospects are strong enough to justify the share price investors see today.
If you are weighing Kimberly-Clark's earnings story against similar opportunities, it can help to compare it with companies in 31 resilient stocks with low risk scores.
Has Kimberly-Clark Run Too Far on Earnings?
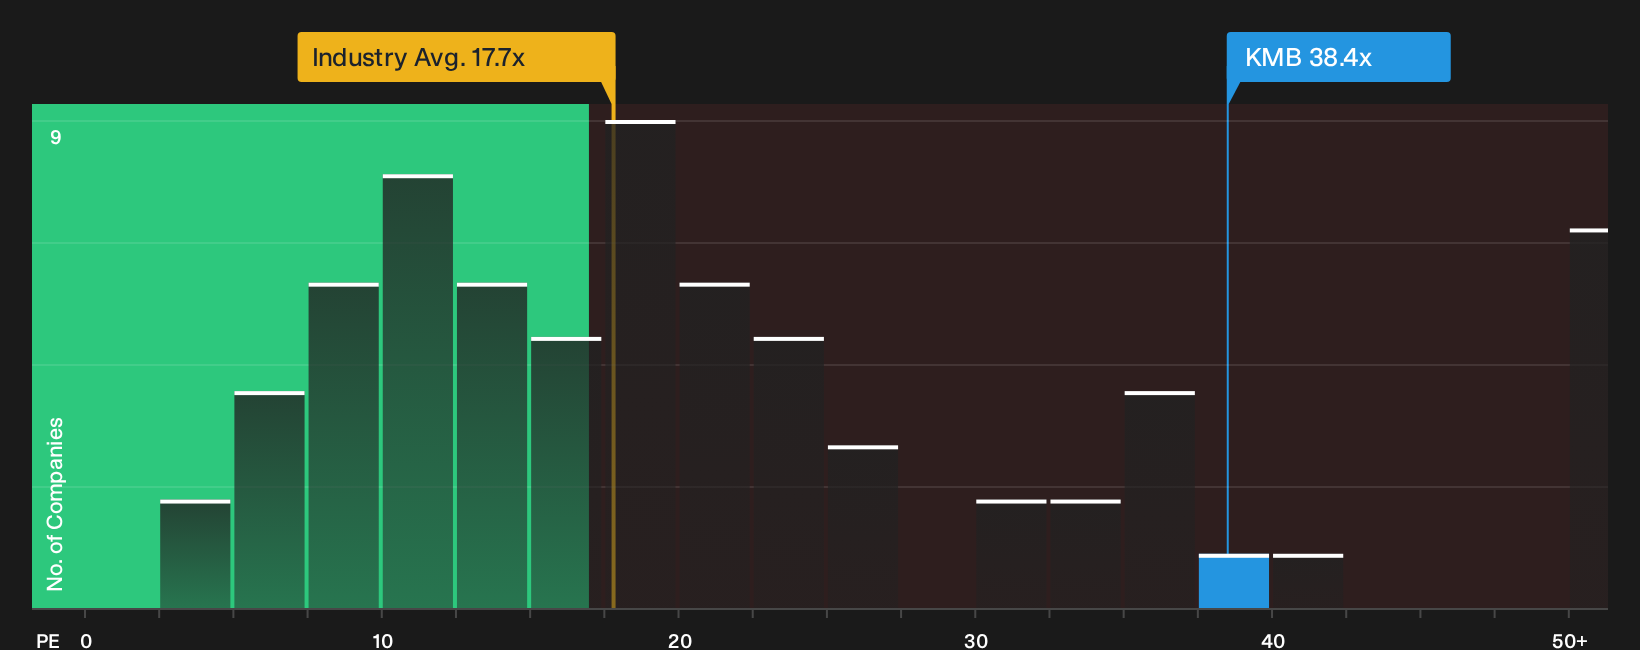
P/E works well for Kimberly-Clark because earnings remain a key anchor for how investors value a mature consumer staples group. The stock trades on a P/E of 38.4x, which is higher than both the Household Products sector average of 17.7x and the peer group on roughly 29.4x. Against these simple yardsticks, buyers are paying a visibly richer price for each dollar of profit than the broader industry commands.
On a more tailored yardstick that blends Kimberly-Clark's growth profile, profitability, size and risk into a single benchmark multiple, the current 38.4x P/E also sits above where that model would place the shares, so the stock screens as overvalued on this framework. Because the recent Kenvue acquisition concentrated expectations on cost synergies and cash generation, the premium valuation suggests the market is already baking in a meaningful level of execution success. Explore the numbers behind Kimberly-Clark's P/E valuation.
The Kimberly-Clark Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kimberly-Clark pick up where the valuation puzzle leaves off. They explain which possible paths for Kimberly-Clark's growth, margins and earnings would need to occur for the current share price to appear high or low. Instead of relying on a single P/E or model headline, each narrative presents the assumptions behind its view of fair value, allowing you to later compare those expectations with the actual results on the Community page.
Bulls see Kimberly-Clark turning its premium mix and cost programs into support for earnings, while bears focus on debt, execution risk and dividend strain.
Bull case: 8% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside in Kimberly-Clark around mix, margins and a reshaped portfolio.
"Continued innovation across premium and mid tier product lines, with mix in major markets already heavily skewed to premium offerings and 10 consecutive quarters of volume plus mix led performance, supports the view that further premiumization can help Kimberly-Clark lift net margins and operating profit even in relatively slow growing categories..."
Discover why this Narrative puts Kimberly-Clark at 8% undervalued.
Bear case: 22% overvalued
The bearish analyst Narrative on Simply Wall St spotlights slower organic sales, higher leverage and tight dividend cover as the pressure points.
"Kimberly-Clark’s long running dividend policy, including a streak of 54 consecutive annual increases that recently consumed about 101% of 2025 free cash flow, leaves limited room for error as the company layers on debt for Kenvue and absorbs input cost headwinds, which could pressure future dividend coverage and constrain retained earnings..."
Explore why this Narrative puts Kimberly-Clark at 22% overvalued.
Kimberly-Clark’s valuation raises one more crucial issue
Price and earnings only tell part of the story for Kimberly-Clark, because independent checks have also highlighted specific areas of concern that investors may want to weigh before taking the next step. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com