


EN
Teekay Tankers (TNK) Stock May Look Reasonable Despite Cyclical Earnings Risk
Teekay Tankers has seen its share price move sharply in recent years, which naturally raises a question for you as an investor. Is the current valuation of the stock properly grounded in the earnings the shipping group is generating today and is expected to produce in the future?
- Over the past 5 years, Teekay Tankers has delivered a return of roughly 7x, so the key issue is whether the profit base has kept pace with that kind of share price performance.
- The business relies heavily on freight rates and fleet utilization, which can shape how consistently its earnings support reinvestment needs and any potential shareholder returns.
- Your read on Teekay Tankers is one view; the desks covering it have another. See what analysts think Teekay Tankers's shares could be worth.
The issue now is whether Teekay Tankers' current share price is adequately supported by the earnings power that investors are effectively paying for today.
If you are questioning whether Teekay Tankers at US$89.43 is giving you enough earnings power for the risk, it can help to compare it with 32 high quality undervalued stocks as another starting point for research.
Is Teekay Tankers a Bargain on Earnings?
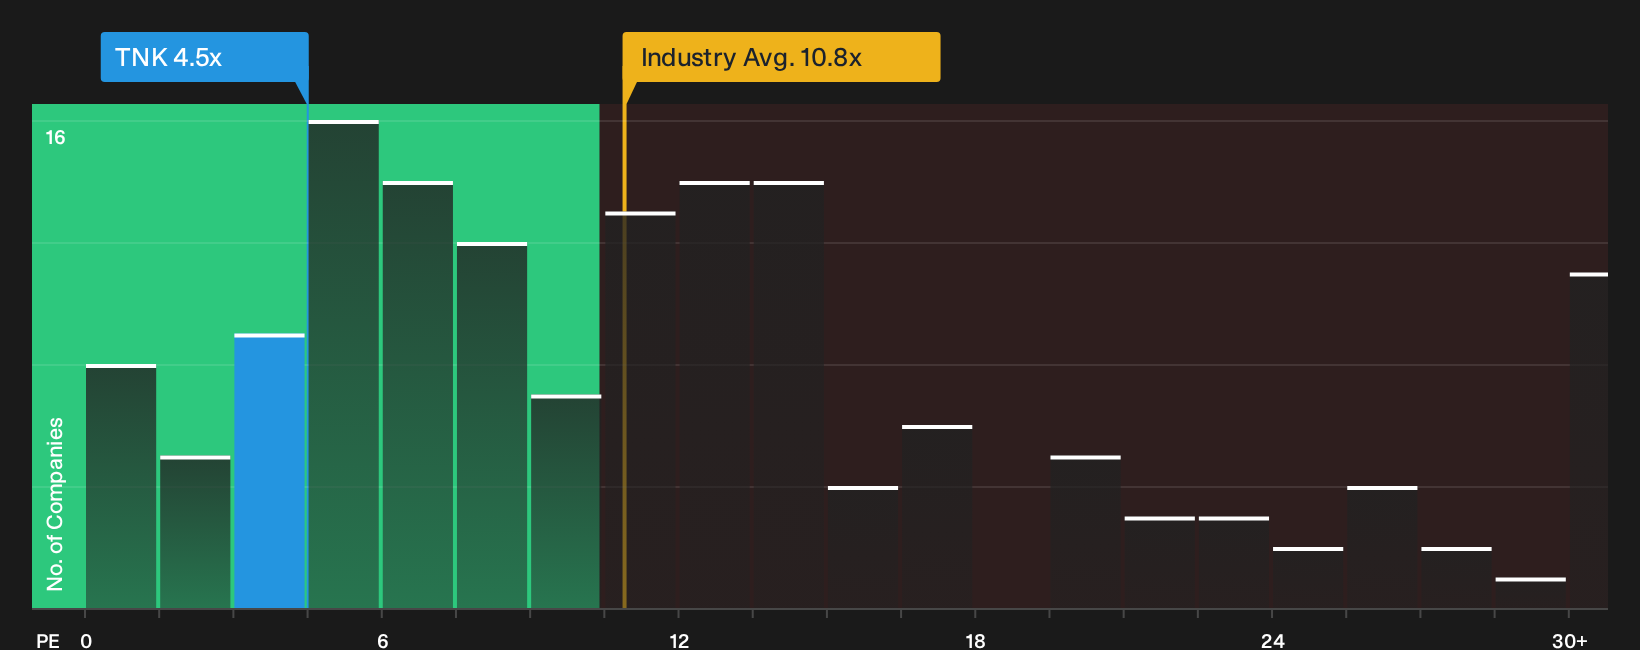
The P/E ratio suits Teekay Tankers because earnings are a key anchor for a shipping operator tied closely to freight markets. On this measure, Teekay Tankers trades on a P/E of 4.5x, compared with an Oil and Gas industry average of about 10.8x and a peer group around 8.3x. That is a sizeable gap for a business whose results are directly visible in the income statement each quarter rather than relying on distant optionality.
The fair multiple implied by the valuation model, which factors in Teekay Tankers' growth profile, profitability, size and risk, points to a higher P/E than the stock currently carries. That leaves the shares at a discount on this earnings yardstick relative to what the model suggests investors might usually pay for this type of cash generation. For you as a shareholder or potential buyer, the key question is whether the earnings base that underpins this low P/E is durable enough to justify potential for a re rating, or simply reflects the market’s caution about future shipping conditions. Explore the numbers behind Teekay Tankers's P/E valuation.
The Teekay Tankers Narrative: What Would Justify Today's Price?
Narratives for Teekay Tankers pick up where the valuation puzzle leaves off and explain what kind of growth, profitability and earnings profile would need to materialise for the share price to sit meaningfully higher or lower than today. Rather than relying on a single multiple or model line, each narrative lays out its own set of assumptions behind a fair value range so you can weigh those inputs against Teekay Tankers' reported results over time.
One of the top narratives on Teekay Tankers: 31% undervalued
This is the bullish analyst Narrative on Simply Wall St, based on the most optimistic analyst price target and forecasts, not one person's view.
"The current valuation suggests that Teekay Tankers’ share price does not fully reflect its recent record free cash flow generation, large cash balance and zero debt position..."
Discover why this Narrative puts Teekay Tankers at 31% undervalued.
One more Teekay Tankers check before you lean on the current price
Before you file Teekay Tankers away based only on today’s multiples and recent returns, it is worth seeing where professional forecasters think the earnings profile could land a few years from now. Explore where analysts expect Teekay Tankers to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com