


EN
How Investors May Respond To Boozt (OM:BOOZT) Earnings Beat
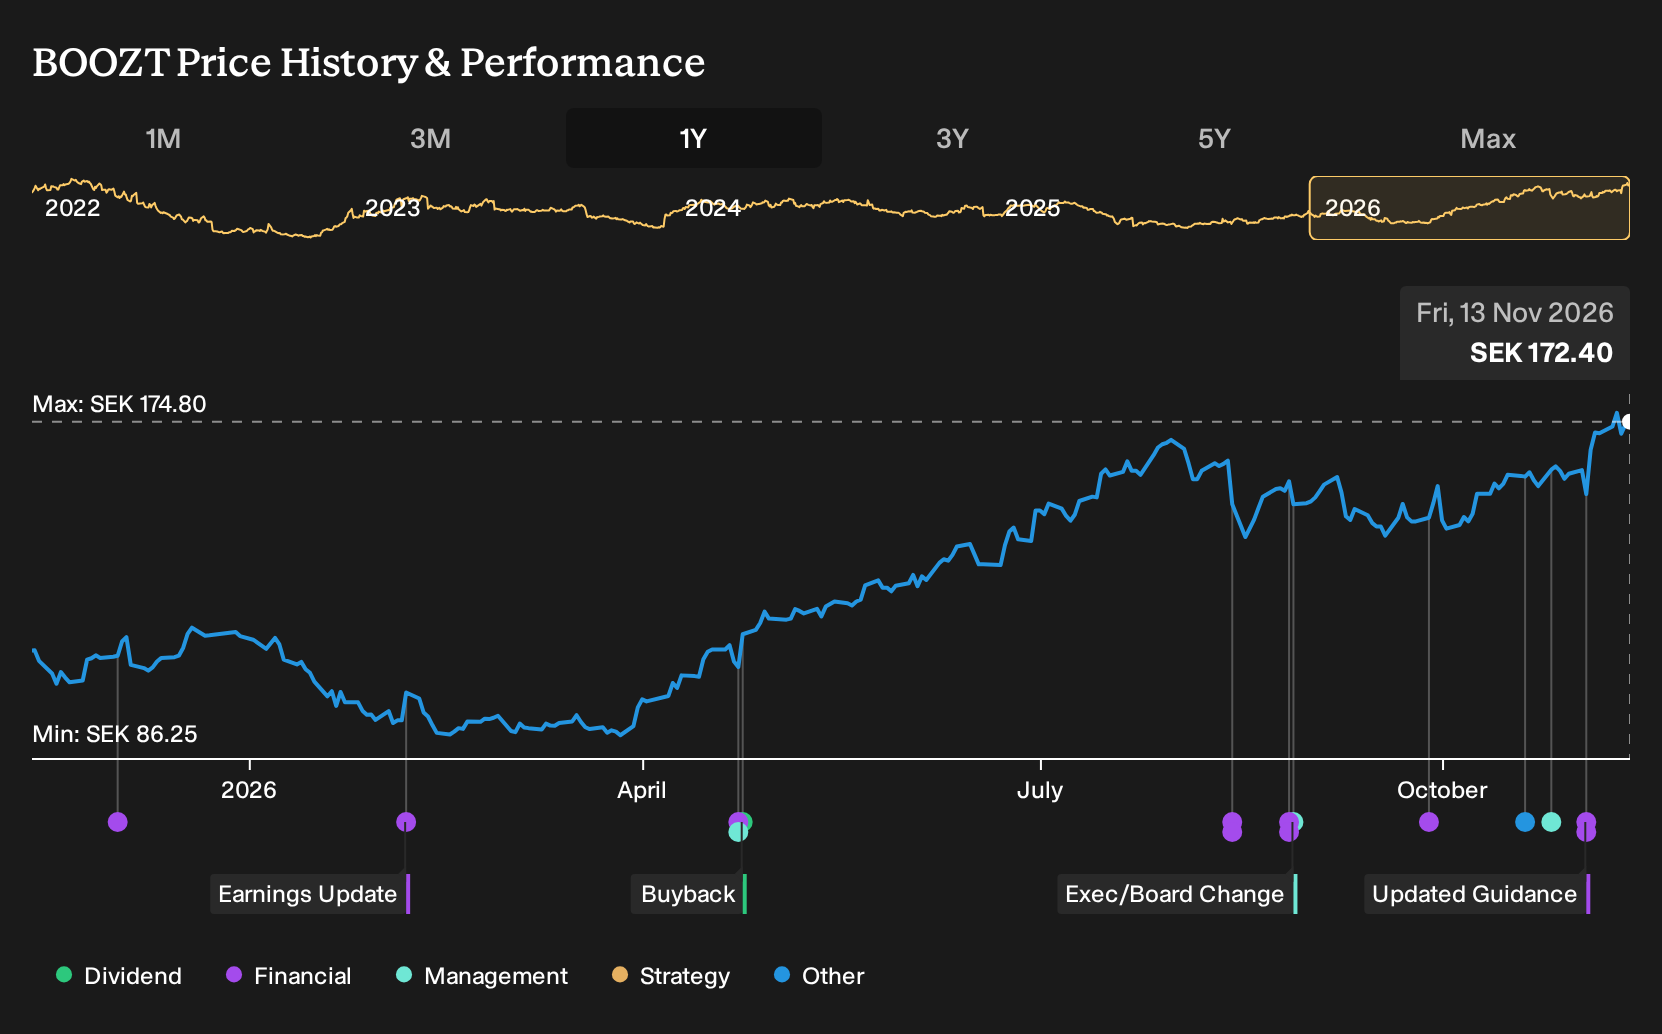
- Boozt reported third quarter 2026 revenue of SEK 1,951 million and net income of SEK 59 million, and confirmed that full year 2026 revenue growth is now expected at the high end of its guidance range.
- The retailer also completed a SEK 221 million share buyback covering 1,669,308 shares, which reduces the share count and increases the focus on per share earnings and cash generation for investors tracking Boozt.
- We will now look at how Boozt's raised full year revenue outlook could influence the existing investment narrative around efficiency and margins.
Compare Boozt's updated guidance with other retailers by reviewing 198 high quality undervalued stocks that have similar revenue momentum and capital return profiles.
Boozt Investment Narrative Recap
To own Boozt, you need to be comfortable with an ecommerce model that leans on premium assortment, cross category shopping and tech driven efficiency to support margins while still investing heavily in growth. The analyst consensus narrative on Simply Wall St focuses on that mix of wider assortment, AI use and logistics upgrades. The raised full year revenue guidance narrows attention on execution quality in the core Nordic footprint.
The near term swing factor remains how product mix, FX headwinds and a higher cost base from the Copenhagen headquarters affect EBIT margins and cash conversion. The main risk is that inventory build, exit tax payments and higher administrative costs keep free cash flow more constrained, which could limit scope for further capital returns.
The most relevant update here is the completed SEK 221 million share buyback covering 1,669,308 shares, equal to 2.81% of the company. That sits alongside Q3 2026 revenue of SEK 1,951 million and net income of SEK 59 million, which together show how management has been willing to combine operational investment with capital returns.
For you as a shareholder, that repurchase programme ties directly to the narrative of disciplined inventory led cash generation supporting per share metrics. With free cash flow in 2026 described as relatively moderate because of exit taxes and inventory build, the completed buyback now serves as a reference point for what the business can fund once those temporary cash uses ease.
Boozt's analyst narrative projects SEK 11.3b revenue and SEK 721.9m earnings by 2029, which assumes 9.7% yearly revenue growth and an earnings increase of SEK 420.9m from SEK 301.0m today.
Uncover why Boozt's fair value is broadly aligned with its current price.
Exploring Other Perspectives
For a different angle, focus on the bullish catalyst that Boozt’s premium, AI supported department store model could drive stronger earnings than consensus assumed before this news. The most optimistic analysts were already pencilling in SEK 11.4b revenue and SEK 761.0m earnings by 2029. You can now ask whether this fresh guidance and completed buyback push those scenarios closer, or if forecasts need a rethink. Analyst opinions can differ a lot, so it can help to compare several views before deciding how Boozt fits your own portfolio approach.
Explore another Boozt fair value estimate, including one that suggests as much as 42% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boozt research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Boozt. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boozt's overall financial health at a glance.
Looking for more investment ideas beyond Boozt?
Once you have a view on Boozt, it can help to line it up against a wider watchlist so you are not relying on a single story. The Simply Wall St Screener lets you quickly surface other companies with traits that match your own risk, income, or quality preferences.
- If resilience comes first for you, start with a 210 resilient stocks with low risk scores that may better match a capital preservation mindset.
- If quality balance sheets matter most, broaden your research with a list of solid balance sheet and fundamentals (198 results) that share Boozt's focus on fundamentals and financial discipline.
- If you are hunting for under-followed opportunities, round out your shortlist by reviewing a 559 high quality undiscovered gems that might complement or contrast with Boozt in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com