


EN
Natural Resource Partners (NRP) Could Be 51% Below Fair Value Following Higher Distribution
Why Natural Resource Partners is Back on Income Investors’ Radar
Natural Resource Partners (NRP) just paired softer third quarter earnings with strong free cash flow, a higher cash distribution of $2.34 per unit, and clear progress on nearly eliminating its remaining debt.
Even with the softer quarter, Natural Resource Partners’ recent news on higher distributions and a shrinking debt load has arrived alongside a clear upswing in the unit price, with an 18.8% year-to-date share price return and a very large 5-year total shareholder return that indicates momentum has been building rather than fading.
Scan royalty-focused income ideas that follow similar themes to Natural Resource Partners’ cash generation and distributions with a curated list of 6 dividend fortresses.
Natural Resource Partners now pairs a richer distribution and lighter debt load with a unit price that has already rerated sharply. Does the current valuation still leave enough upside to justify fresh risk for new buyers?
Price-to-Earnings of 16.3x: Is it justified?
Natural Resource Partners closed at $123.56 with a P/E of 16.3x, which aligns with a business the market is pricing above the broader US Oil and Gas sector average but below closer peers.
The P/E ratio compares what you pay today for each dollar of reported earnings. For a royalty focused partnership like Natural Resource Partners, that matters because earnings quality is flagged as high, profits are real cash backed and the model is less capital intensive than a traditional producer.
There is a tension, though. The stock trades on a richer earnings multiple than the US Oil and Gas industry average of 11.1x. This indicates that investors are paying a clear premium relative to the broader sector. At the same time, the 16.3x P/E sits well below the 27.6x peer average. This signals that the market is applying a discount when you look at closer comparables in similar niches.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 16.3x (ABOUT RIGHT)
Still, Natural Resource Partners relies heavily on coal-linked royalties and has a relatively small Soda Ash segment, so shifts in commodity pricing or regulation could quickly challenge today’s upbeat story.
Find out about the key risks to this Natural Resource Partners narrative.
Another View on Natural Resource Partners’ Valuation
The earnings multiple paints one picture, but Natural Resource Partners looks very different when you shift to the SWS DCF model. From that perspective, the unit price of $123.56 sits well below an estimated future cash flow value of $253.40. This points to a wide potential gap.
That is a large margin for any royalty focused partnership, and it raises a simple question for investors: Is the market correctly discounting earnings that have declined 3.7% per year over 5 years, or is the long term cash generation being mispriced?
Look into how the SWS DCF model arrives at its fair value.
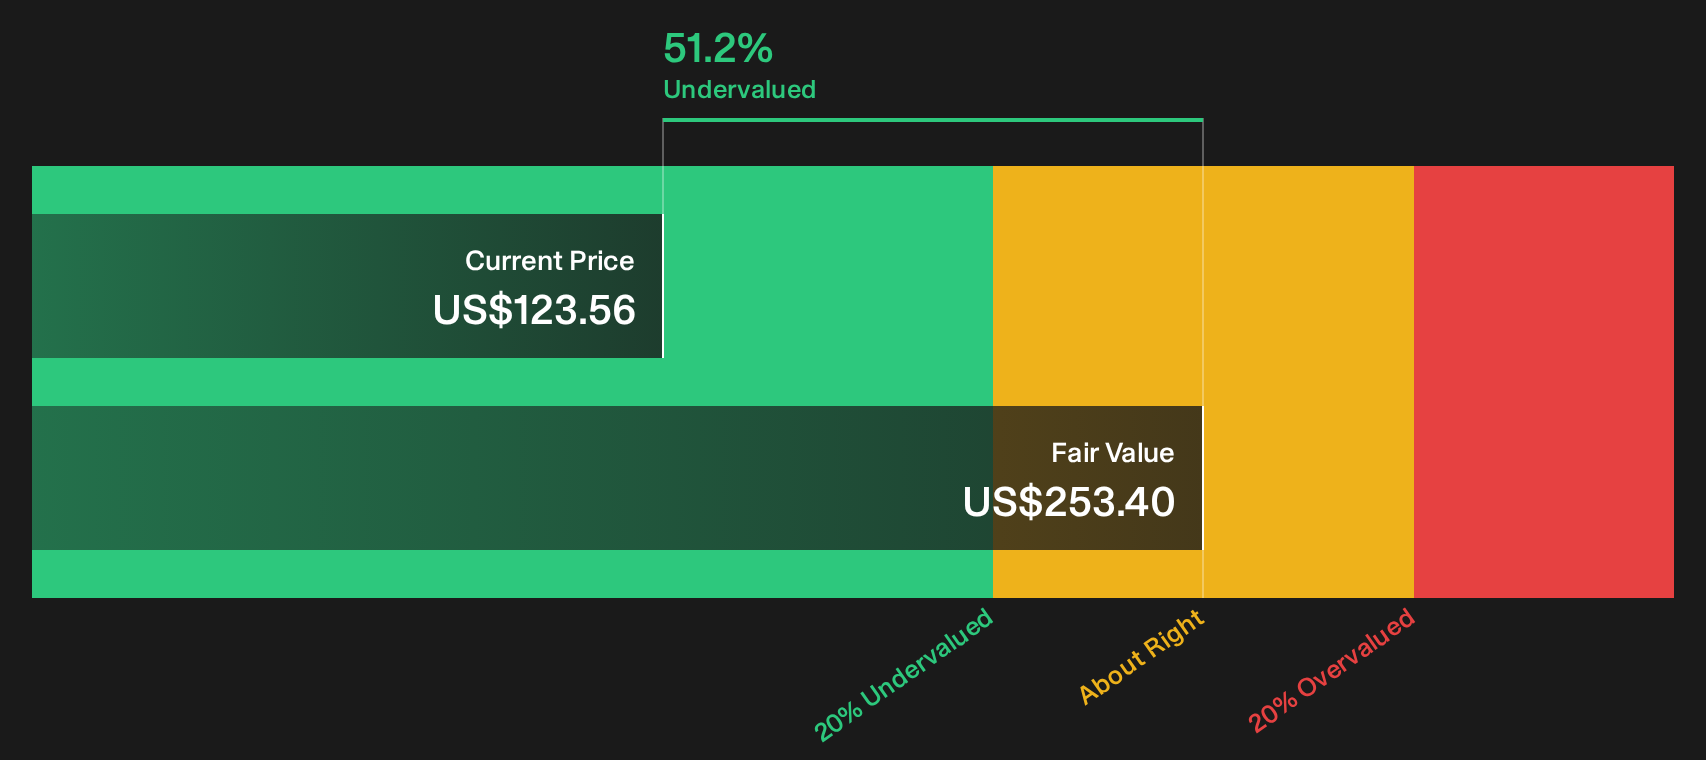
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natural Resource Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Natural Resource Partners’ valuation and income appeal can pull you in both directions. Move quickly to test the numbers, weigh the coal royalty exposure, and build your own thesis around its 1 key reward and 3 important warning signs through 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Natural Resource Partners?
If Natural Resource Partners has sharpened your focus on income and quality, do not stop here. Broader opportunity often sits just outside the obvious watchlist.
- Target resilient potential compounders by scanning a curated 32 high quality undervalued stocks that pairs solid fundamentals with prices the market has not fully reflected yet.
- Strengthen your capital base by focusing on balance sheet resilience through a focused list of solid balance sheet and fundamentals (24 results) before conditions test weaker businesses.
- Spot tomorrow’s potential leaders early by combing through a hand picked 20 high quality undiscovered gems before wider attention narrows the gap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com