


EN
Will Job Cuts And NBCUniversal Separation Change Comcast's (CMCSA) Narrative
- Comcast has already connected more than 1,400 previously unserved and underserved homes and businesses in Monongalia County, West Virginia to multi gigabit, symmetrical fiber, with a public private build targeting over 2,700 locations by the end of 2026 and funded in part by the American Rescue Plan Act.
- During the same period, the company has implemented restructuring moves, including more than 1,000 cable and broadband job cuts and the separation of NBCUniversal. It has also intensified its focus on connectivity, streaming, and theme parks as Comcast responds to broadband pressure and reshapes where capital is committed.
- This article will examine how Comcast's investment narrative could be affected by this restructuring push, including broadband layoffs and the NBCUniversal separation.
Comcast Investment Narrative Recap
To own Comcast, you need to believe the connectivity engine can offset pressure in legacy video and slower experiences. The analyst consensus Narrative on Simply Wall St leans on converged broadband, wireless, streaming and parks to keep cash flow resilient even as headline revenue is expected to drift slightly lower. The Monongalia County fiber build fits that story, though on its own it is too small to shift the near term picture.
Right now, the key swing factor is whether broadband subscriber and pricing trends can hold as fiber and fixed wireless rivals push aggressive everyday offers. The biggest risk is that heavier competition and Comcast's higher debt load squeeze margins further, after net profit margins already moved lower versus last year.
The West Virginia project matters most as proof of Comcast still putting real money into higher quality connectivity, including multi gigabit, symmetrical fiber and bundled services. That lines up with the catalyst in the analyst consensus Narrative on Simply Wall St that focuses on DOCSIS 4.0 upgrades, gig+ speeds and better WiFi as tools to support broadband and mobile bundles.
This build out also speaks to execution risk. Management has to deliver these rural and semi rural expansions on time and on budget while restructuring, handling more than 1,000 job cuts and separating NBCUniversal. If integration of new fiber markets, mobile, security and streaming goes smoothly, it can support the case that connectivity and bundles remain the core driver of Comcast's outlook.
Comcast's narrative projects US$119.0b revenue and US$10.9b earnings by 2029, based on analyst estimates. This assumes revenue shrinks by 1.1% per year and earnings decline by US$0.4b from US$11.3b today to reach that 2029 consensus figure.
Uncover how Comcast's fair value indicates a 12% potential upside to its current price, which may not last much longer.
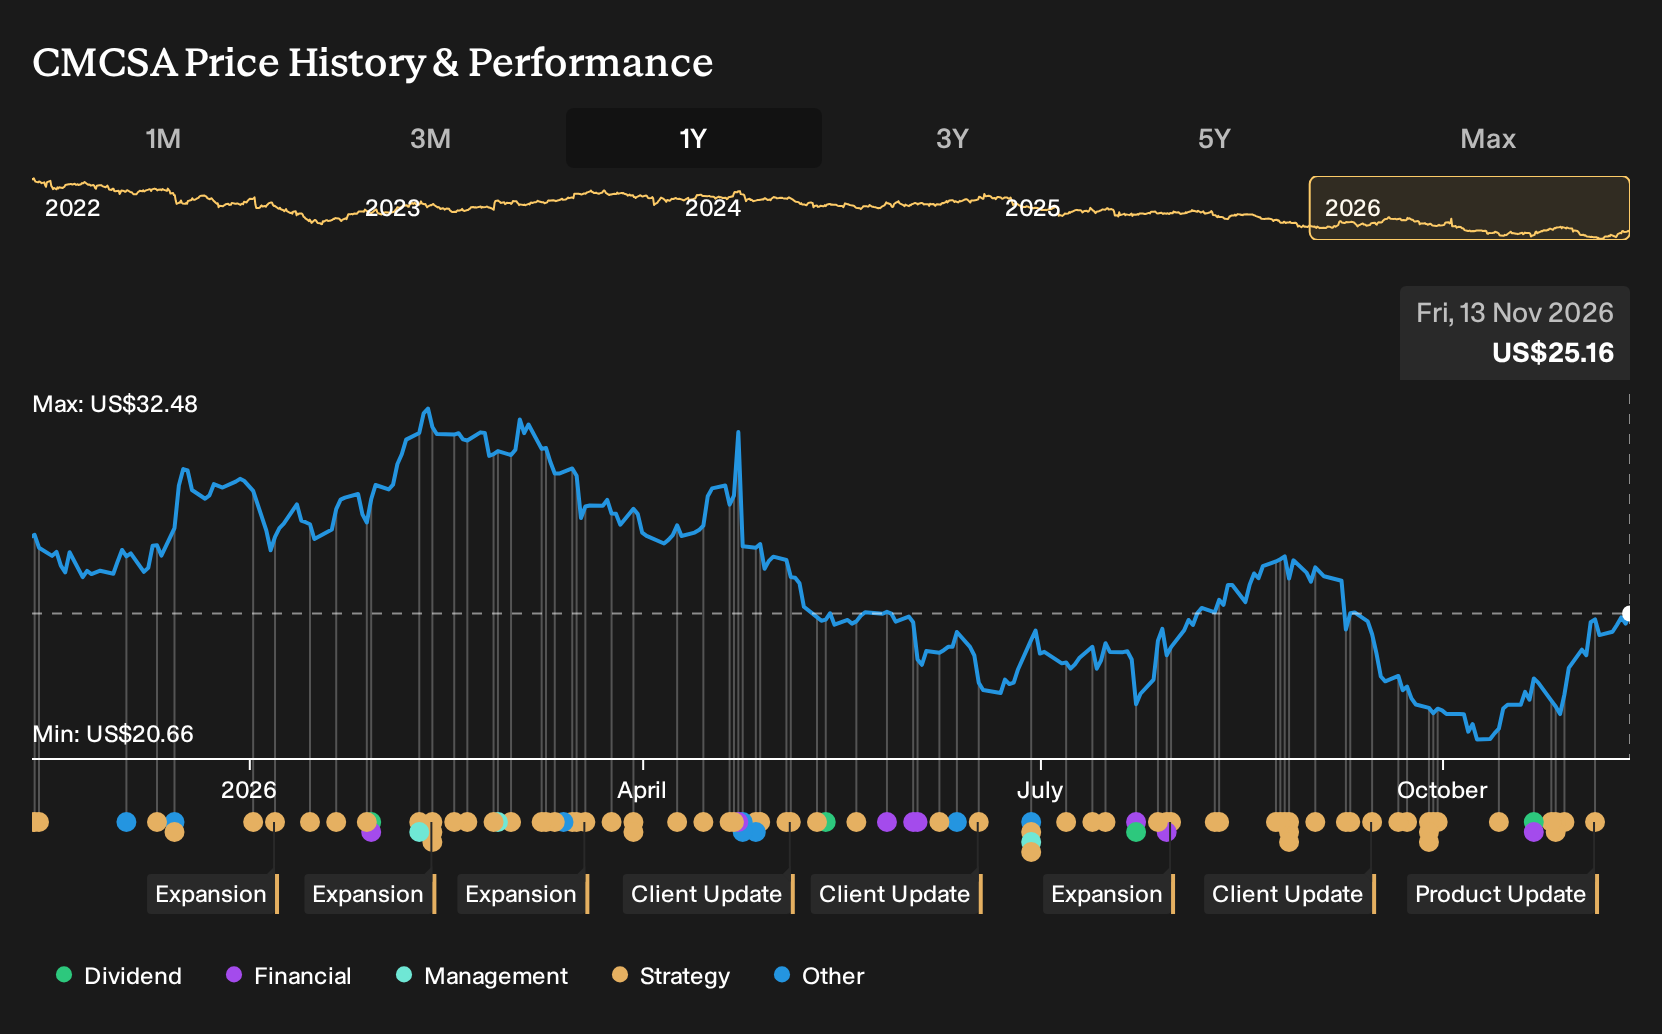
Exploring Other Perspectives
Comcast’s rural builds look encouraging, yet the most pessimistic analysts still flag broadband economics as the pressure point. Before this news, the lowest forecasts were for revenue to reach about US$116.6b and earnings of US$9.8b by 2029, well under consensus. That gap shows how far opinions can diverge. It is therefore worth exploring both narratives yourself.
Explore 5 other Comcast fair value estimates, including one that suggests as much as 32% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Comcast research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Comcast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comcast's overall financial health at a glance.
Looking For More Ideas Beyond Comcast?
Once you have a view on Comcast, it can help to cross check that thesis against other companies with different risk and return profiles using the Simply Wall St Screener.
- If you prefer resilient balance sheets and steadier fundamentals, scan our list of solid balance sheet and fundamentals (24 results) to see which businesses match that profile.
- If potential mispricing is your focus, review the 32 high quality undervalued stocks that combine stronger cash flows with what the model views as attractive prices.
- If you are hunting for opportunities that attract less attention, sift through the 20 high quality undiscovered gems and compare their qualities with what you see at Comcast.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com