


EN
What Coloplast (CPSE:COLO B)'s Earnings And Guidance Mean For Shareholders
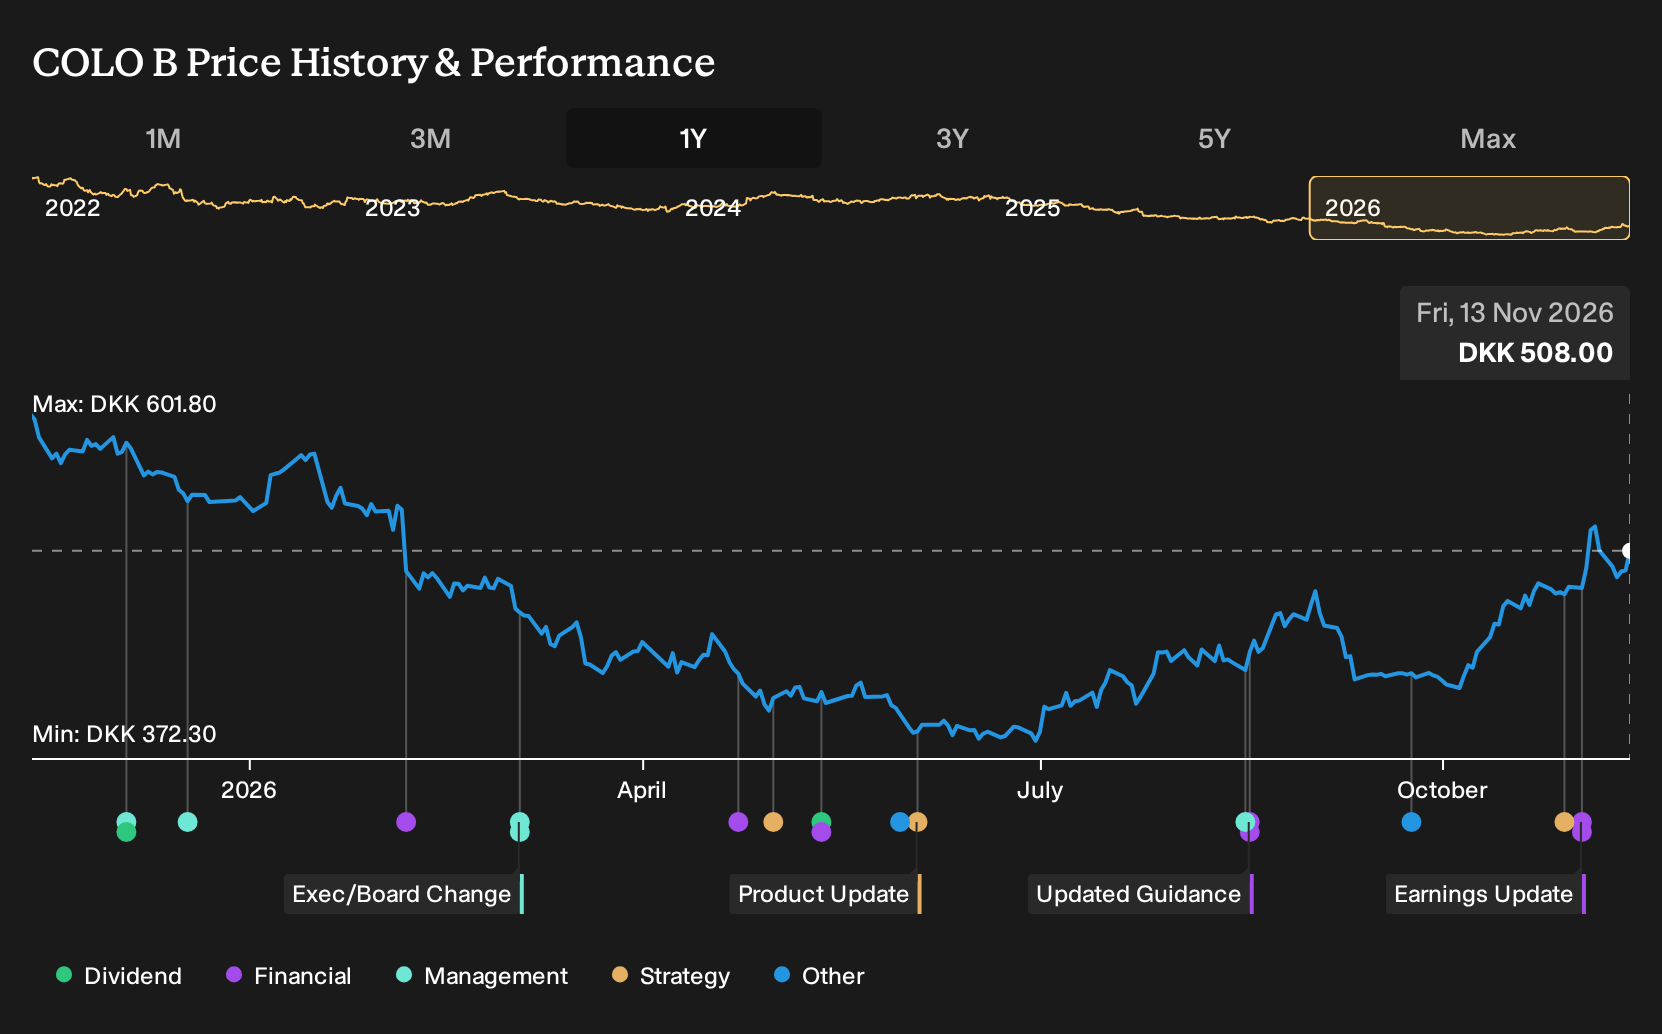
- Coloplast reported Q4 2025/26 sales of DKK 7,459 million and net income of DKK 1,186 million, with full-year revenue of DKK 28,941 million and net profit of DKK 3,074 million, alongside detailed EPS figures for both periods.
- The full-year net income and EPS outcomes, combined with new guidance for 2026/27 calling for 7% to 9% reported revenue growth and a currency tailwind to EBIT margin, sharpen the picture of how Coloplast is balancing topline expansion with profit quality.
- We will now see how Coloplast's earlier investment case intersects with fresh guidance for 7% to 9% reported revenue growth.
Scan how Coloplast's latest guidance compares with peers by lining it up beside our hand picked 210 resilient stocks with low risk scores with resilient earnings profiles.
Coloplast Investment Narrative Recap
To stay a shareholder in Coloplast, you need to believe the core chronic care franchises can keep compounding while newer units stabilise. The latest Q4 figures showed higher quarterly sales and profit, yet full year net income and EPS were lower than the prior year, so the key question is how clean that earnings base now is after the large one off items.
According to RisbergCapital, an investor in the Simply Wall St Community, the near term catalyst is clearer execution on guidance and margin quality. The new outlook for 7% to 9% reported revenue growth, with a currency lift to EBIT margin, keeps that catalyst intact. The biggest current risk remains balance sheet stretch and earnings volatility around acquisitions rather than the underlying ostomy and continence engine.
The guidance for 2026/27 is the announcement that matters most here. Coloplast now points to 7% to 9% reported revenue growth, including around a 2 percentage point currency benefit, plus up to a 50 basis point currency tailwind to the EBIT margin. That frames expectations for how quickly the group aims to re build earnings momentum after a year where net profit and EPS moved in the wrong direction.
For you, the link to catalysts is straightforward. If the chronic care units can deliver organic expansion within that guidance band while biologics and interventional urology avoid fresh setbacks, confidence in the Impact4 plan should slowly improve. If growth or margins undershoot again, concerns flagged by RisbergCapital about acquisition execution and leverage could move back to the foreground, even if demand in the core franchises remains steady.
On RisbergCapital’s math, fair value clusters near DKK685.00 per share, because the probability weighted scenario work, including segment level modelling and assumed exit multiples on EBIT, points to a blended intrinsic value well above the current enterprise value even without aggressive growth assumptions.
Uncover why Coloplast's fair value indicates a 35% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different potential catalyst for Coloplast. They emphasise the cost savings program and new plants, arguing that if these efficiencies land, the business could support stronger earnings than the baseline narrative assumes. Before this earnings release, that camp was modelling revenue of DKK 35.7b and earnings of DKK 7.3b by 2029. Those estimates underpin an upbeat view that margins could reach 20.3% and still justify a P/E of about 21x. That is a considerably more optimistic story than the baseline, and it shows how far opinion can stretch. Use these more bullish forecasts as one reference point, and then compare them with other scenarios to decide which version of Coloplast’s future you find more realistic.
Explore 4 other Coloplast fair value estimates, including one that suggests up to 38% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Coloplast research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Coloplast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coloplast's overall financial health at a glance.
Looking for more Coloplast sized investment ideas?
If the Coloplast story has sharpened your thinking about quality, risk and price, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- For investors who care most about stability and capital preservation, consider a 210 resilient stocks with low risk scores that historically show more resilient performance when conditions get choppy.
- If value is your priority, weigh Coloplast against a 198 high quality undervalued stocks that combine solid fundamentals with prices that appear modest relative to their financial profile.
- Income focused portfolios might benefit from comparing Coloplast to 220 dividend fortresses that offer higher yields while still aiming to keep payout strength in view.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com