


EN
What Invesco Holders Bought Into
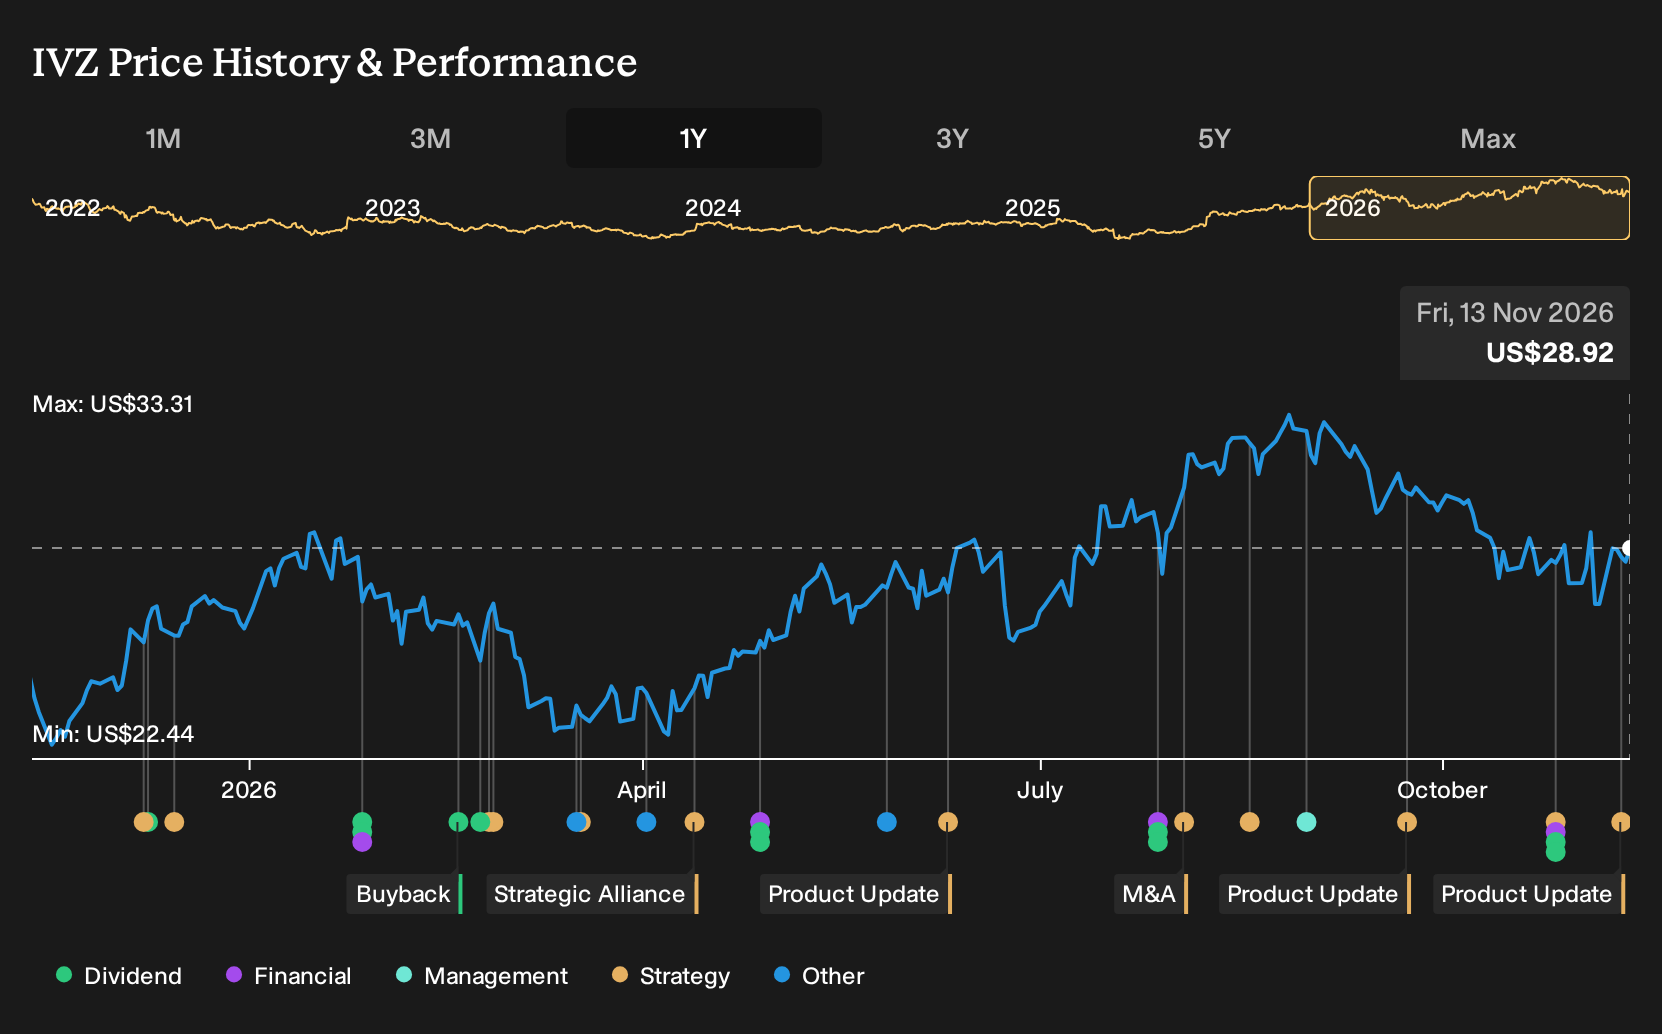
Holding Invesco over the past year would have returned 26.7%, including dividends. If you had bought on 13 November 2025, you would have been weighing very different signals. Bulls pointed to global aging, passive investing, and the MassMutual and Barings partnership as a way into retirement alternatives. Bears focused on fee pressure, active outflows, and rising competition in QQQ. Which of those pressures now looks more important to you?
The easy part of this move is behind Invesco. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Arguing About On Invesco
The shares cost US$23.98 at the start of the period, so anyone looking at Invesco had to decide which story felt more realistic.
The bullish narrative pointed to a Fair Value of US$27.61. This price was implied by assumptions such as revenue declining 6.2% a year while profit margins rose toward 24.0% on the back of global aging and passive investing.
The bearish camp saw a Fair Value of US$17.03. This was based on expectations of revenue falling 7.0% a year and profit margins settling near 21.9% as fee pressure and passive migration weighed on the business.
What The Results Changed For The Invesco Debate
Invesco reported Q3 2026 revenue of US$1,873.2 million, above the US$1,640.4 million recorded in Q3 2025, which supported the bullish focus on scale and global inflows. Net income slipped from US$301.3 million to US$294.5 million and net margin moved from 18.4% to 15.7%, which kept the bear case on fee pressure and mix very much alive. Overall, the evidence cut both ways.
The whole argument hinged on whether higher assets and product launches would outweigh thinner fee yields. When you look at another asset manager, track net inflows alongside net margin. That pairing tells you whether growth in assets is translating into sturdier profitability or simply delivering lower-fee volume.
What You Are Paying For In Invesco Now
Invesco now trades at US$28.92, so the analyst consensus Narrative on Simply Wall St places its Fair Value above the current price rather than below it.
That view leans on a shift toward ETFs, SMAs, model portfolios and private markets. Investors would need to judge whether sustained organic inflows and healthier margins really hold.
"The current valuation, according to this narrative, implies the share price does not fully reflect the combination of record AUM, consistent net long-term inflows, expanding operating margins, and planned EPS accretion from preferred stock redemptions, and therefore characterizes Invesco as undervalued with a positive outlook."
The price and this Narrative do not agree. → Uncover what this Narrative says Invesco is actually worth
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 36% below our estimate - targets AI-driven freight and customs tasks as regulatory compliance complexity increases.
- Company 2 - 48% below our estimate - supplies integrated accelerated computing systems tailored to large-scale artificial intelligence infrastructure expansion.
- Company 3 - 39% below our estimate - converts fast-turn subsea development work into higher-margin equipment packages and follow-on services contracts.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com