


EN
Obayashi Stock Eyes Raised Outlook After Earnings Upgrade
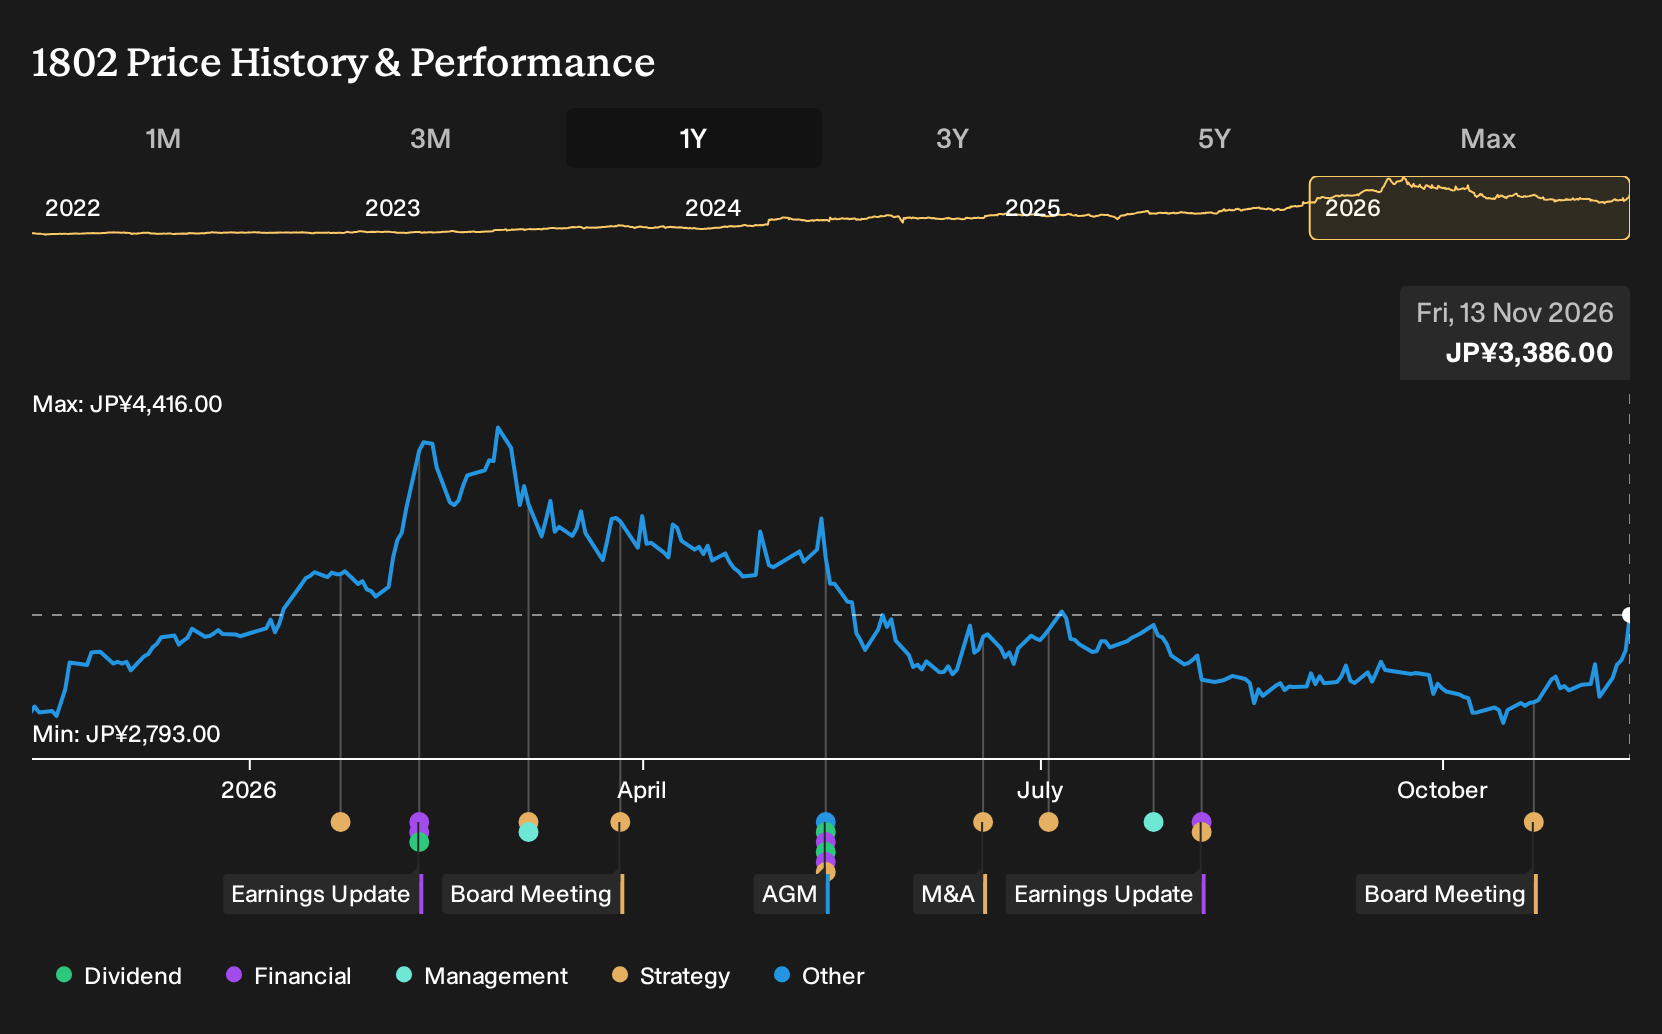
- Obayashi Corporation approved a share repurchase program of up to 20,000,000 shares for ¥30,000 million, raised full year earnings guidance on both consolidated and non consolidated bases, and announced a higher interim dividend of ¥47 per share for the quarter ended September 30, 2026.
- The combination of a stronger profit outlook, cancellation of repurchased shares, and a higher cash payout signals management’s focus on capital efficiency and on returning surplus funds to shareholders, alongside ongoing construction and M&A activity.
- The next area of focus is how Obayashi’s broader investment narrative is shaped by the upgraded earnings guidance just issued by management.
Scan how Obayashi’s buyback and higher dividend compare with other companies returning surplus cash through disciplined capital management by reviewing the curated 28 dividend fortresses.
What Is Obayashi's Investment Narrative?
To own Obayashi, you need to be comfortable with a construction-led group that leans on large projects, complex execution and sizeable capital needs, while still trying to keep returns respectable. The upgraded guidance points to stronger activity in domestic building work and better gross margins on completed contracts, helped by customers pulling forward decisions in response to labor shortages. The Multiplex acquisition adds more overseas volume, which supports the revenue story but can also raise integration and cost discipline questions in the near term.
The new buyback, dividend lift and the move to localize U.S. civil engineering under OCNA all sit in the same bucket: management tightening capital use while pushing profit from operations rather than financial engineering alone. For the short run, key swing factors stay quite practical, including construction schedules holding, pricing on change orders, and whether higher personnel and M&A expenses eat into the upgraded profit targets.
Even so, there is a less comfortable angle to Obayashi’s story that turns on...
There's only one way to know the right time to buy, sell or hold Obayashi. Head to Simply Wall St's company report for the latest analysis of Obayashi's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community place Obayashi between roughly ¥2,946 and ¥3,811, which already shows how far individual estimates can stretch. Those opinions do not yet reflect the buyback, dividend lift or raised profit outlook announced on 13 November 2026, so you may want to consider several updated perspectives.
Explore another Obayashi fair value estimate, including one that suggests as much as 13% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Obayashi research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Obayashi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Obayashi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Obayashi?
Once you are comfortable with your view on Obayashi, it can help to widen the lens and compare it with other businesses that have different strengths, balance sheet profiles and payout habits.
- For investors who want potential mispricing combined with quality fundamentals, scan a curated set of companies using the 19 high quality undervalued stocks.
- If capital preservation and balance sheet strength sit high on your checklist, filter for businesses with robust finances through the list of solid balance sheet and fundamentals (24 results).
- Income focused investors can broaden their watchlist by reviewing companies known for stronger cash distributions via the 28 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com