


EN
Parsons (PSN) Wins A $100 Million Amendment, Is It Still Below Fair Value?
Parsons (PSN) just picked up a fresh contract amendment worth up to US$100 million to continue handling environmental remediation work on the United States west coast, keeping site clean-up services firmly in focus for investors.
Over the past month Parsons has seen a 16.2% share price return, even though the share price return year to date is down 20.1% and the total shareholder return over the past year has declined 39.8%. This points to short term momentum rebuilding after a tougher stretch for longer term holders.
Scan Parsons alongside other contract driven infrastructure and defense plays by running through our hand picked 43 power grid technology and infrastructure stocks in a single view.
Parsons keeps winning complex work and sharpening its federal and infrastructure niche, yet the share price is still digging out from a steep 12 month slide. Does that combination add up to a fair valuation today?
Most Popular Narrative: 16.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Parsons screens as undervalued, with a fair value estimate of $59.64 against the recent $49.72 close. This comparison puts the current contract momentum and guidance reset into a wider earnings story.
The main thing that has to go right is Parsons successfully executing its portfolio mix shift toward higher margin, product and AI driven federal work, while continuing to wind down and exit lower return or higher risk construction and advisory contracts without further large charges.
The current valuation implies the share price reflects concern about guidance cuts and recent one off losses more than the size and duration of Parsons’ backlog, product programs and identified long runway in infrastructure and environmental remediation.
See why 12 investors see Parsons as 17% undervalued.
Result: Fair Value of $59.64 (UNDERVALUED)
Still, the Q2 2026 nonrecurring losses and the cut to 2026 revenue guidance to US$6.2b to US$6.5b leave Parsons exposed if further contract issues emerge.
Find out about the key risks to this Parsons narrative.
Another View: Parsons On Earnings-Based Valuation
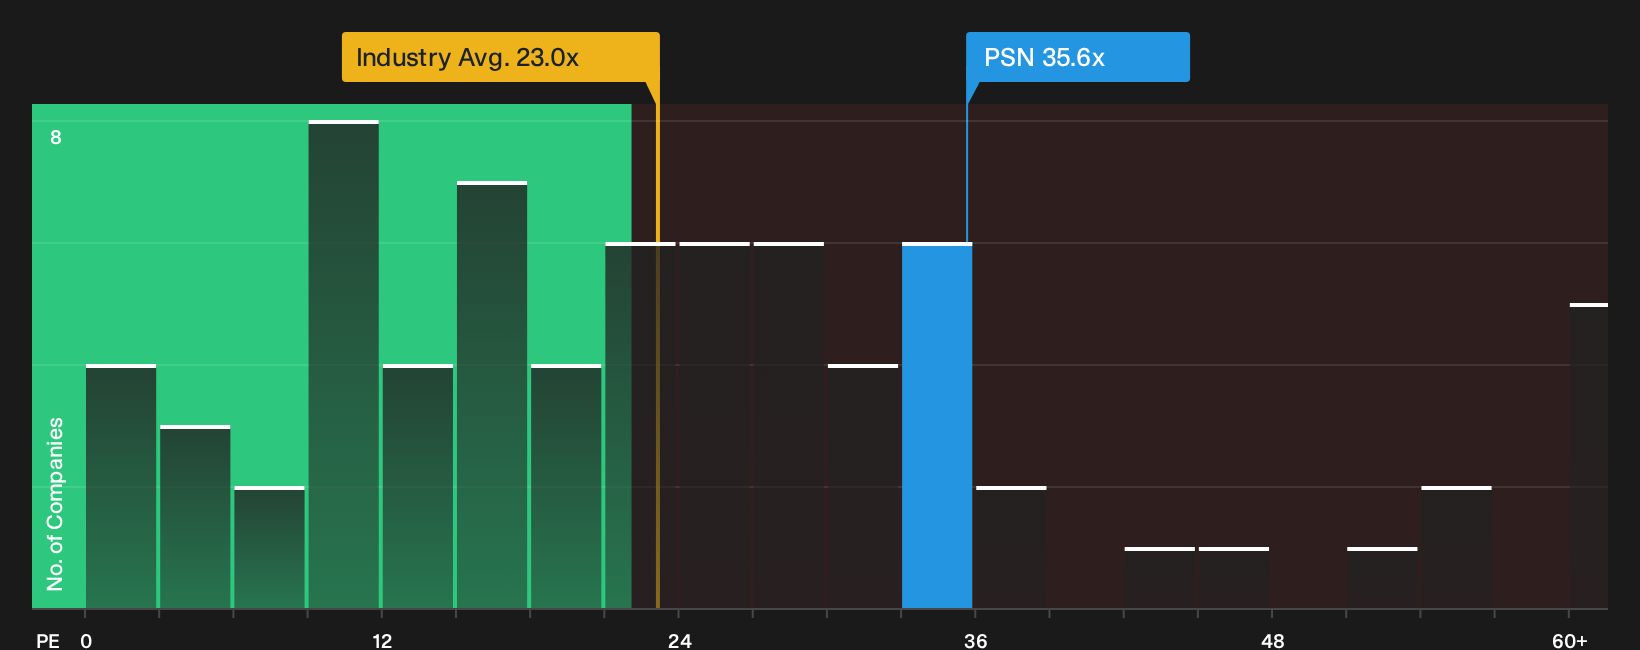
The first take paints Parsons as 16.6% undervalued against a $59.64 fair value. A different lens tells a tighter story. On a P/E of 35.6x, the stock trades above US Professional Services at 22.7x and above its own fair ratio of 30.4x. That gap points to valuation risk if sentiment cools before earnings catch up, so which picture do you trust more today?
For a closer look at how these earnings multiples stack up against cash flow assumptions and scenario work, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Parsons is mixed, with fresh contracts on one side and guidance cuts on the other. Move quickly and test the numbers yourself against your own expectations. To see how those trade offs shake out across both caution flags and potential upsides, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Parsons?
If Parsons has your attention, use this momentum to widen your watchlist and stress test your thesis against other opportunities before the market moves on.
- Target potential upside by scanning a curated pool of quality ideas with the 20 high quality undiscovered gems that many investors may not be watching yet.
- Strengthen your downside protection by filtering for companies on the list of solid balance sheet and fundamentals (24 results) that pair sturdier finances with underlying business fundamentals.
- Lock in income-focused opportunities by reviewing the 6 dividend fortresses that combine higher yields with resilient cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com