


EN
How Job Cuts And Streamlining At Verizon (VZ) Have Changed Its Investment Story
- Verizon Communications has begun a CEO-led overhaul that includes about 13,000 job cuts, fewer management layers, and a push to simplify internal processes, while tying this reset to customer performance and profitability metrics.
- The restructuring highlights a focus on operational efficiency and cost discipline at a time when Verizon is also actively managing its debt profile through note redemptions and tender offers.
- We will look at how this large-cap income story and Schulman’s sweeping restructuring influence Verizon Communications’ long term investment narrative.
Compare Verizon Communications with other potential income and restructuring stories by scanning our hand picked 32 high quality undervalued stocks, which pair balance sheet discipline with cash flow strength.
Verizon Communications Investment Narrative Recap
To stay on as a Verizon Communications shareholder, belief needs to center on steady telecom demand, disciplined capital allocation and an income focus that can absorb heavy network and spectrum spending. According to Silvester, a Simply Wall St Community investor who wrote the Narrative, disciplined leverage and a reliable dividend are key. The short term swing factor is whether execution on fixed wireless and fiber keeps cash generation solid while restructuring removes cost.
The biggest risk right now remains Verizon’s high debt load relative to its funding mix. The latest note tenders and the planned redemption of the US$1.75b 4.125% notes due 2027 look important, yet do not fundamentally change that leverage picture on their own.
The recent tender offers and the scheduled redemption of the 4.125% notes bring the balance sheet into sharper focus for income driven holders. Verizon accepted US$663.976m of longer dated notes and is preparing to retire another US$1.75b in 2027 maturities. That directs attention squarely to refinancing terms, interest expense and future headroom for capex and payouts.
Silvester describes Verizon as relatively low risk with a reasonable return profile, which depends on that mix of recurring telecom cash flow and the composition of the debt stack over time. Progress on retiring or reshaping obligations may support the dividend story that many investors focus on, although execution on earnings and pricing remains central.
Silvester’s narrative sets a fair value for Verizon Communications at US$50.50, anchored to projected revenue growth of 8.1% a year and a future profit margin of 12.5%. Together, these figures frame what that cash generation could justify for an income focused investor.
Uncover how Verizon Communications' fair value indicates a 9% potential upside to its current price before the market closes the discount.
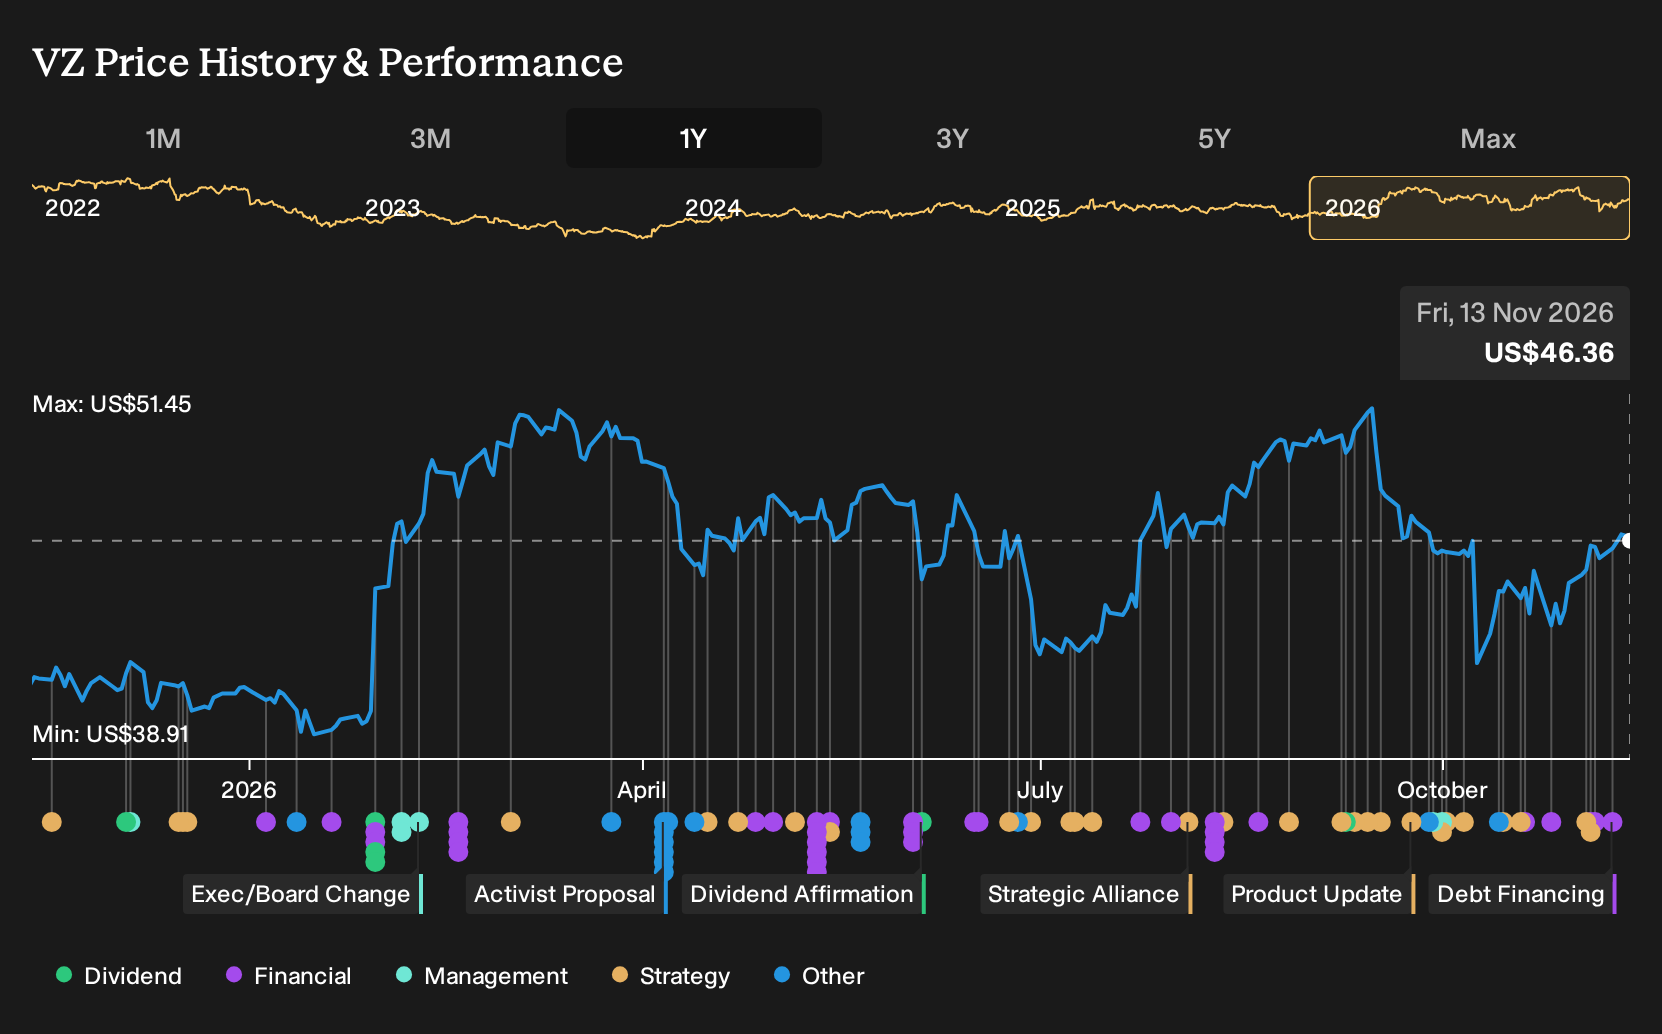
Exploring Other Perspectives
One alternate view on Verizon Communications leans heavily on competitive risk. The most pessimistic analysts worry that new satellite backed mobile entrants could squeeze wireless pricing power. Their pre news models call for revenue of about US$142.7b and earnings of US$21.6b by 2029. That is a more muted path than bulls expect, and this fresh debt activity may eventually push those forecasts in either direction.
Explore 5 other Verizon Communications fair value estimates, including one that suggests it could be worth just $50.50.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own research and judgment.
- A great starting point for your Verizon Communications research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verizon Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verizon Communications' overall financial health at a glance.
Looking Beyond Verizon Communications For Ideas
If you want to stress test your view on Verizon Communications, it often helps to line it up against other income and restructuring stories that share some of the same themes but come with different balance sheets, payout profiles, and risk levels.
- For investors who care most about resilient cash flows and strong finances, scan a list of solid balance sheet and fundamentals (24 results) that keeps the focus on durability rather than excitement.
- If you are hunting for income, review a 6 dividend fortresses that surfaces companies with higher yields and the financial backing that may support those payouts.
- When your priority is tilting toward capital preservation, work through a 31 resilient stocks with low risk scores to see which businesses line up with a more cautious approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com