


EN
Mission Produce (AVO) Could Be 28% Undervalued On Free Cash Flow And Calavo Integration
Analyst commentary around Mission Produce (AVO) has focused on two levers that could matter for shareholders: expected improvements in annual free cash flow and the integration of Calavo, which are now central to the valuation debate.
Recent trading paints a mixed picture for Mission Produce. The share price closed at US$11.83 after a 1-day share price return of 2.51% and a 7-day share price return of 1.46%. However, the 90-day share price return is down 9.42% and the 1-year total shareholder return is down 4.52%. This suggests that short term enthusiasm around free cash flow and the Calavo deal is emerging against a longer backdrop where investors are still reassessing risk and valuation.
Compare Mission Produce's potential free cash flow reset and Calavo integration with other businesses on our curated list of 20 high quality undiscovered gems that the market may not be fully pricing in yet.
Mission Produce trades at US$11.83 while analyst and intrinsic value estimates sit meaningfully higher. Is the recent share price rebound a small blip, or a sign that the discount is starting to close?
Most Popular Narrative: 28% Undervalued
Mission Produce's last close at $11.83 sits well below the $16.50 fair value in the analyst consensus Narrative on Simply Wall St. This applies a 7.24% discount rate to its cash flow outlook and earnings assumptions.
The main factor that has to go right is successful integration of Calavo so that the planned cost synergies and broader prepared foods offering translate into stronger cash generation despite higher debt and integration costs.
See why 6 investors see Mission Produce as 28% undervalued.
Result: Fair Value of $16.50 (UNDERVALUED)
Still, the Mission Produce story can break if weather issues hit Peru or Mexico at the wrong time and if higher debt and cash outflows persist longer than analysts expect.
Find out about the key risks to this Mission Produce narrative.
Another View: Multiples Paint A Tougher Picture For Mission Produce
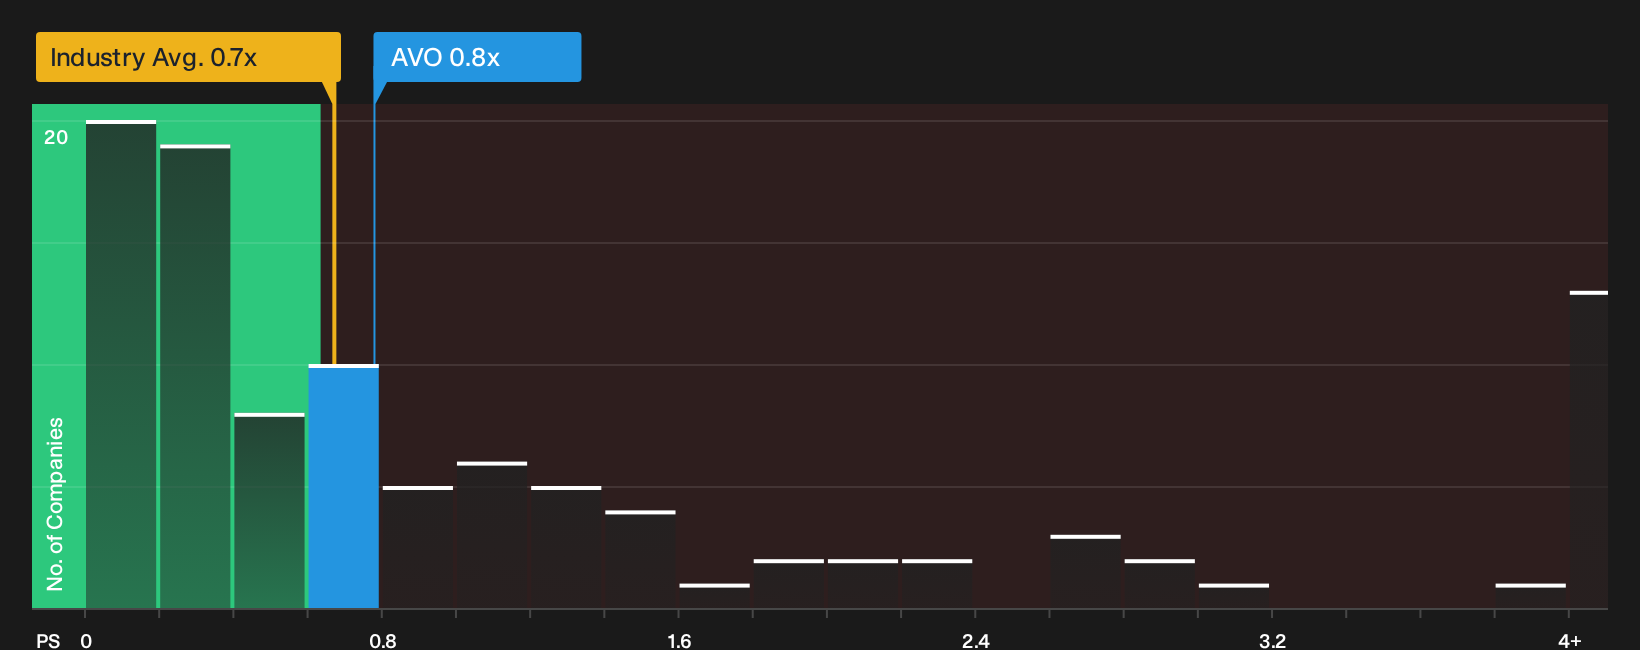
The story looks different once you leave cash flow models aside. On a simple P/S yardstick, Mission Produce trades at 0.8x, which is richer than both its peer group at 0.6x and the US Food industry at 0.7x, and above an estimated fair ratio of 0.7x. That kind of premium can limit upside if the Calavo integration or cash generation disappoints.
For investors weighing these signals against the bullish free cash flow narrative, it raises a practical question. Is the current price rewarding too much optimism for a business with thin margins and mixed recent returns, or is this just the cost of backing a potential turnaround. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals around Mission Produce's value story and risk profile, now is a good time to check the numbers yourself and decide where you stand. To weigh the potential upside against the red flags and see how they balance out, review the 3 key rewards and 5 important warning signs.
Looking for more Mission Produce sized opportunities?
If Mission Produce has you rethinking what the market might be missing, do not stop here. Broadening your watchlist now could shape your next few years.
- Target resilient upside by scanning for steady performers with fewer red flags through a 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing a 32 high quality undervalued stocks that combines solid balance sheets with attractive pricing.
- Stack potential income streams on top of growth ideas by using a 6 dividend fortresses that focuses on higher yielding payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com