


EN
3 UK Recruitment Stocks Facing A Youth Jobs Turning Point
Youth unemployment in the UK is back in the headlines, with around 1 million young people out of work or education and questions over what Alan Milburn’s review and Andy Burnham’s push on jobs might mean next. That mix of political focus and economic strain creates both openings and risks for listed employers and training providers. This article walks through three UK employment and training services stocks exposed to these shifts and why their fortunes could matter for your portfolio.
The three stocks below are just a sample from this theme, and the full screen surfaced 7 more UK employment and training services providers with equally compelling narratives that are not covered here. If you want to identify possible front runners in this space, head straight to the UK employment and training services providers screener to filter and analyze the wider opportunity set.
Michael Page (LSE:PAGE)
Michael Page sits right in the middle of the UK employment and training services theme, because its recruiters live on the front line of matching jobseekers to openings. The analyst consensus Narrative on Simply Wall St highlights why that positioning matters for how the business now makes its money.
Michael Page runs a global recruitment consultancy focused entirely on recruitment services. It generated about £1.6b in revenue, with a mix spanning Page Executive, Michael Page, Page Personnel and Page Outsourcing across professional and support roles. The group, valued at around £653 million, is firmly in mid-cap territory.
"Michael Page is continuing to shift consultants from lower-fee Page Personnel roles into higher-salary Michael Page and Page Executive mandates. This is already reflected in record permanent fee rates and higher gross profit per fee earner in Q3 2026, and can further support revenue quality and net margins as this mix change deepens."
What happens to those improved unit economics if one quiet pressure on recruitment demand moves the needle in either direction?
If that pressure point matters to you, read the full narrative for Michael Page to see how recruitment cycles, consultant mix and capital returns could be decoupling.

Robert Walters (LSE:RWA)
Robert Walters is a pure play on the UK employment and training services theme, helping employers worldwide fill professional roles while governments and businesses look for ways to move more people, including young workers, into sustainable jobs through recruitment, outsourcing and advisory support.
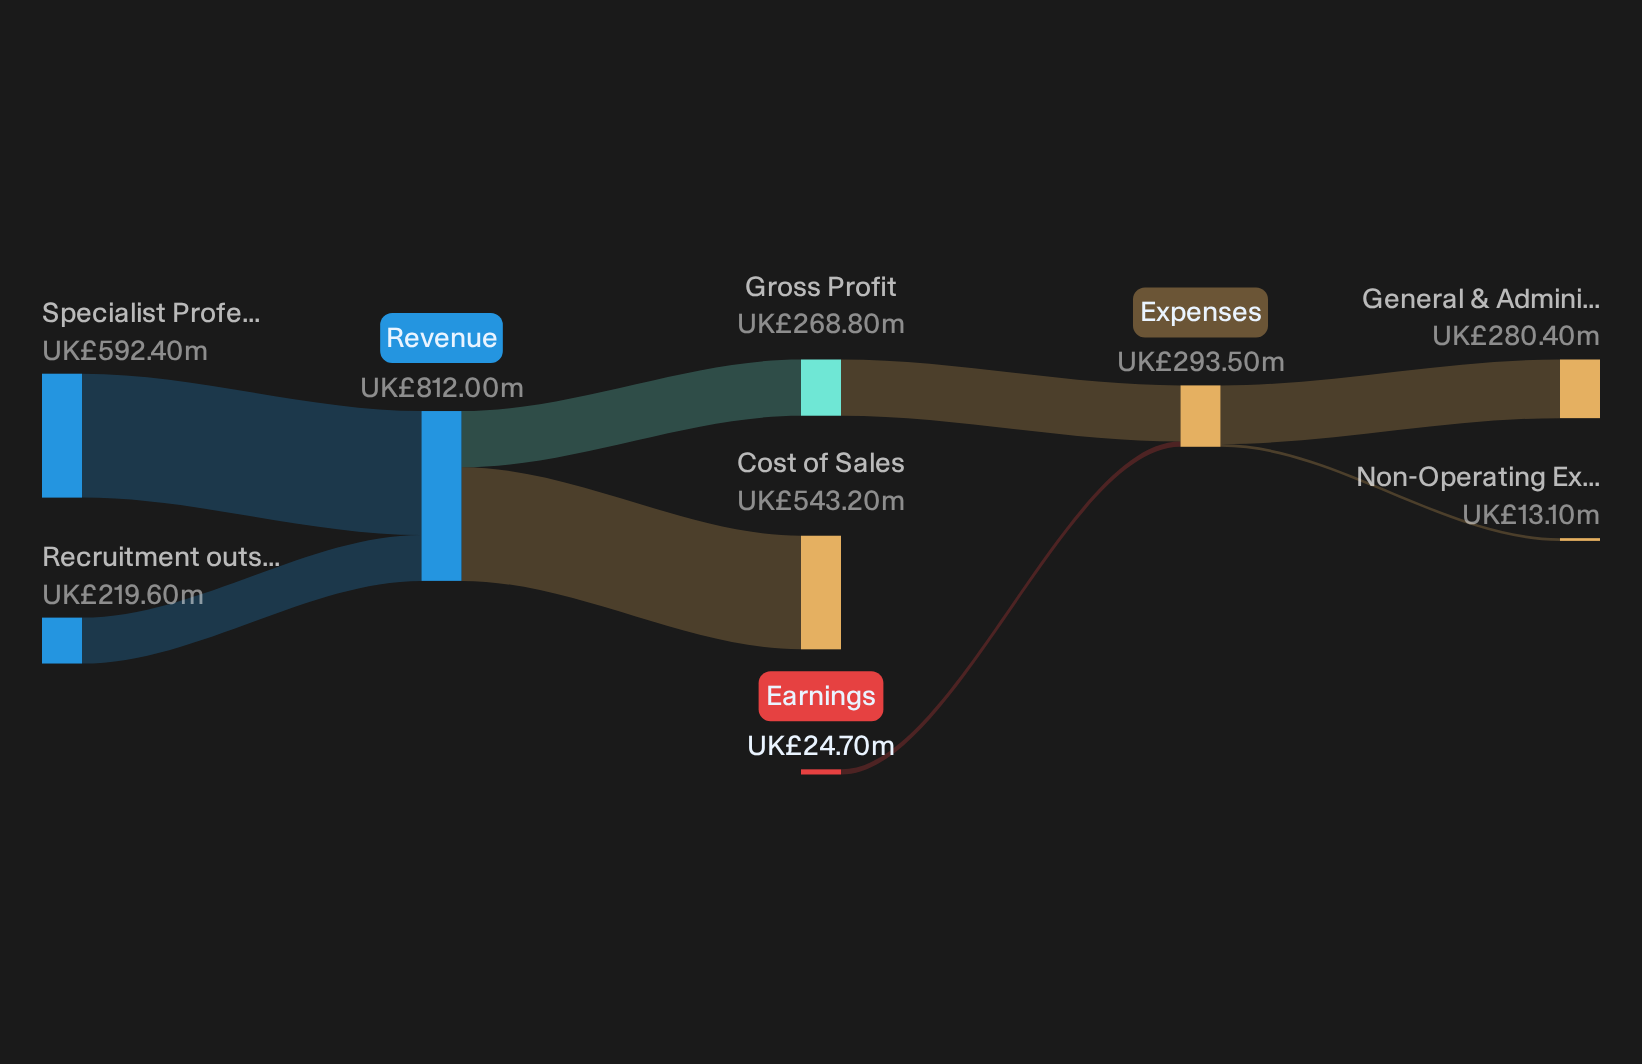
Robert Walters focuses on professional recruitment consultancy and talent services closely tied to employability, generating about £592 million from Specialist Professional Recruitment and £220 million from recruitment outsourcing, with a market value near £89 million.
The bullish analyst Narrative on Simply Wall St argues that what really matters for Robert Walters in this youth employment moment is how its shift toward broader total talent solutions changes the quality and resilience of the income it earns from employers.
"The build out of Robert Walters as a total talent solutions provider, with recruitment outsourcing, consultancy and talent advisory layered on top of its core recruitment franchise, creates scope for a larger mix of multi service contracts that could lift group revenue density per client and support more resilient net margins over time."
What that means for investors depends on how one underappreciated pressure on hiring appetite and contract size ultimately plays out.
That hinge factor is exactly what the full narrative for Robert Walters unpacks, including how Robert Walters could turn multi service contracts into accelerating fee quality and more durable employer relationships.
Hays (LSE:HAS)
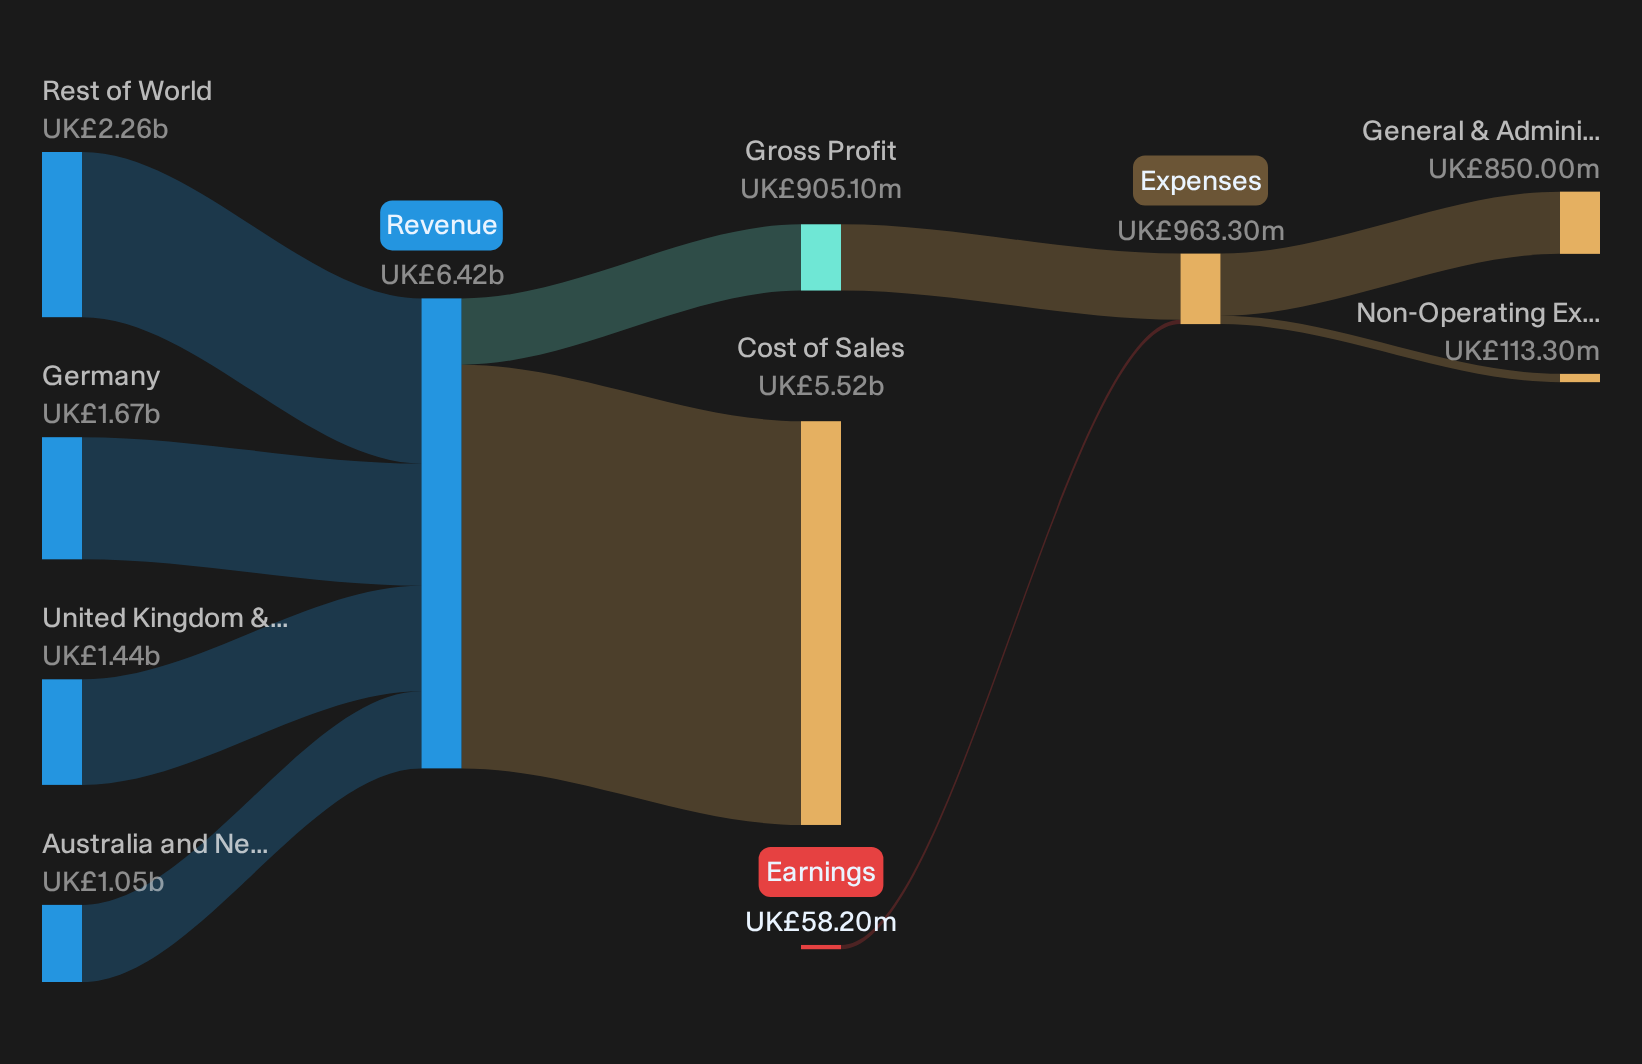
Hays plugs directly into the UK employment and training services theme as a recruiter focused on professional and skilled roles, generating about £6.4b from qualified recruitment and workforce solutions across Germany, the UK and Ireland, Australia and New Zealand and the rest of the world, with a market value near £897 million.
The scale of Hays in professional recruitment means any policy push to get more people into work flows through its desks quickly, and the analyst consensus Narrative on Simply Wall St frames that policy backdrop through the lens of what management is doing to reshape its cost base and earnings power.
"Hays is progressing large structural cost reduction programmes, with £125m per year of savings already delivered since the start of FY'24 and a further £50m per year targeted for FY'27, which management links to a planned improvement in operating profit conversion and future earnings."
What really shifts the dial for Hays now is whether one quiet change in its mix of higher value services and technology driven productivity truly sticks.
If that shift really takes hold, full narrative for Hays shows how Hays’ cost reset, fee mix and tech productivity could turn a routine recruiter into an accelerating earnings story.
Seeking Alternatives Before The Crowd
Fresh themes move fast, and the best breakout stories rarely stay under the radar for long. Momentum shifts, prices move, and ideal entry points can change quickly, so consider acting promptly if an idea fits your strategy.
- Spot potential turnaround stories early by scanning the 15 high quality undervalued stocks while these candidates are still flying under most radars and pricing still reflects yesterday’s expectations.
- Track structural demand by following the 53 AI infrastructure stocks and focus on companies supplying the hardware and infrastructure behind surging AI workloads before momentum is fully reflected in prices.
- Review the 33 elite gold producer stocks to research cash generating miners and identify producers that already have operating projects before renewed interest affects the broader group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com