


EN
How Profit Rebound At Albemarle (ALB) Has Changed Its Investment Story
- Albemarle reported third quarter 2026 sales of US$1,553.1 million, net income of US$296.76 million, and basic earnings per share from continuing operations of US$2.16, with both the quarter and year to date period shifting from losses a year earlier to profits.
- The swing from a net loss of US$160.69 million in the prior year quarter to a profit in the latest period highlights a sharp change in Albemarle's reported operating performance and cost structure, with nine month earnings also moving from a loss to over US$1.0b of net income.
- We will now explore how Albemarle's return to profitability and stronger year to date earnings could reshape the existing investment narrative.
Scan how Albemarle’s profit rebound compares to peers by lining it up against 20 high quality undiscovered gems that also pair strong fundamentals with relatively low market attention.
Albemarle Investment Narrative Recap
To own Albemarle, you need to be comfortable with a lithium producer whose results are tightly linked to commodity pricing and large capital projects. The analyst consensus Narrative on Simply Wall St focuses on cost savings, disciplined spending, and long term contracts to support earnings. The latest quarter shows that profitability can return even in a soft market, which supports the shorter term view that cost cuts are flowing through the income statement.
The biggest near term swing factor is lithium pricing and how long industry oversupply persists. Prolonged weak prices could limit the benefit of Albemarle’s improved cost base and cash generation. A key risk is that aggressive belt tightening and lower CapEx eventually cap volume growth just as demand and pricing reset, leaving the group with healthier margins but less output than it might otherwise have achieved.
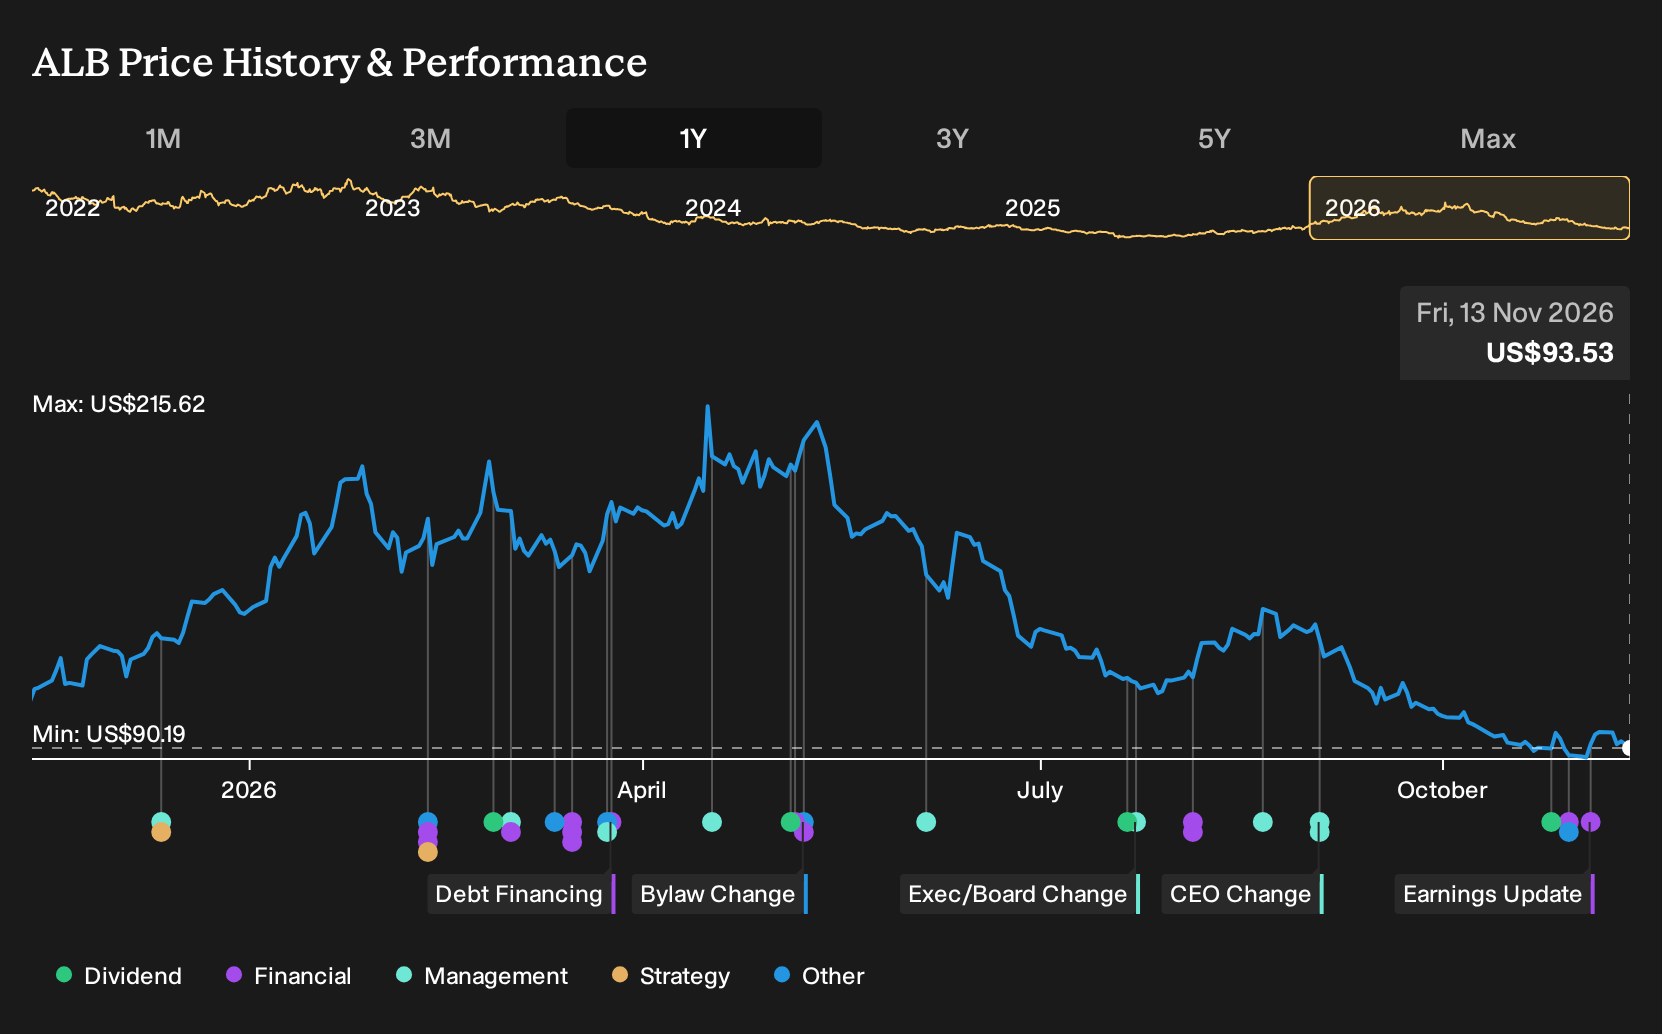
The recent third quarter report is the main operational update. Albemarle reported US$1,553.1 million in quarterly sales and US$296.76 million in net income, with basic EPS from continuing operations of US$2.16. For the first nine months, revenue reached US$4,725.14 million and net profit US$1,095.81 million, with basic EPS of US$8.23. That places the business firmly back into the black after losses a year earlier.
This return to profitability connects directly to the catalysts in the analyst consensus Narrative on Simply Wall St, which highlight cost reduction, contract stability, and capital discipline as supports for future earnings. Investors now have recent evidence in the reported numbers that these themes are influencing actual results, while still needing to weigh them against ongoing risks from lithium oversupply, potential underinvestment, and uncertainty around EV demand.
Albemarle's narrative projects US$6.8b revenue and US$2.5b earnings by 2029. That path assumes 4.8% yearly revenue growth and an earnings increase of roughly US$2.44b from US$57.4m today.
Uncover how Albemarle's fair value indicates a 65% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Albemarle’s volume risk rather than lithium pricing. Bearish analysts noted that a flat to slightly lower Energy Storage outlook around 225,000 to 235,000 tons for 2026 could correspond to revenue drifting down about 6.8% a year toward roughly US$5.0b by 2029. That group viewed earnings of about US$2.2b as already reflected in the share price. The latest profit rebound has not been incorporated into those earlier models, so you can treat this quarter as a reference point and decide which narrative aligns more closely with your own expectations.
Explore 3 other Albemarle fair value estimates, including one that suggests it could be worth just $140.55!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Albemarle research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Albemarle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albemarle's overall financial health at a glance.
Looking for more Albemarle style investment ideas?
If Albemarle has sharpened your sense of what you want from a position, you can use that same checklist to filter the wider market with the Simply Wall St Screener. You can move beyond a single lithium stock and compare other opportunities on income strength, balance sheet resilience, or valuation support in just a few clicks.
- For investors who care most about paying a sensible price for strong fundamentals, you can scan a curated set of potentially mispriced opportunities with the 32 high quality undervalued stocks.
- If capital preservation sits high on your list, you can focus on companies that pair financial resilience with measured risk profiles by running a screen using the 31 resilient stocks with low risk scores.
- When you want to focus on resilient balance sheets and solid underlying finances, you can filter for businesses that pass stricter quality checks using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com