


EN
Is Raised Guidance Altering The Investment Case For Estée Lauder (EL)?
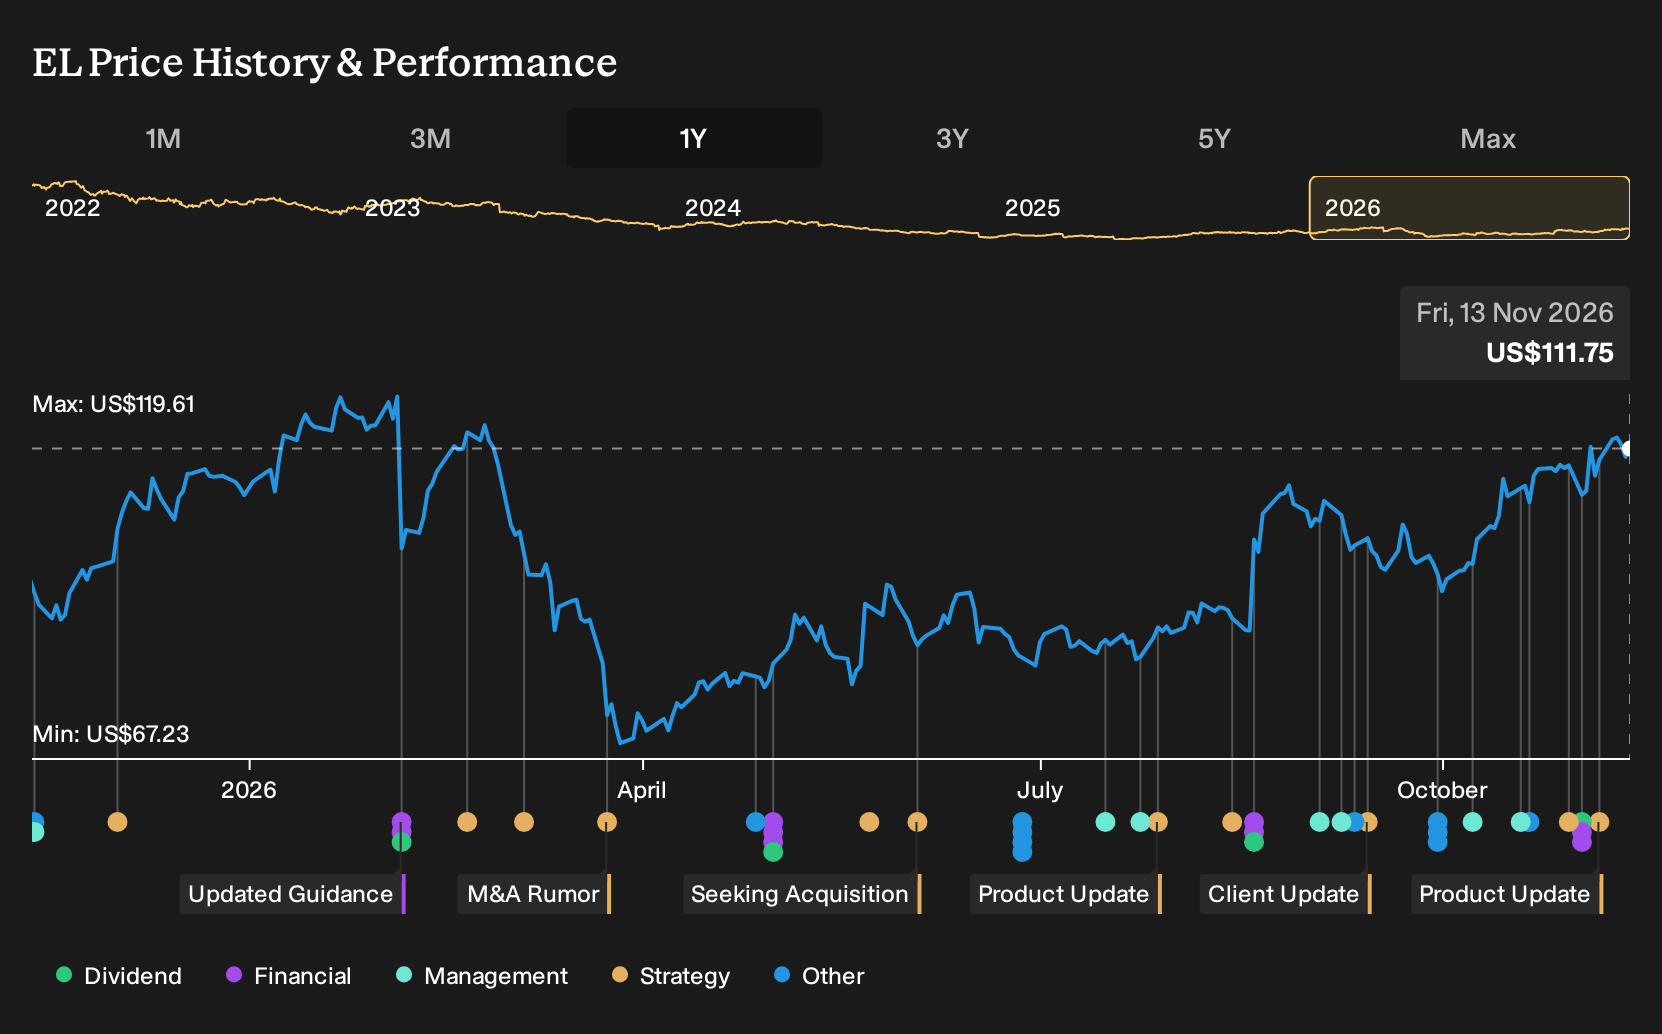
- Estée Lauder Companies reported first quarter fiscal 2027 sales of US$3,715 million and net income of US$233 million. The company then raised full year guidance to 5.0% to 6.5% reported net sales growth and projected diluted EPS of US$2.85 to US$3.18.
- The firm paired this outlook upgrade with a US$0.35 quarterly dividend declaration and highlighted its Mastering Skin Longevity platform as a shared science engine for future product development across key brands.
- We will look at how Estée Lauder Companies' upgraded fiscal 2027 sales and earnings guidance reshapes its Profit Recovery and Growth Plan narrative.
Scan beyond Estée Lauder Companies and compare its recovery story with curated peers using the 20 high quality undiscovered gems that may be quietly building equally robust foundations.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies, you need to believe the Profit Recovery and Growth Plan plus the One ELC model can keep translating restructuring into healthier margins without dulling brand appeal. The raised fiscal 2027 sales and EPS guidance points to progress, but the analyst consensus Narrative on Simply Wall St still flags execution as the key hinge.
The most important near term swing factor remains revenue consistency across travel retail and online channels. The biggest risk is that heavy workforce and door reductions or any governance overhang from the external investigation undermine on the ground execution just as Estée Lauder Companies leans harder into higher margin growth.
The Mastering Skin Longevity platform announcement sits right in the middle of that story. It concentrates decades of Estée Lauder Companies research in areas like sirtuin biology, epigenetics and cellular repair into a common R&D engine that multiple brands can pull from, which ties directly into product cycle strength and pricing power.
If this science hub leads to a steadier stream of differentiated serums, creams and treatments across Estée Lauder, La Mer, Clinique, Lab Series and The Ordinary, it could support the recovery plan by improving mix and supporting gross margin. The flip side is execution risk if complex new technologies raise development cost or fail to resonate in key channels such as travel retail and online where the catalysts are most sensitive.
Estée Lauder Companies' narrative projects US$17.4b revenue and US$1.6b earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about US$1.2b from US$368.0m today.
Uncover why Estée Lauder Companies' fair value aligns with its current price.
Exploring Other Perspectives
Some of the lowest Estée Lauder Companies forecasts put more weight on cash flow pressure than on the Mastering Skin Longevity catalyst you just read about. Those analysts were pencilling in around US$17.0b in revenue and US$1.5b in earnings by 2029 and a P/E of 27.3x. That is a more cautious story than the consensus, which assumes US$17.4b of sales and US$1.6b of earnings. Use that spread as your prompt to explore several narratives, then decide which feels closest to how you think this new guidance and science platform could reshape the outlook.
Explore 5 other Estée Lauder Companies fair value estimates, including one that suggests as much as 21% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking for more Estée Lauder Companies sized investment ideas?
Once you have a view on Estée Lauder Companies, it can help to set it alongside other businesses with different balance sheets, risk profiles and income characteristics using the Simply Wall St Screener.
- If capital preservation sits high on your list, scan resilient candidates with lower risk scores through the 31 resilient stocks with low risk scores and see how they compare with your current watchlist.
- If dependable income matters more to you, weigh Estée Lauder Companies against companies offering strong yield profiles by reviewing the 6 dividend fortresses that combine payouts with underlying business strength.
- If you want to uncover less crowded ideas, widen your search beyond headline tickers and hunt through the 20 high quality undiscovered gems that pair solid fundamentals with quieter investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com