


EN
How Analyst Upgrades At Eagle Bancorp Stock Have Changed Its Investment Story
- Eagle Bancorp is drawing fresh attention as analysts highlight a cleaner office loan book, stronger earnings estimates and improving balance sheet flexibility.
- The more compelling angle is the shift toward C&I lending and core relationship deposits, which could reshape Eagle Bancorp’s earnings mix and funding profile.
- The next area of focus will be how this improving earnings outlook could reshape Eagle Bancorp’s investment narrative and risk reward profile.
Eagle Bancorp Investment Narrative Recap
For an investor to back Eagle Bancorp today, the core belief is that the heavy lifting on office and broader credit cleanup is largely reflected in the current numbers and that the refocus on C&I and relationship deposits can support more stable earnings. The analyst consensus Narrative on Simply Wall St leans on that shift, together with high capital and liquidity, as the operational backbone of the story.
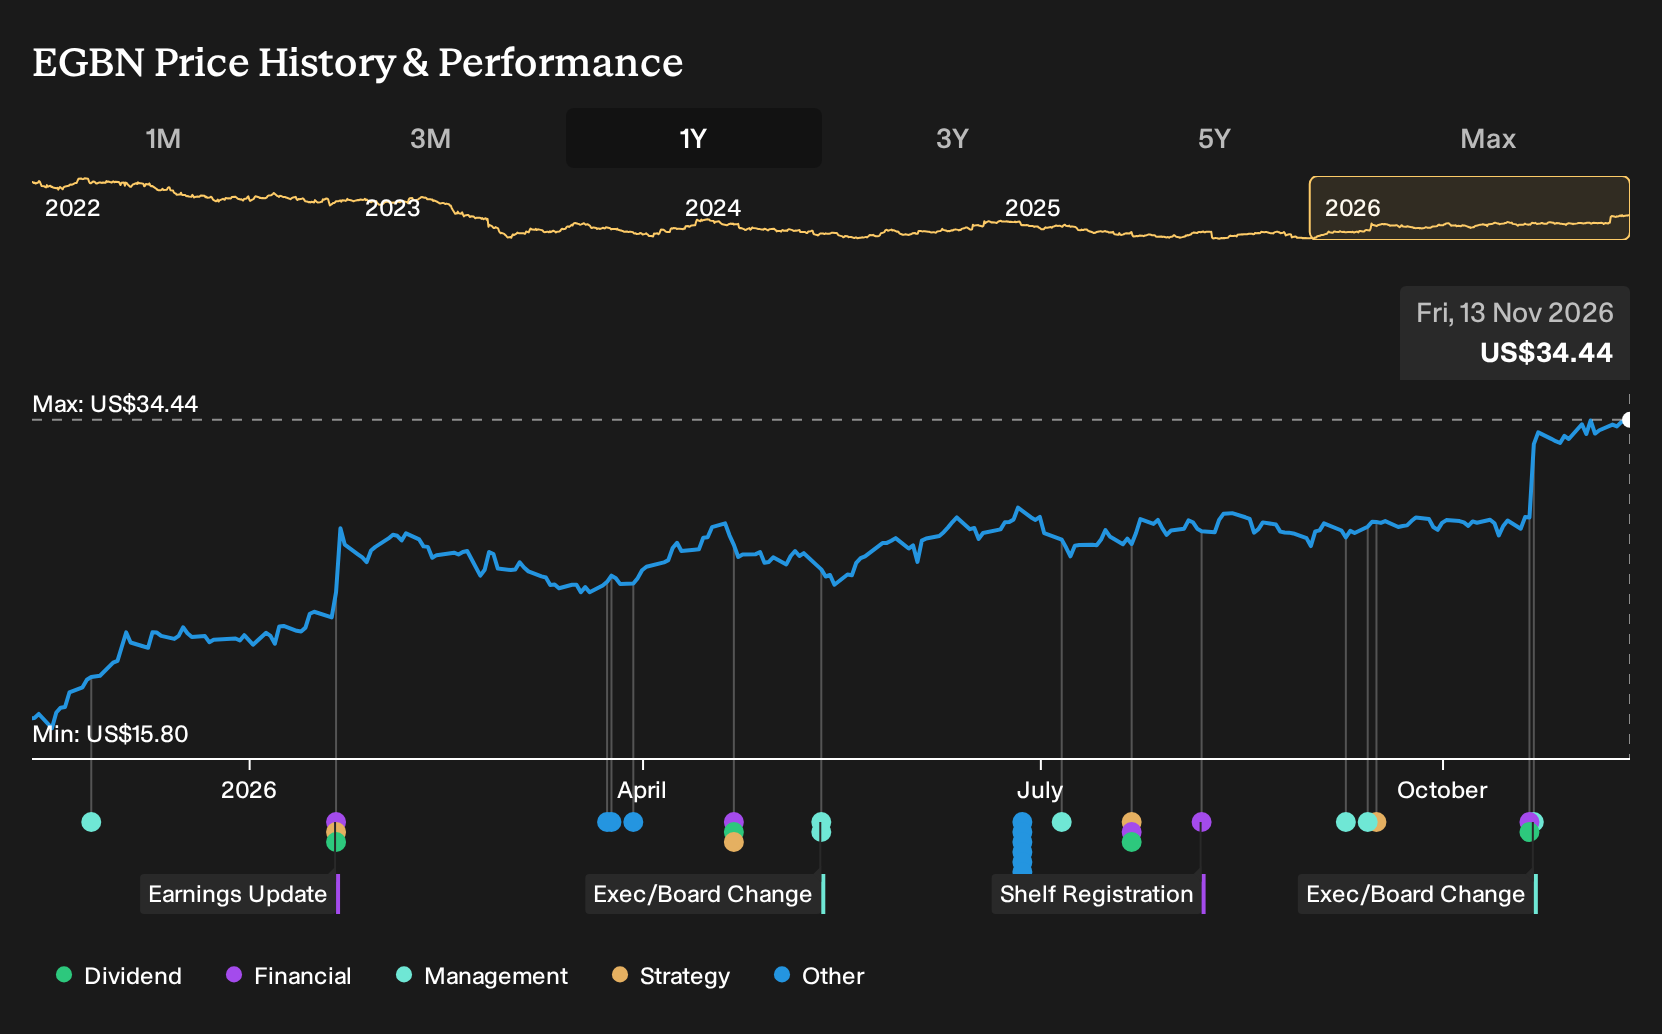
The sharp 1 year share price gain and premium P/E multiple versus US banks mean the short term catalyst is continued evidence that credit costs and funding pressures stay contained while earnings stabilize from this higher base. The biggest near term risk remains further stress in commercial real estate or multifamily that pushes bad loans and provisions above expectations.
The most relevant recent development is the upward revision to earnings estimates that resulted in Eagle Bancorp receiving a Zacks Rank #2 rating and a Momentum Style Score of B. Consensus forecasts now assume earnings growth of about 31% per year over the next three years, with revenue projected to rise roughly 7% annually.
That upgrade aligns with the catalysts in the analyst consensus Narrative on Simply Wall St, which focuses on office credit cleanup, C&I growth and an improved deposit mix to support those forecasted earnings. It also highlights the trade off investors need to weigh. A higher earnings outlook and strong 1 year return are set against valuation signals such as the excess returns model indicating the stock trades above estimated intrinsic value and a P/E that screens as expensive relative to peers.
Eagle Bancorp's narrative projects US$305.7 million revenue and US$119.8 million earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about US$76.4 million from current earnings of US$43.4 million.
Uncover why Eagle Bancorp's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish twist on Eagle Bancorp focuses on those higher non performing assets. The most cautious analysts were penciling in roughly US$302.2 million of revenue and about US$113.1 million of earnings by 2029, which is meaningfully lower than the upbeat cases. Your takeaway is simple. Opinions differ a lot, and this fresh news could push both stories to change.
Explore 2 other Eagle Bancorp fair value estimates, including one that suggests up to 12% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eagle Bancorp research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Eagle Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eagle Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eagle Bancorp?
If the Eagle Bancorp story has sharpened your focus on balance sheet strength, income potential and valuation, the next step is to widen your opportunity set using the Simply Wall St Screener. You can filter for the kind of financial traits you care about, then build a watchlist that genuinely reflects your own risk and return preferences.
- If capital preservation and smoother earnings matter to you, start with companies that screen well for resilience using our 31 resilient stocks with low risk scores.
- For investors who want stronger fundamentals without overpaying, there is a curated 32 high quality undervalued stocks that may align with your preferred margin of safety.
- Those looking to broaden their watchlist with less followed opportunities can review a focused 20 high quality undiscovered gems that meet tighter quality filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com