


EN
Upbound Group (UPBD) Settles 43 State Acima Probe With $183.5 Million Customer Relief
- Upbound Group (NasdaqGS:UPBD) subsidiary Acima reached a multistate settlement with attorneys general from 43 states over its rental purchase practices.
- The agreement resolves a multiyear investigation into Acima's leasing conduct and includes financial restitution and lease forgiveness for affected customers.
- Acima settled the case without an admission of wrongdoing, addressing legal questions around its business model while allowing operations to continue.
- The Acima multistate settlement closes a major legal chapter, although the broader investment story for Upbound Group involves more than this outcome. Check out 4 other big wins that Upbound Group investors should know about.
For investors tracking consumer finance and leasing companies, it can be useful to compare this situation with peers through 6 dividend fortresses.
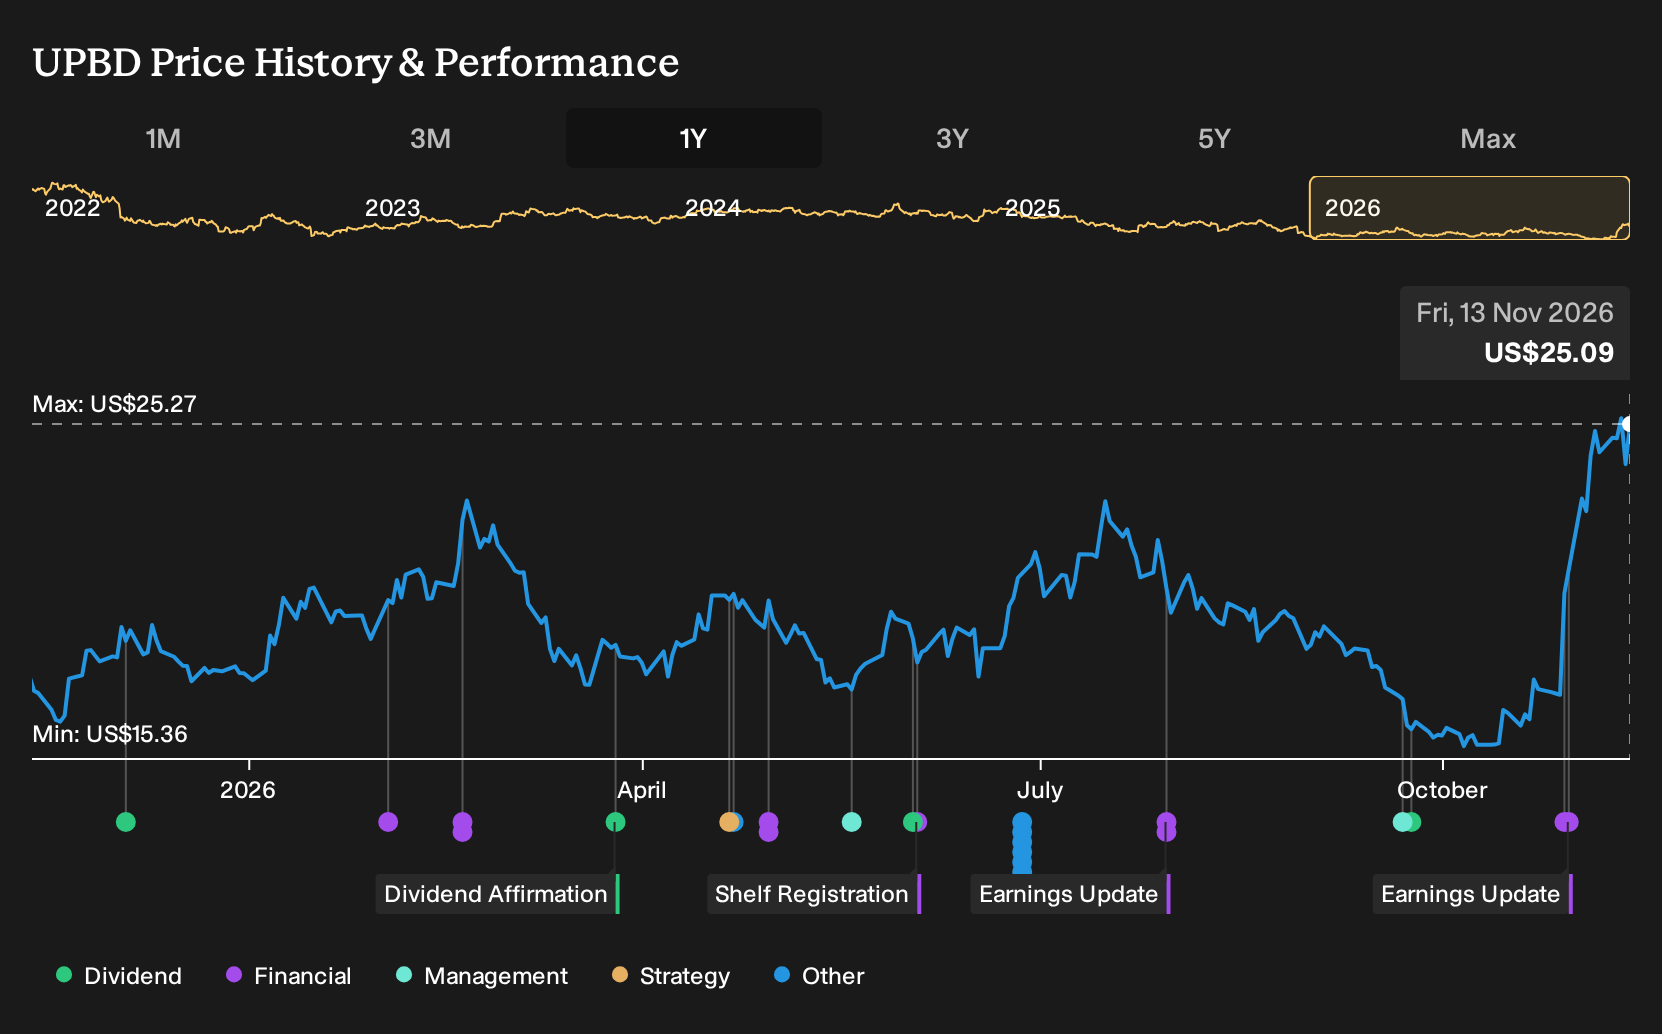
Upbound Group operates as a US based specialty retail and financial solutions provider, using technology and data to offer leasing style options to customers in the United States, Puerto Rico, and Mexico. As a result, regulatory clarity around Acima directly affects how this wider platform can be used.
See how Upbound Group's balance sheet measures up.
How the Acima settlement tilts the Upbound Group narrative
The central bet with Upbound Group is that Acima and Rent-A-Center can keep producing steady cash from non-prime customers while Brigit grows, even as regulators test how far the model can stretch. This settlement directly touches the Acima part of that story.
"The main thing that has to go right is that Brigit continues to scale paying users and new products while Acima and Rent-A-Center sustain disciplined credit performance and cash generation in a pressured non-prime consumer market…"
See how the full story points towards a $28.25 fair value for Upbound Group.
The multistate deal gives investors a defined cost for a 2021 investigation, which lines up with the bull view that regulatory risk can be contained while Acima continues to operate. It also fits the Narrative’s emphasis on disciplined credit, since settling without admitting wrongdoing reduces one layer of uncertainty around past leasing practices rather than current underwriting.
The bear side does not disappear, though. A US$53.5 million payment plus US$130 million of lease forgiveness reinforces that legal and conduct issues can absorb real cash, which analysts already flag as a risk for earnings and free cash flow. For a model built on non-prime customers, that kind of scrutiny can feel structural rather than one-off, especially when rivals like Affirm or Klarna face their own regulatory questions.
News like this only becomes useful once it is plugged into a clear Upbound Group narrative that connects regulatory outcomes to the durability of cash generation and risk.
Add Upbound Group to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com