


EN
Intapp (INTA) Q4 Strength Puts Valuation In Focus As Cloud Growth Builds
Intapp (INTA) moved after reporting a strong fiscal fourth quarter, with cloud annual recurring revenue up 29% and subscription revenue up 27%, along with record cloud migrations and guidance for fiscal 2027 above consensus.
Recent trading suggests momentum is building for Intapp, with a 30 day share price return of 16.71% and a 90 day gain of 15.08%, while the 1 year total shareholder return of 7.17% indicates more measured longer term progress.
Scan beyond Intapp and see which other software players are showing similar momentum and fundamentals in our hand picked 20 high quality undiscovered gems list.
Intapp clearly has a strong cloud and subscription engine, and the recent share price jump reflects that optimism. The harder question is whether the current valuation already incorporates most of that strength.
Most Popular Narrative: 7% Overvalued
Intapp closed at $46.16, while the analyst consensus Narrative on Simply Wall St pegs fair value at $43.00, so the stock screens as slightly expensive based on those long range assumptions and a discount rate of 8.4%.
The shift of professional firms from desk level AI to governed Firm AI, with Celeste contributing more than 40% of net new bookings, combined with ongoing on premises to cloud migrations and a subscription mix nearing 80% of revenue and a 25% free cash flow margin, provides a path for Intapp to grow recurring revenue and sustain higher net margins.
See why 16 investors see Intapp as 7% overvalued.
Result: Fair Value of $43 (OVERVALUED)
Still, the Intapp narrative can be knocked off course if partner delivery capacity limits Celeste rollouts, or if cloud subscriptions fail to offset weaker on premises license revenue.
Find out about the key risks to this Intapp narrative.
Another View: Intapp Through The Cash Flow Lens
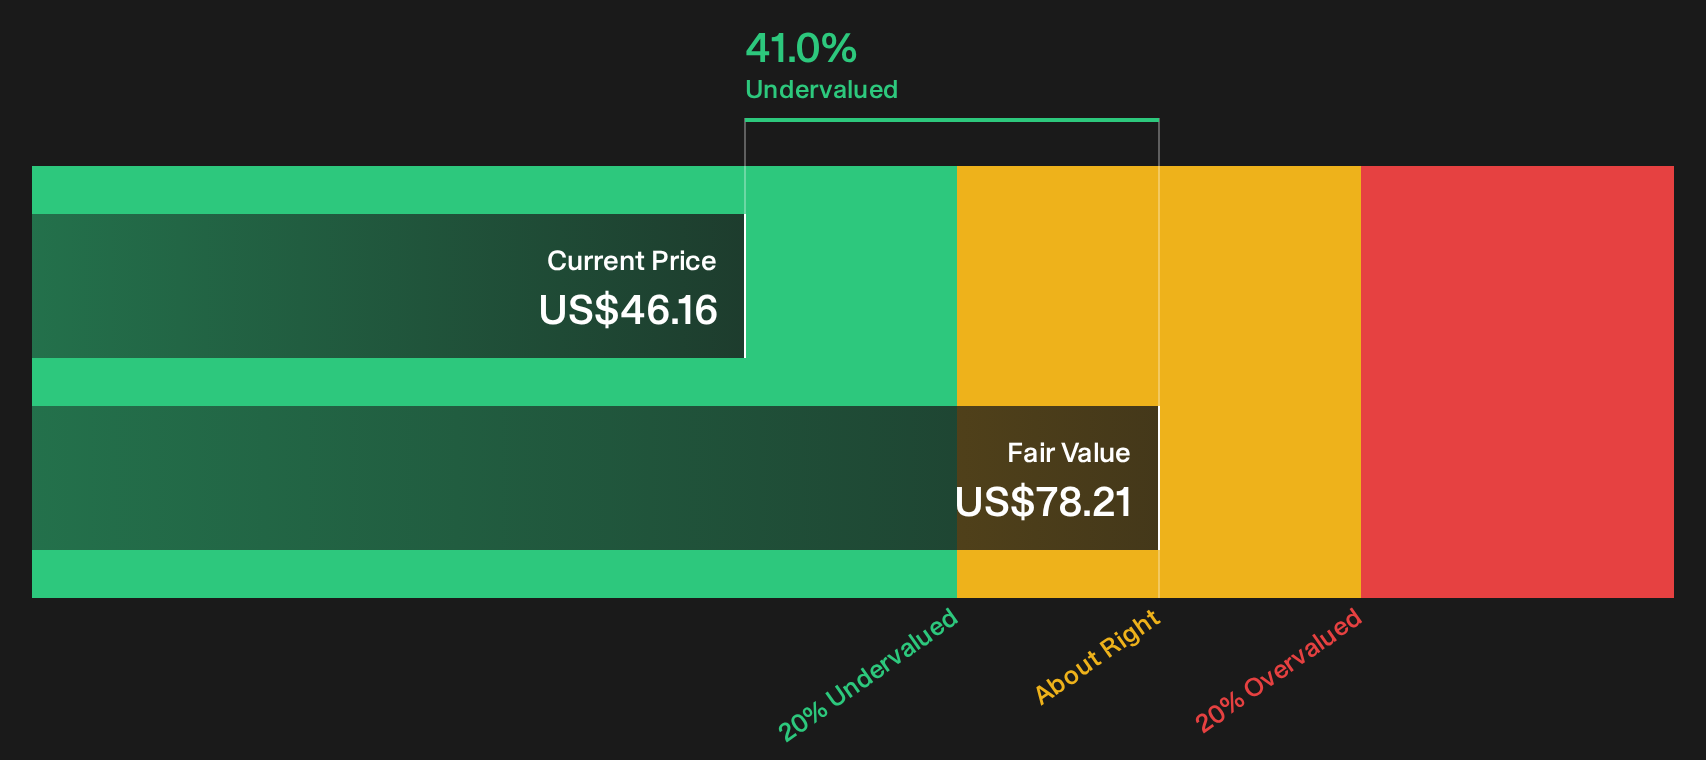
The analyst narrative on Intapp flags the shares as about 7% overvalued at $46.16 versus a $43.00 fair value. The SWS DCF model points in the opposite direction. It suggests the stock trades around 41% below an estimated future cash flow value of $78.21, which frames the current price as discounted rather than stretched. That split raises a simple question: Which set of assumptions do you trust more, the earnings based target or the cash flow path baked into the DCF model?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Intapp is mixed in the data, so it makes sense to move quickly and weigh the upside case for yourself. To see what optimism is already priced in, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Intapp?
Do not stop your research with Intapp. Use the Simply Wall St Screener to hunt for fresh opportunities before other investors start paying attention.
- Target resilience by checking companies with strong capital structures and fundamentals through our list of solid balance sheet and fundamentals (24 results).
- Focus on value by reviewing companies that combine quality fundamentals with potentially attractive pricing in the 32 high quality undervalued stocks.
- Prioritise stability by scanning companies with steadier profiles and lower risk scores using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com