


EN
Is Talen Energy (TLN) Undervalued Following Its Long Term Capacity Sales Deals?
Capacity deals push Talen Energy toward more predictable earnings
Talen Energy (TLN) has kicked off a multi year reset of its cash flow profile, signing long dated capacity agreements that lock in revenue from key PJM power plants.
The centerpiece is a seven year sale of 750 megawatts of accredited capacity from the Guernsey Power Station to an investment grade buyer, expected to generate about US$100 million a year from 2029/2030 through 2035/2036.
Layered on top of earlier PJM auction clears, these commitments give Talen Energy roughly ten years and around US$1b of cumulative capacity revenue visibility tied to this slice of its fleet.
Management now has more than one third of its ELCC accredited capacity under long term contract, which lifts the contracted share of gross margin to 40% through 2036 and reduces earnings volatility.
The Guernsey deal is not the only piece in play. Talen Energy has also lined up separate agreements for the remaining 588 megawatts of Guernsey capacity in the 2029/2030 PJM delivery year and 702 megawatts from the Waterford Energy Center for three years through 2031/2032.
Those additional commitments push total contracted capacity from this transaction set to more than two gigawatts in the 2029/2030 planning year and 1.45 gigawatts in each of 2030/2031 and 2031/2032.
Talen Energy’s latest capacity deals come after a strong run in the shares, with a 7 day share price return of 11.04% and a 3 year total shareholder return of almost 7x. This is despite the year to date share price return being down 5.22% and the 1 day move slipping 2.76% to US$376.01 as investors digest earnings guidance, recent quarterly results and this new push toward more contracted cash flows.
Pursue other contracted cash flow stories like Talen Energy by scanning our hand picked 31 resilient stocks with low risk scores across the utilities and infrastructure space.Talen Energy now trades at a steep discount to both analyst targets and intrinsic estimates, even after the recent surge. This raises a simple tension: Is the market prudently fading contract risk or overpricing caution?
Most Popular Narrative: 4.8% Undervalued
Talen Energy closed at $376.01, while the leading valuation narrative pegs fair value at $395, suggesting a small undervaluation gap that depends heavily on future cash generation. According to Andrei_Niculescu, a Simply Wall St Community investor who wrote the narrative, the key question is whether current guidance on free cash flow holds up against leverage and PJM market risk.
That is attractive, if you underwrite the 2027 Adj FCF midpoint and apply a mid-to-high single-digit FCF yield after leverage. It is not attractive if you capitalize peak GAAP quarters or ignore that part of next year's capacity cash has already been sold forward.
See why 4 investors see Talen Energy as 5% undervalued.
Result: Fair Value of $395 (UNDERVALUED)
Still, two pressure points could upset the Talen Energy story: a cut to the 2027 free cash flow guidance and any harsh redesign of PJM capacity rules.
Find out about the key risks to this Talen Energy narrative.
Another view on Talen Energy’s valuation
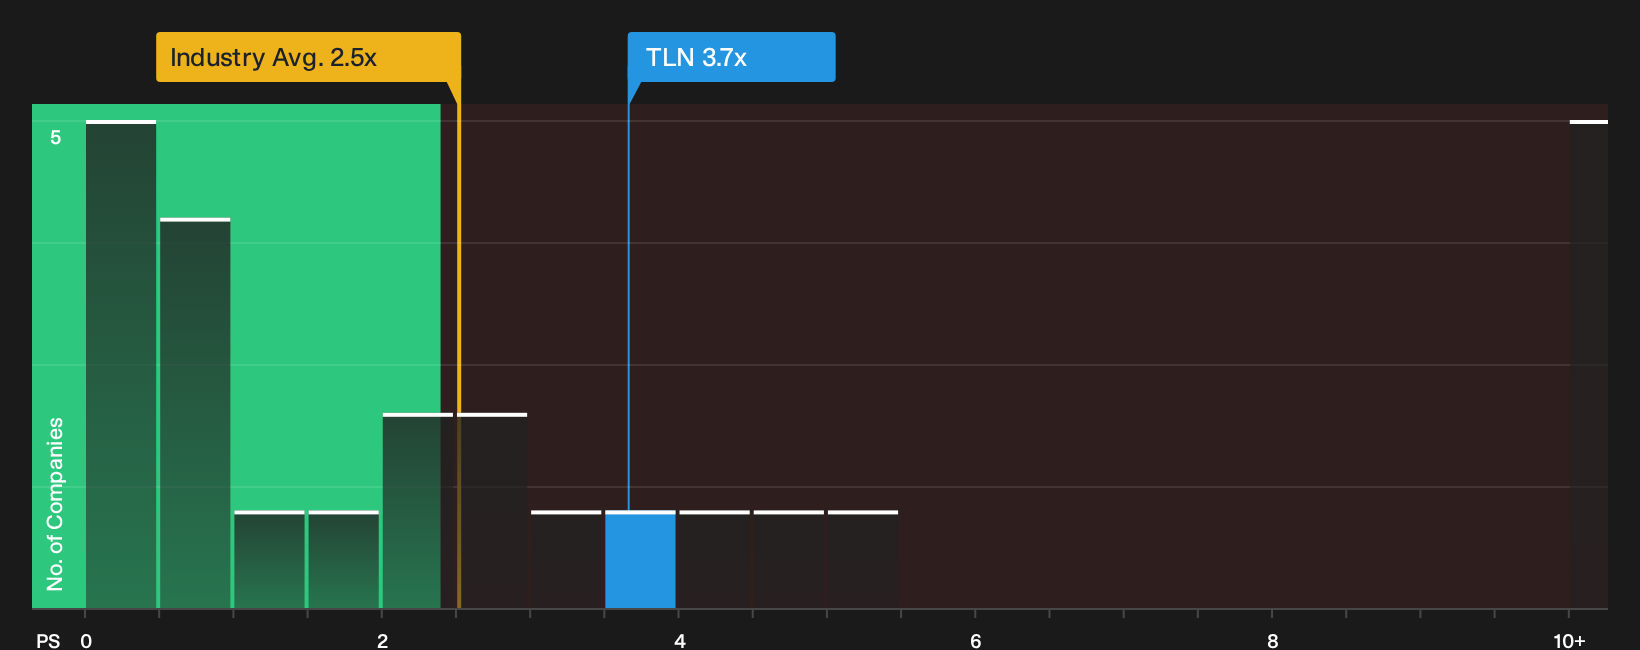
The DCF story is one thing. On simple sales-based pricing, Talen Energy looks expensive, trading on a P/S of 3.7x against 2.5x for the wider North American renewable group and 1.7x for peers, even though the fair ratio model points to 4.2x as a level the market could move toward.
That gap cuts both ways. Richer multiples than the sector and closer alignment with the fair ratio can signal investors are already paying up for the contract-heavy earnings profile, or that the stock is still catching up to its own cash flow math. Which reading fits your risk appetite?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of new contracts and valuation debates around Talen Energy feels finely balanced, that is the point. It is why you should review both the upside case and the caution flags for yourself through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Talen Energy?
You have seen how contract-backed cash flows shape the Talen Energy story. Now give yourself options by lining up a few more ideas side by side.
- Target resilient potential by scanning a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without constant balance sheet stress.
- Hunt for mispriced opportunities through a focused 32 high quality undervalued stocks that highlights shares where fundamentals and expectations look out of sync.
- Build a watchlist of potential income workhorses with a 6 dividend fortresses that screens for higher yields supported by underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com