


EN
How Strong Earnings Guidance At Nova (NVMI) Has Changed Its Investment Story
- Nova reported third quarter 2026 revenue of US$287.84 million and net income of US$89.96 million, with diluted EPS from continuing operations of US$2.64. The company also issued fourth quarter guidance for US$305 million to US$315 million in revenue and diluted GAAP EPS of US$2.78 to US$2.93.
- Results for the first nine months of 2026 showed revenue of US$778.11 million and net income of US$234.23 million, indicating that Nova's process control tools are seeing demand across customers that value tighter metrology in complex chip production flows.
- We will now look at how Nova's investment narrative relates to this new revenue outlook, particularly the fourth quarter guidance range.
Nova Investment Narrative Recap
To own Nova, you need to be comfortable with a metrology specialist that is tightly linked to wafer fab spending and node complexity. The analyst consensus Narrative on Simply Wall St leans on higher metrology intensity as chip designs get harder to manufacture. The latest quarter and Q4 revenue and EPS guidance suggest the near term demand picture is stable enough to keep that operational thesis intact.
The nearer catalyst is whether Nova can keep converting its expanded tool portfolio into steady orders across logic, foundry and memory customers while mix headwinds in DRAM and NAND persist. The key risk remains exposure to China and rising local competitors, which could pressure pricing and margins if tool selections shift away.
The fresh Q4 outlook of US$305 million to US$315 million in revenue and diluted GAAP EPS of US$2.78 to US$2.93 is the cleanest announcement to focus on here. It gives you a direct read on how management sees tool demand trending into year end, after reporting nine month revenue of US$778.11 million and net income of US$234.23 million.
This guidance sits against earlier expectations in the analyst consensus Narrative on Simply Wall St that depend on Nova scaling manufacturing capacity and broadening materials metrology adoption. Execution against the Q4 range will help investors judge how well the firm is handling product mix issues and China competition, both of which sit at the center of the current risk reward trade off.
Analysts are effectively sketching a long runway for Nova, with revenue projections of US$1.8b and earnings of US$599.4 million by 2029. These figures are built on the assumption of 22.3% yearly top line expansion and an earnings increase of about US$300 million from current earnings of US$298.9 million.
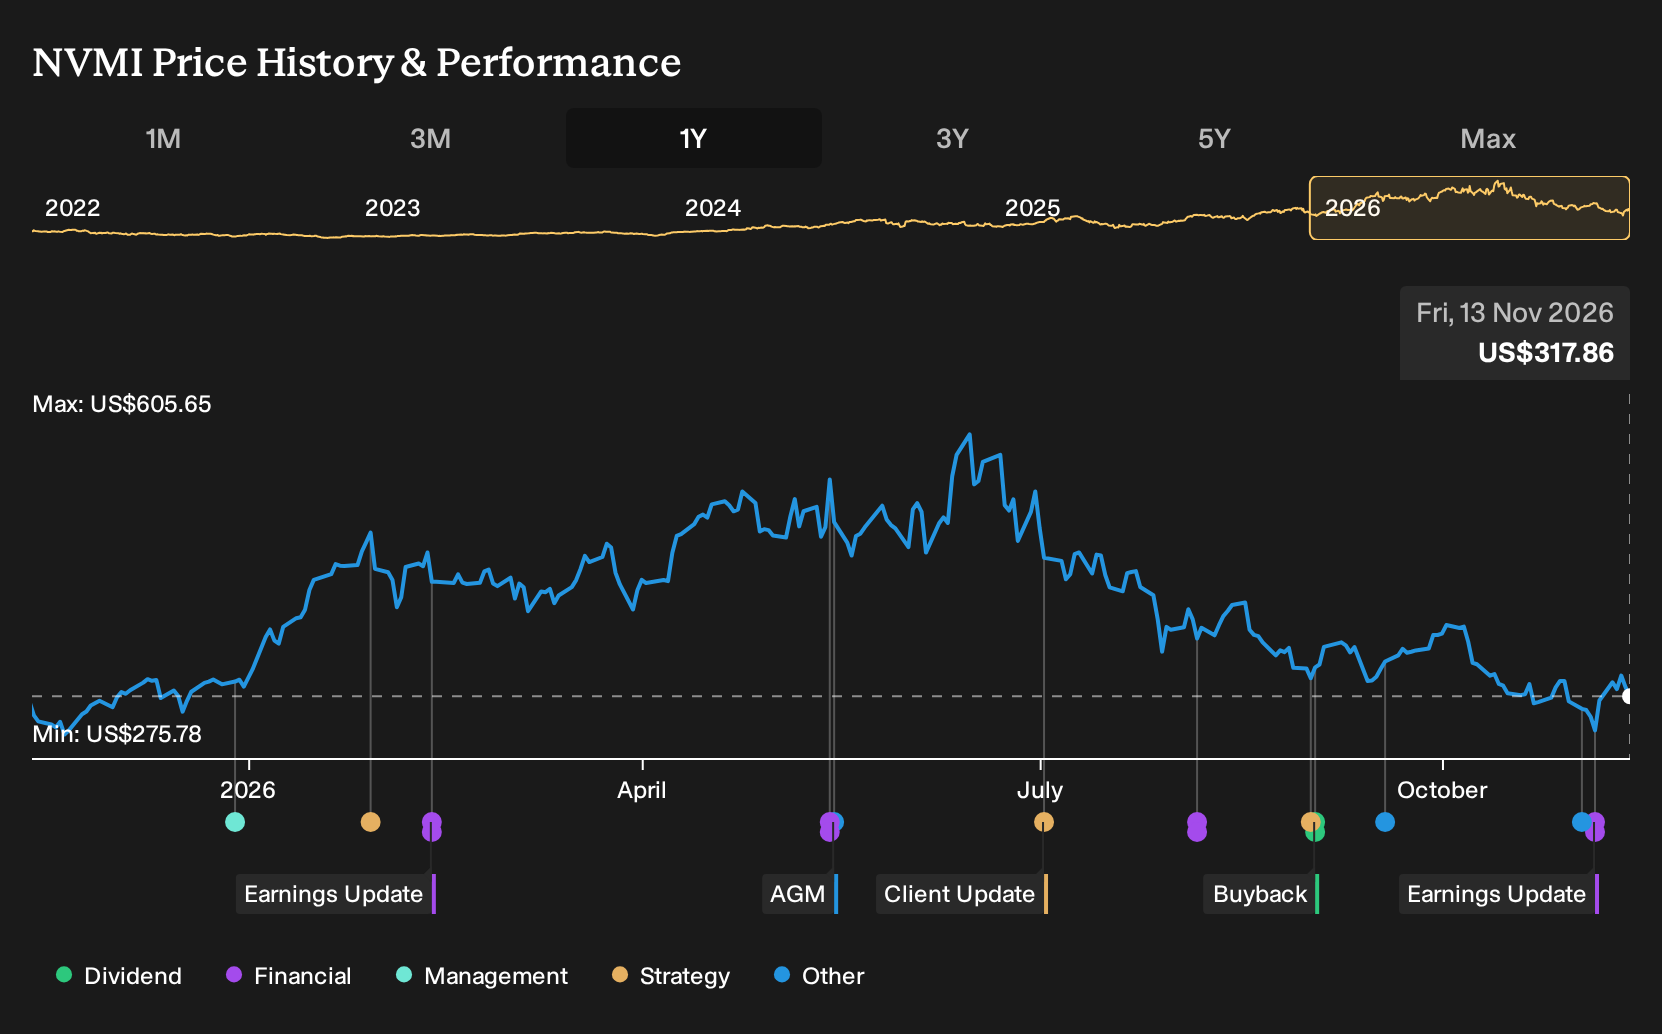
Uncover why Nova's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view fixates on mix risk. The lowest analysts expected Nova’s revenue to reach about US$1.8b and earnings of roughly US$602.3 million by 2029, but only on a lower 30.7x P/E. This presents a more cautious story that this fresh Q4 guidance could still reshape.
Explore 3 other Nova fair value estimates, including one that suggests as much as 58% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A useful starting point for your Nova research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which helps you evaluate Nova's overall financial health at a glance.
Looking for more Nova investment ideas beyond a single stock?
If you want to stress test your view on Nova against other opportunities, use the Simply Wall St Screener to line up alternatives with similar qualities and see where the risk reward trade off looks more appealing to you.
- For investors who put capital strength first, compare Nova with companies screened for balance sheet resilience through our list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced quality rather than headline stories, line up Nova beside a 32 high quality undervalued stocks and see how its profile stacks up.
- Those who want to keep volatility in check can weigh Nova against a 31 resilient stocks with low risk scores that might better fit a more defensive approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com