


EN
VEON Stock Earnings Turnaround Raises The Bull Case Changed?
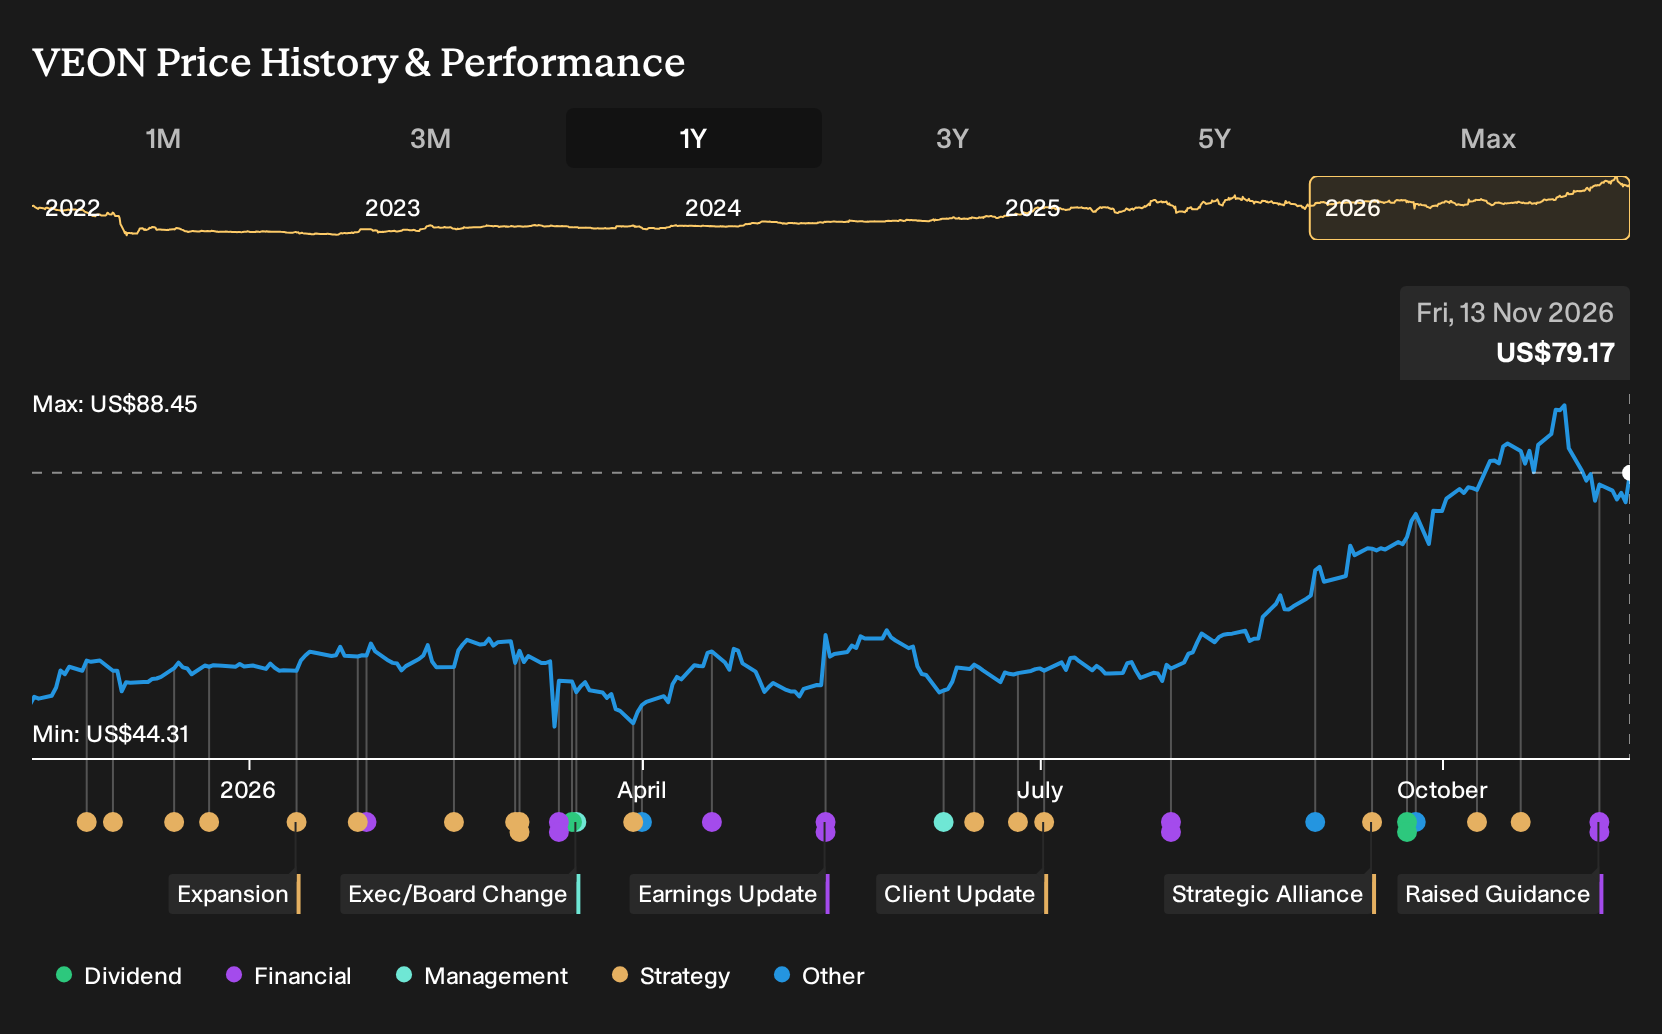
- VEON reported third quarter 2026 sales of US$1,307 million and net income of US$188 million, compared with a loss a year earlier, and management lifted full year revenue growth guidance to a 16% to 18% range.
- Behind the headline profit swing, VEON continues to lean on digital and financial services such as Kyivstar and JazzCash. The company is using tools like AI and non terrestrial networks to keep users connected and spending even in conflict and high inflation markets.
- We will assess how VEON's improved quarterly profitability and higher revenue guidance interact with its digital ecosystem thesis and risk profile.
Scan beyond VEON and this guidance upgrade by checking out a curated set of telecom and digital platform plays in the 32 high quality undervalued stocks that may still be priced for scepticism.
VEON Investment Narrative Recap
To own VEON, you need to believe its push into digital platforms and financial services can offset tough macro conditions in Pakistan, Ukraine and other core markets. The raised 2026 revenue growth guidance to 16% to 18% signals management confidence in that ecosystem thesis, although the step up from 15% is modest rather than transformative.
The near term swing back to a US$188 million quarterly profit puts attention on whether VEON can keep earnings resilient while inflation, energy costs and tax changes bite. The biggest operational swing factor is still execution in high margin digital services, while the key risk is that rising costs and outages pressure cash generation.
The analyst consensus Narrative on Simply Wall St leans heavily on VEON’s digital ecosystem and fintech scale up as core earnings drivers. The recent third quarter showing, with US$1,307 million in sales and a move from a loss to US$188 million in net income, gives investors fresh data on how that thesis translates into reported profitability.
Against that backdrop, the Apna Microfinance Bank acquisition plan in Pakistan looks central to the catalyst list. Folding Apna’s branches into Mobilink Microfinance Bank would deepen JazzCash style services, but it also adds execution risk on integration, potential regulatory delay and the challenge of earning adequate returns when inflation, energy costs and taxation are already pressuring margins.
What VEON's Long Range Forecasts Assume
Analysts sketch a fairly demanding glide path for VEON. Their work implies that revenue needs to reach US$6.4b and earnings US$798.9m by 2029, built on forecast top line expansion of 10.3% a year and an increase in profit margins from 1.2% to 12.5% over roughly three years. That profit target reflects a jump in earnings from US$59.0m today, which would require an increase of about 13.5x to reach the US$798.9m consensus level by 2029.
Uncover how VEON's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on VEON’s Bangladesh digital bank plan as the real swing factor. Before this latest guidance raise, they were pencilling in revenue of about US$6.7b and earnings of roughly US$907.8m by 2029. You can treat this as one possible storyline and compare it with more cautious forecasts that may shift after these results.
Explore 4 other VEON fair value estimates, including one that suggests there could be up to 786% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your VEON research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for VEON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VEON's overall financial health at a glance.
Looking for more investment ideas beyond VEON?
If VEON has sharpened your thesis around digital platforms and higher risk markets, it can help to line it up against other opportunities with different balance sheet strength, income profiles and growth angles using the Simply Wall St Screener.
- For investors who want quality and value together, compare VEON with a 32 high quality undervalued stocks that blend solid fundamentals with prices that still imply caution.
- If capital preservation and steadier profiles matter more to you, weigh VEON against a 31 resilient stocks with low risk scores that score well on business stability and risk factors.
- When you are hunting for future leaders rather than established giants, contrast VEON with a 20 high quality undiscovered gems that show strong underlying metrics but limited attention so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com