


EN
Raised Revenue Outlook Might Change The Case For Investing In Hensoldt (XTRA:HAG)
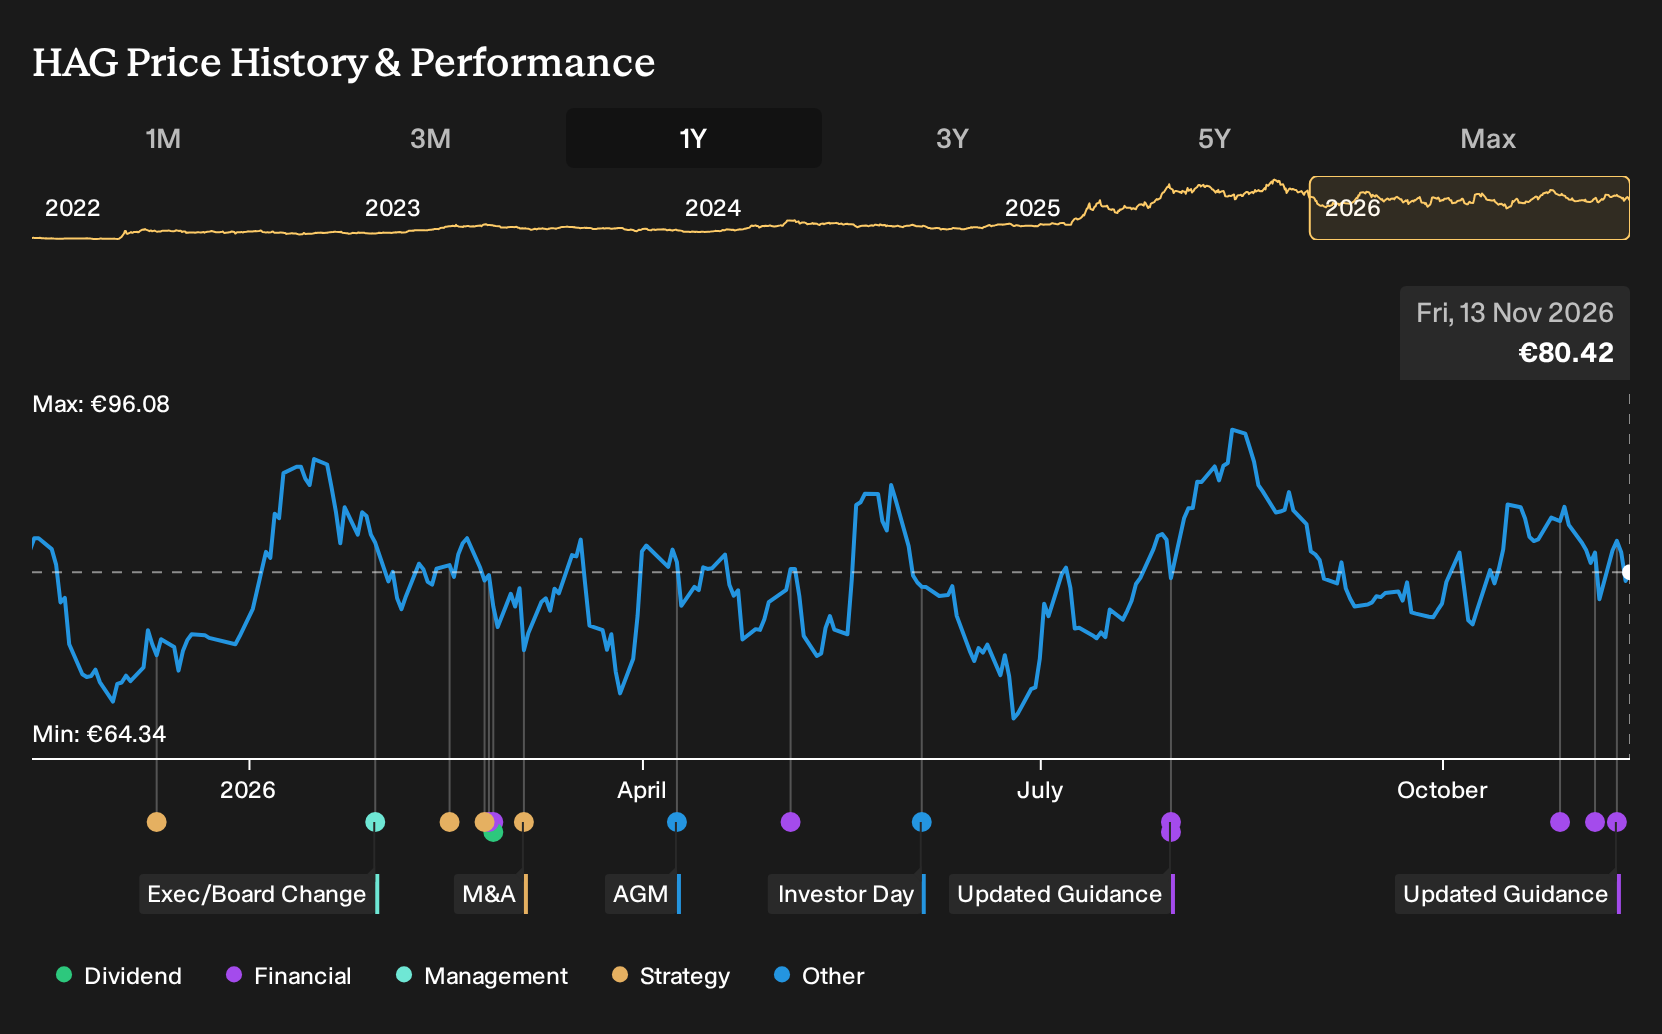
- Hensoldt recently raised its 2026 revenue guidance to around €2,800 million from about €2,750 million and issued new 2027 to 2028 earnings guidance that targets annual revenue growth of 15% to 20%.
- The tighter 2026 revenue range and explicit multi year growth targets give investors more concrete milestones to judge Hensoldt's execution on its expanding defense electronics backlog and capacity plans.
- Now the focus shifts to how Hensoldt's higher 2026 revenue target might reshape the investment narrative built around backlog conversion and Operations 2.0.
Hensoldt Investment Narrative Recap
To stay invested in Hensoldt, you need to be comfortable with a simple idea. The sensor and defense electronics backlog only turns into value if Operations 2.0 really eases engineering and supply chain bottlenecks. The raised 2026 revenue guidance and new 2027 to 2028 growth targets sharpen that execution test rather than changing it.
For the near term, the clearest potential catalyst remains faster conversion of the more than €10b order book into sales and margins, as outlined in the analyst consensus Narrative on Simply Wall St. The key risk is that capacity and technology upgrades lag complex programs like Luchs 2 or PEGASUS batch 2, which could hold back free cash flow and keep the high P/E under pressure.
The most relevant announcement is Hensoldt's outlook for annual revenue growth of 15% to 20% in 2027 and 2028. This sits directly on top of the Operations 2.0 story, since that kind of step up depends on new radar lines, smoother logistics and better engineering throughput actually working at scale.
For you, that guidance turns operational milestones into clear checkpoints. Progress on easing the roughly 1.5 year order to revenue lag, ramping programs like TRML 4D and PEGASUS batch 2, and managing the high debt load becomes the checklist that will likely drive sentiment around the existing backlog and any reassessment of valuation.
Hensoldt's current earnings of €120.0 million are projected by analysts to reach €415.7 million by 2029, which implies roughly a 3.5x increase in profit. This projection is underpinned by forecast annual revenue growth of 17.2% and a revenue target of €4.3 billion in the same year.
Discover why Hensoldt's fair value suggests a potential 14% upside to its current price, which may be realized sooner than many investors expect.
Exploring Other Perspectives
One alternate angle on Hensoldt focuses on bullish analysts who already expected about €4.5b of revenue and €478.8 million of earnings by 2029, before this new guidance. That view leans on software-heavy programs and airborne ISR as the real engine. It is a more optimistic story that could shift further as guidance resets sink in. Compare both narratives before deciding what makes sense to you.
Explore 3 other Hensoldt fair value estimates, including one that suggests as much as 84% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hensoldt research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hensoldt. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hensoldt's overall financial health at a glance.
Looking for more investment ideas beyond Hensoldt?
Once you have formed a view on Hensoldt, it can help to compare that thesis with opportunities across other sectors and balance sheet profiles using the Simply Wall St Screener.
- If you care most about sturdy finances and cleaner leverage profiles, start with a list of solid balance sheet and fundamentals (198 results) to see which companies offer stronger balance sheets.
- For investors hunting for mispriced quality, use the 198 high quality undervalued stocks to scan for businesses where fundamentals and market price appear out of sync.
- When stability and lower downside risk matter more than rapid growth, focus on a 210 resilient stocks with low risk scores to surface stocks that score better on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com