


EN
Is Eton Pharmaceuticals (ETON) Undervalued Following Strong Q3 Results And Raised Guidance?
Eton Pharmaceuticals (ETON) drew investor attention after reporting third quarter results that shifted from a loss to a profit, raising full year revenue guidance and releasing encouraging early ET-700 tolerability data.
Eton Pharmaceuticals has already seen a sharp re-rating, with the share price up 293.17% year to date and a 1-year total shareholder return of 277.39%. The recent 20.90% 1-month share price return suggests momentum is building as investors reassess both earnings power and pipeline risk.
Capitalize on the momentum around Eton Pharmaceuticals by scanning a curated shortlist of rare disease and specialty treatment players in the 20 high quality undiscovered gems.Given Eton Pharmaceuticals has already moved hard on fresh earnings and ET-700 data, the puzzle now is simple: Does the current price already reflect that shift, or is there still a valuation gap?
Most Popular Narrative: 11% Undervalued
On the analyst consensus Narrative on Simply Wall St, Eton Pharmaceuticals screens as undervalued, with a fair value of $71.50 against a last close of $63.93. This points to a discount anchored in rare disease cash flow assumptions and margin guidance rather than short term trading swings.
Operating leverage is becoming more visible as adjusted EBITDA margin reached 49% in Q3 2026 on US$57.9 million of revenue. Full-year 2026 margin guidance was lifted to above 40%, while management continues to signal potential for further gross margin gains toward and above 75% as the rare disease portfolio scales. This can support stronger earnings power relative to past periods.
See why 19 investors see Eton Pharmaceuticals as 11% undervalued.
Result: Fair Value of $71.50 (UNDERVALUED)
Still, the Eton Pharmaceuticals story leans heavily on a concentrated rare disease portfolio and optimistic analyst forecasts that could reset quickly if margins or launch timelines slip.
Find out about the key risks to this Eton Pharmaceuticals narrative.
Another View: What The P/E Ratio Says About Eton Pharmaceuticals
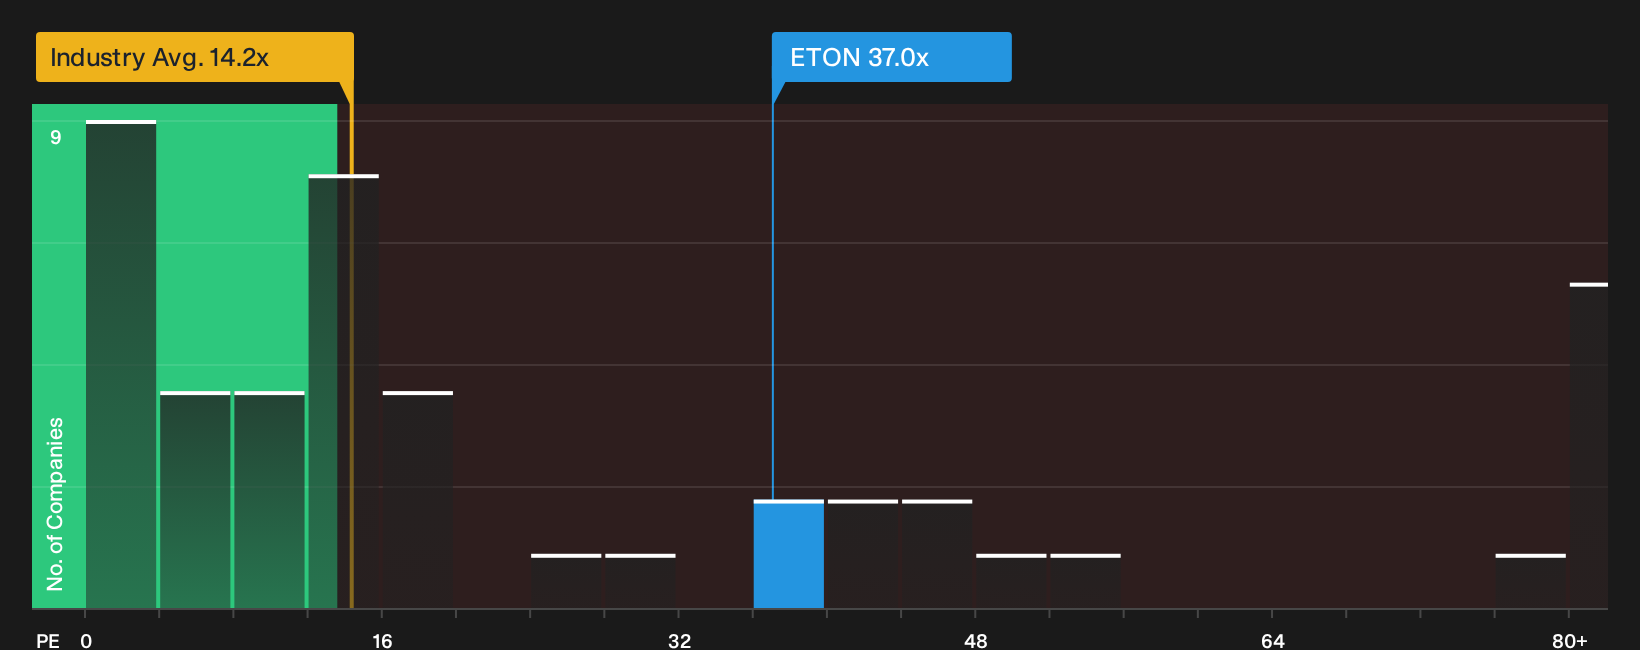
The analyst and narrative fair value work up suggests Eton Pharmaceuticals looks undervalued. The P/E ratio tells a different story. At roughly 37x earnings versus 14.2x for the wider US pharmaceuticals group and 10.6x for close peers, the stock trades on a much richer multiple. Even against an estimated fair ratio of 26.3x, the current pricing looks stretched. This raises the question: is the premium simply the cost of owning a fast growing rare disease platform, or a valuation risk if sentiment cools?
To pressure test those earnings expectations against peers and that fair ratio, the next step is to see what the numbers say about this price in the valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism runs through this Eton Pharmaceuticals story, yet the market is also pricing in clear fault lines that could matter for you. Act while the data and sentiment are fresh, and weigh both sides of the ledger with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Eton Pharmaceuticals?
If Eton Pharmaceuticals is already on your radar, broaden your opportunity set with fresh ideas pulled from Simply Wall St's screeners while this momentum is front of mind.
- Target resilient cash generators and compare them with Eton by scanning a list of solid balance sheet and fundamentals (24 results) that can help you sidestep fragile balance sheets.
- Spot potential mispricings early and pressure test your thesis by reviewing a 32 high quality undervalued stocks before the rest of the market catches up.
- Build a portfolio that sleeps well at night by studying a 31 resilient stocks with low risk scores designed to surface stocks with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com