


EN
Did Jefferies Upgrade Just Shift Procore Stock Investment Narrative?
- Procore Technologies reported third quarter 2026 sales of US$402.31 million with a net loss of US$4.59 million, and issued fourth quarter revenue guidance of US$420 million to US$422 million alongside full year 2026 guidance of US$1.557 billion to US$1.559 billion.
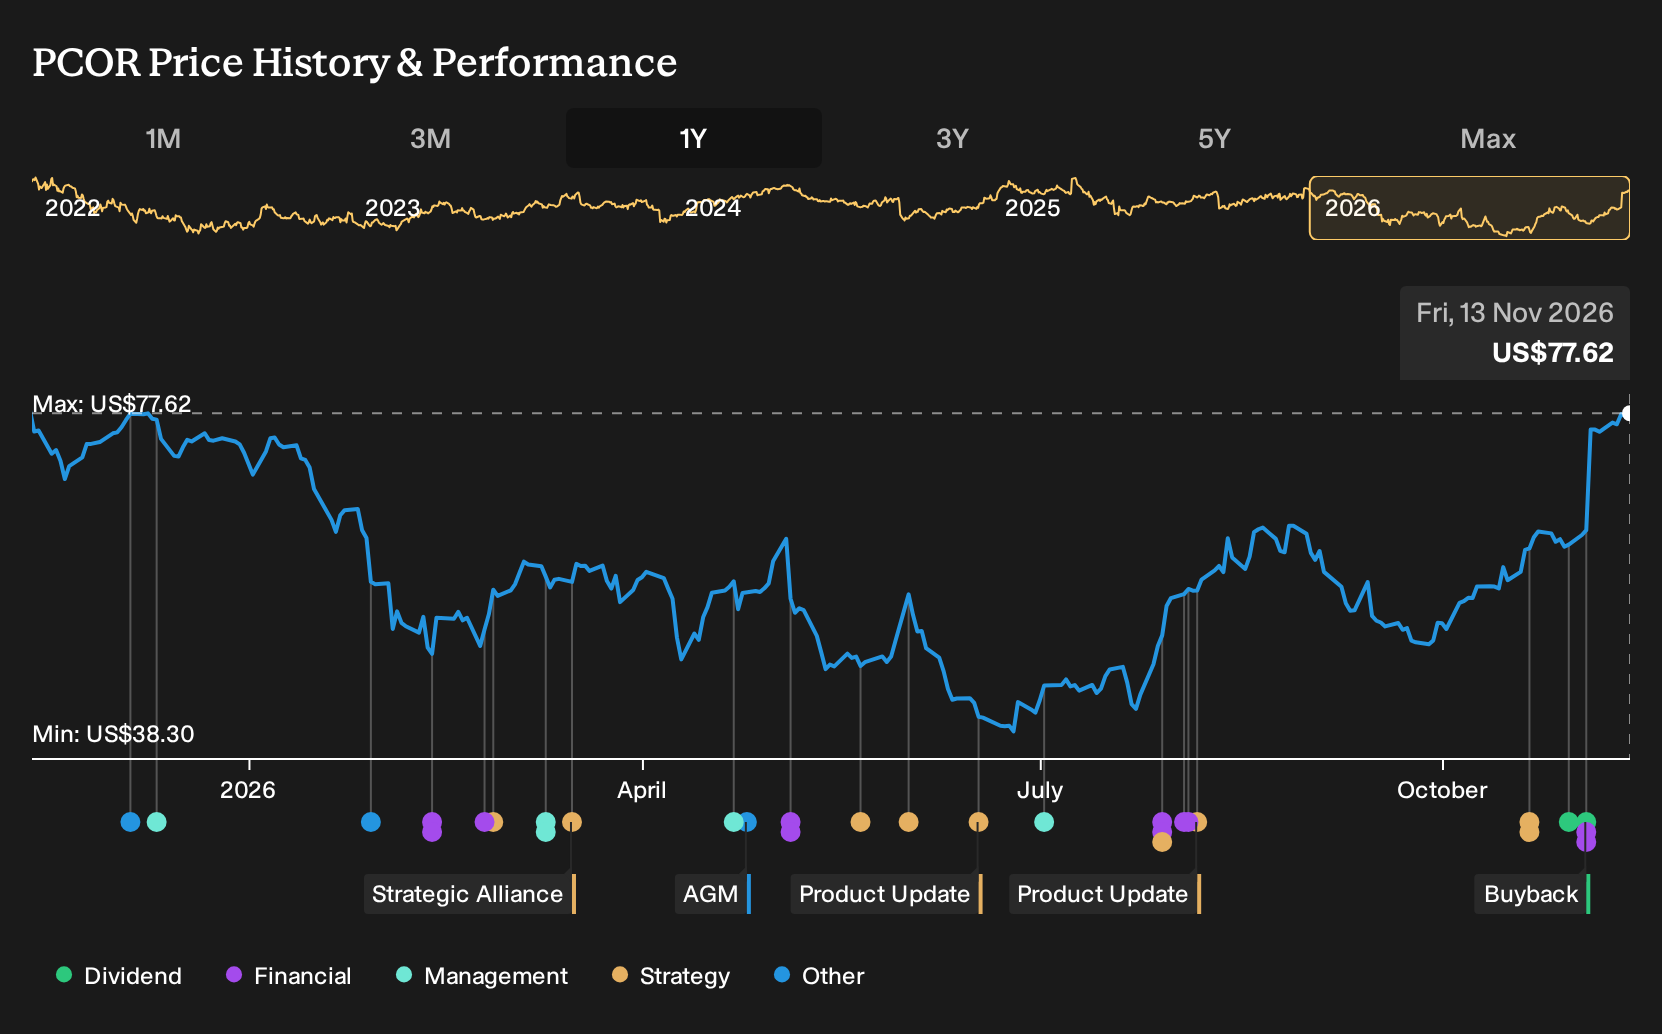
- The business also authorized a US$300 million share repurchase program funded from working capital, signaling confidence in its balance sheet, while analyst commentary highlights operational improvements and AI monetization as key themes.
- The focus will now be on how Procore Technologies’ earnings guidance and new buyback program fit into the existing long-term investment narrative.
Compare Procore Technologies’ guidance and buyback plans with other potential breakouts by scanning our hand picked list of 32 high quality undervalued stocks that score well on both quality and price discipline.
Procore Technologies Investment Narrative Recap
For you to own Procore Technologies, the analyst consensus Narrative on Simply Wall St suggests you need to believe its construction platform, AI tools and multi stakeholder model can keep attracting users while expense discipline holds. The latest quarter shows sales of US$402.31 million and a small net loss of US$4.59 million, so the near term story still turns on execution.
The most important short term catalyst remains whether the firm can translate AI usage, owner adoption and international wins into steady subscription growth without needing heavy extra sales spending. The biggest risk is that slower revenue expansion and rising customer acquisition costs squeeze margins, and this update does not remove that concern.
The new US$300 million share repurchase plan, funded from working capital and running through October 30, 2027, is the headline move tied to this news. It directly interacts with catalysts built around improving profitability and cash generation, because consistent buybacks generally rely on surplus cash once core investment needs are met.
For you as an investor, the program sits alongside guidance for fourth quarter revenue of US$420 million to US$422 million and full year 2026 revenue of about US$1.557 billion to US$1.559 billion. Attention now stays on whether Procore Technologies can support this capital return while managing costs, scaling AI products and avoiding the slower growth and margin pressure highlighted in the risk section.
Procore Technologies' narrative projects US$2.6b revenue and US$298.4 million earnings by 2029. This rests on analysts assuming 19.8% yearly revenue growth and an earnings increase of about US$332.8 million from current earnings of a US$34.4 million loss.
Uncover how Procore Technologies' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts the Procore Technologies buyback front and center as a risk rather than a plus. The most bearish analysts already penciled in slower annual revenue growth of about 14.6% and earnings of roughly US$194.1 million by 2029, and they worry extra capital returns could tighten flexibility. Those projections and the Q4 and 2026 revenue guidance were set before this update, so you should expect opinions to shift as fresh numbers and the repurchase plan feed into new models.
Explore 4 other Procore Technologies fair value estimates, including one that suggests as much as 64% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Procore Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Procore Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procore Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Procore Technologies?
If the Procore Technologies story has sharpened your thinking about quality, risk and price, it can help to line it up against a wider bench of opportunities using the Simply Wall St Screener.
- For investors who want income that aims to be both sizable and better supported by underlying cash flows, take a look at 6 dividend fortresses that focus on payouts with substance behind them.
- If downside resilience matters most to you, filter for companies with sturdier financial profiles by running a list of solid balance sheet and fundamentals (24 results) that puts balance sheet strength and fundamentals front and center.
- When you want to widen the net for future growth candidates without paying up blindly, scan through a 20 high quality undiscovered gems that highlight quieter businesses with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com