


EN
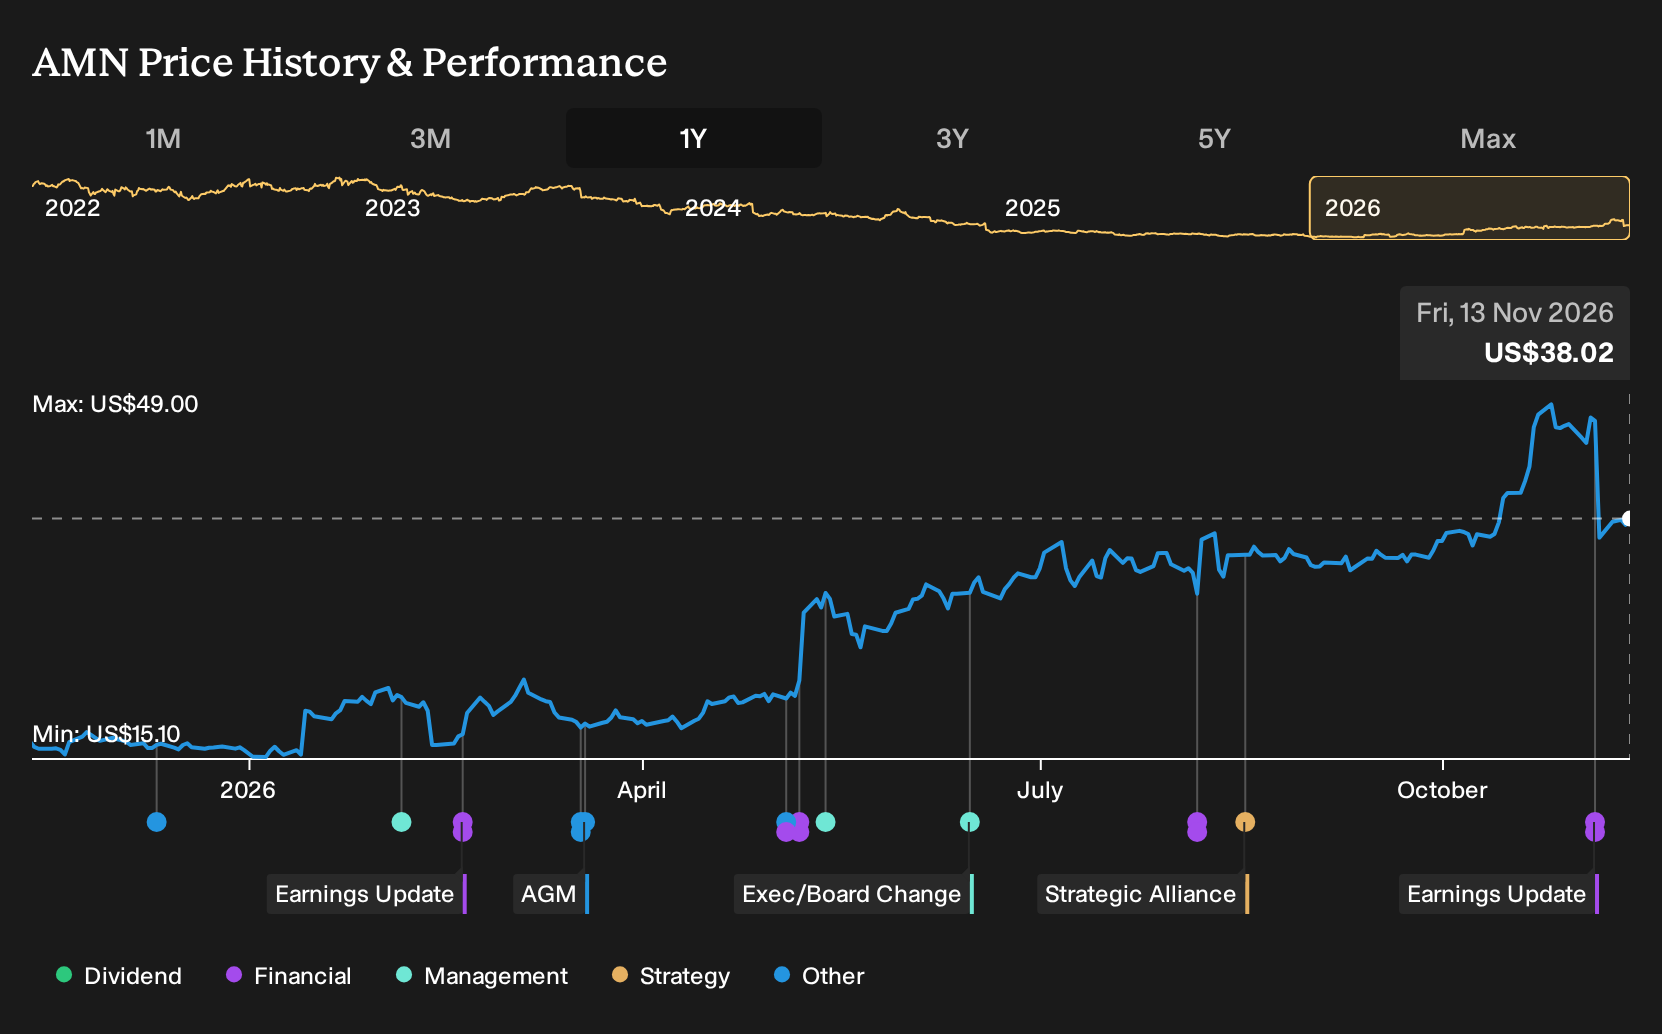
How Stronger Earnings At AMN Healthcare Services (AMN) Has Changed Its Investment Story
- AMN Healthcare Services reported third quarter 2026 sales of US$717.27 million and net income of US$33.39 million, with basic earnings per share from continuing operations of US$0.85 and diluted earnings per share of US$0.83.
- For the first nine months of 2026, AMN Healthcare Services moved from a net loss to net income of US$116.72 million, signalling a sharp shift in profitability alongside higher reported sales.
- We will now explore how AMN Healthcare Services' updated fourth quarter revenue outlook could reshape the existing investment narrative for the business.
Scan how AMN Healthcare Services compares with other potential turnaround stories by reviewing a curated group of 20 high quality undiscovered gems that pair improving fundamentals with recent earnings catalysts.
AMN Healthcare Services Investment Narrative Recap
To stay invested in AMN Healthcare Services, you need to be comfortable with a story where healthcare staffing demand is real, yet profitability is tight and uneven across segments. The analyst consensus Narrative on Simply Wall St already builds in expectations for declining revenue and earnings, so the third quarter profit and higher nine month sales mainly confirm the business can still execute through that tougher backdrop.
The short term catalyst is whether AMN can stabilise margins while hospitals balance contingent staff against internal hires. The updated outlook for a fourth quarter operating margin between a slight loss and a slim profit keeps pressure on that test. The main risk remains softer volumes or pricing in weaker units weighing on the overall mix.
The clearest new data point is AMN Healthcare Services' fourth quarter 2026 guidance. Management now expects consolidated revenue between US$655 million and US$670 million with an operating margin between a 0.1% loss and a 0.5% profit. That range frames how much operating leverage may realistically come through in the near term while the group absorbs segment level headwinds.
For you, this guidance ties directly back to the earlier risks around pricing pressure in Technology and Workforce Solutions and slower recoveries in Physician and Leadership Solutions. If the business can hold even a modest positive margin on slightly lower projected sales while those units are under strain, it may support the view that improved nine month profitability is not just a one off. If margin slips into the guided loss zone, it would reinforce concerns about earnings pressure already captured in analyst forecasts.
Analysts currently model AMN Healthcare Services' revenue at US$2.5b and earnings at US$72.2 thousand by 2029, which reflects an 11.3% yearly revenue decline and an earnings decrease of about US$108.9m from current earnings of US$109.0m.
Discover how AMN Healthcare Services' fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For AMN Healthcare Services, the sharpest contrast comes from the bearish focus on Technology and Workforce Solutions. Those analysts were working off expectations of a 15% revenue drop in that segment and a 10.9% annual decline in overall sales, with a US$34.0 price target. Their forecasts did not reflect the latest earnings surprise, so you may find their more cautious narrative shifts once this new information is fully absorbed. That gap in views is exactly why it helps to compare several analyst cases before deciding how this story fits into your own portfolio.
Explore another AMN Healthcare Services fair value estimate, including one that suggests as much as 43% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your AMN Healthcare Services research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AMN Healthcare Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMN Healthcare Services' overall financial health at a glance.
Looking for more investment ideas beyond AMN Healthcare Services?
If the AMN Healthcare Services story has sharpened your thinking about risk, reward, and timing, it can help to line it up against other opportunities that fit different roles in your portfolio. The Simply Wall St Screener gives you a quick way to scan for businesses that match the mix of quality, value, and resilience you want.
- If you are hunting for quality at a reasonable price, compare AMN Healthcare Services with a wider set of potential value opportunities by reviewing 32 high quality undervalued stocks that meet strict fundamentals and pricing filters.
- For investors who care about staying on the front foot with financial strength, use the Screener to zero in on a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio through different market conditions.
- Those who prefer a smoother ride can focus on capital protection first and returns second by scanning a 31 resilient stocks with low risk scores that screens for lower volatility and stronger business quality signals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com