


EN
Top 3 Canadian Undervalued Stocks To Watch In November 2026
Inflation remains the main cue for interest rate moves according to recent comments from Federal Reserve Vice Chair Philip Jefferson, so cash flows matter more than ever for pricing risk. When borrowing costs stay uncertain, investors often look harder at businesses that generate solid cash yet trade below estimated fair value. This article highlights three Canadian stocks that screen as potentially mispriced on that basis.
The three stocks below are just a sample, and the full screen on Simply Wall St surfaced 6 more companies with equally compelling cash flow stories that are not covered here. To identify and analyze those potential opportunities with the same lens used in this article, head straight to the Undervalued Stocks Based On Cash Flows screener.
Stantec (TSX:STN)
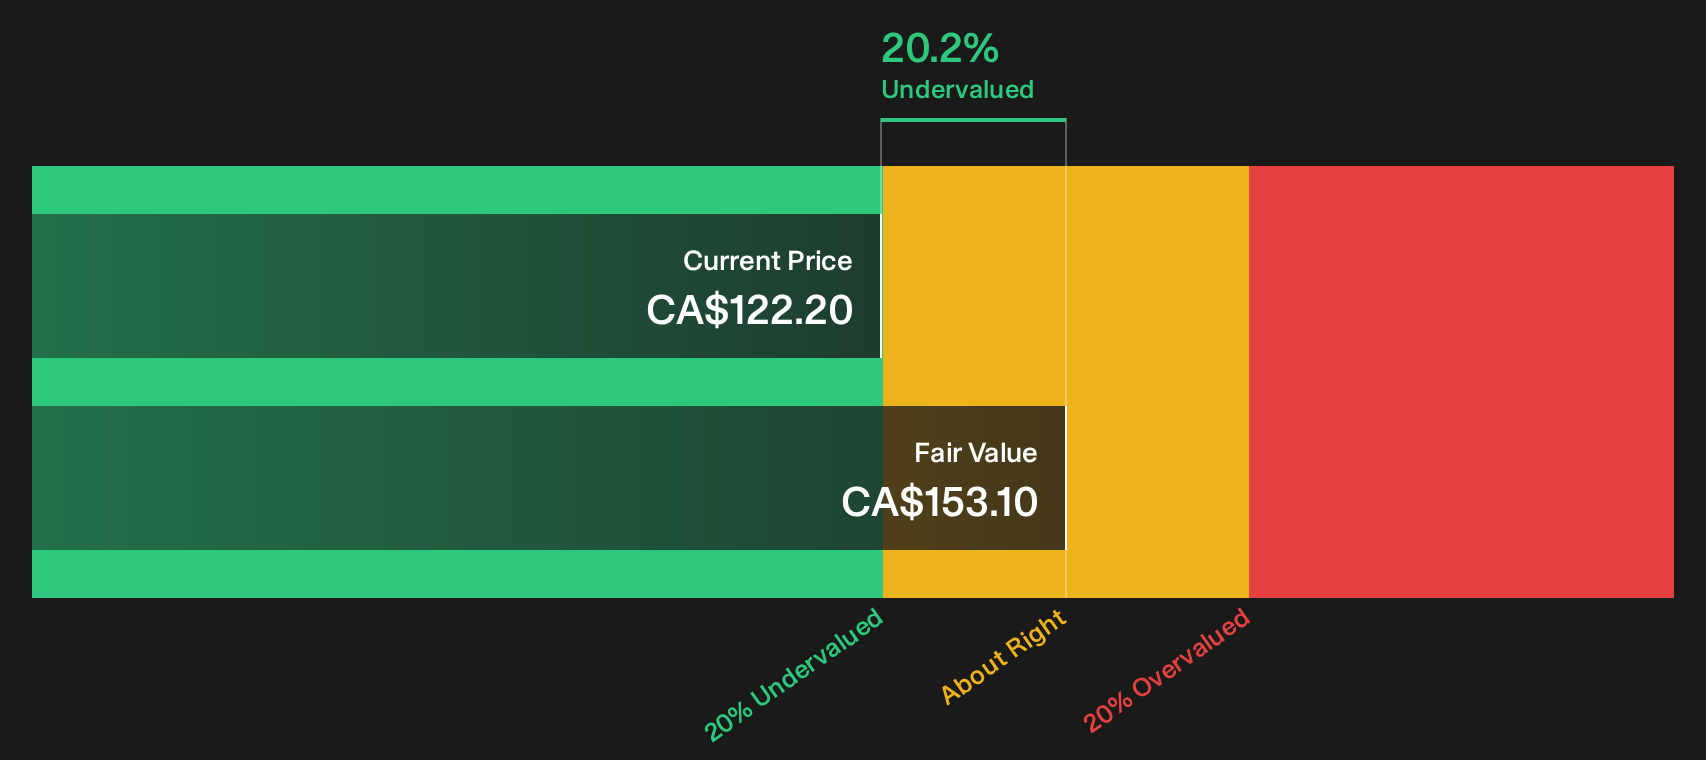
Stantec is a global design and engineering group focused on long term infrastructure, water and environmental projects that often run on multi year, fee based contracts. This aligns neatly with a cash flow driven valuation lens like the “Undervalued Stocks Based On Cash Flows” screen, and it carries a market value of about CA$11.8b.
"Recent large acquisitions such as Page, Cosgroves and Ryan Hanley have significantly expanded Stantec's presence in the U.S., New Zealand and Ireland. With Page now performing strongly and Niche in Australia added in mid 2026, the larger platform can keep widening the revenue base and support future earnings growth as integration benefits continue to flow through to results."
What happens to those projected margins if a single pressure point inside that growing project backlog does not break the way analysts expect?
If that margin pressure is what worries you, full narrative for Stantec explains in detail how Stantec's cash generation, contract mix and deal pipeline could still accelerate value creation.
Barrick Mining (TSX:ABX)
Barrick Mining is a global miner focused on turning long life gold and copper deposits into recurring operating cash flows. This focus supports its fit with a cash flow based screener theme according to the analyst consensus Narrative on Simply Wall St.
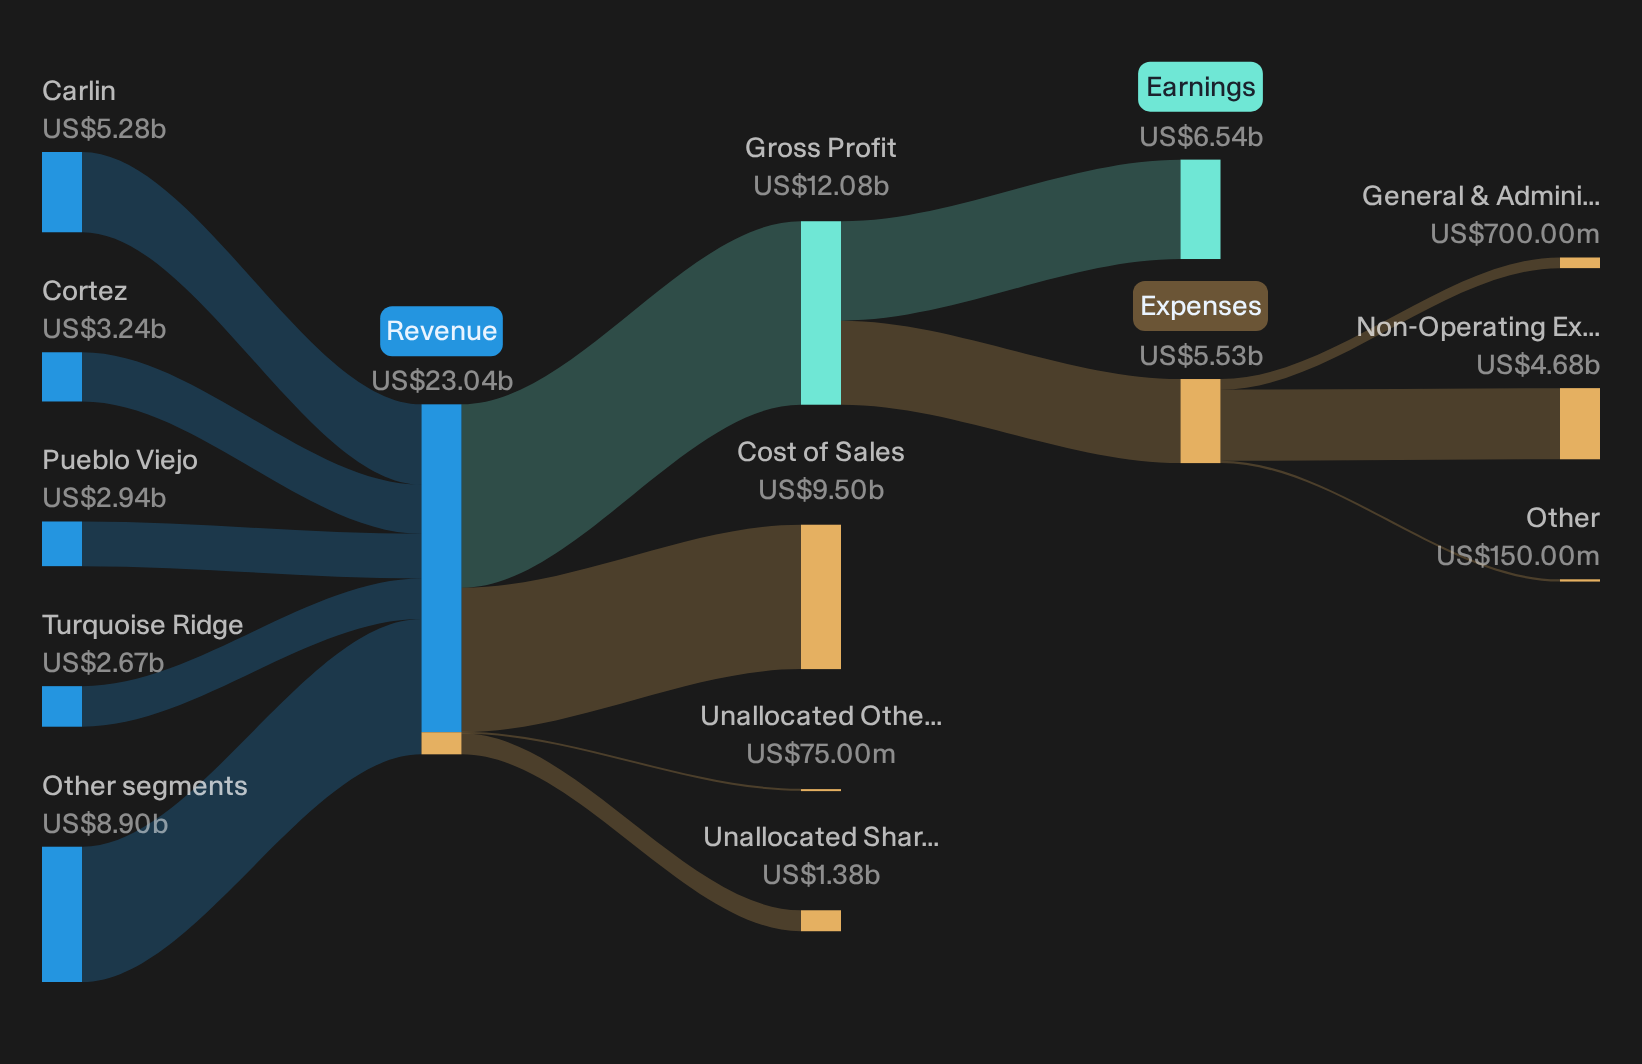
Barrick Mining Corporation produces gold and copper from a portfolio of large mines, with revenue concentrated in Carlin at about $5.3b, Pueblo Viejo at roughly $2.9b, Turquoise Ridge at $2.7b and Cortez at $3.2b, and the business carries a market value near $87.9b.
"Agreement with Newmont to restructure the Nevada Gold Mines joint venture, including bringing Fourmile and Newmont’s Mike and Fiberline assets into the JV and resolving historic disputes, is expected to let Barrick Mining reconfigure processing capacity, reduce ore trucking and pursue higher throughput in Nevada, which would directly affect group revenue and unit cash costs."
What happens to Barrick Mining’s cash focused thesis if one crucial capital allocation decision shifts the balance between higher output and tighter margins?
That capital choice is the hinge. Read the full narrative for Barrick Mining to see how Barrick Mining’s cash engine could accelerate even if margins and volumes decouple.
Headwater Exploration (TSX:HWX)
Headwater Exploration is a Calgary based oil and gas producer focused on turning its Marten Hills and McCully Field assets into cash flows from petroleum and natural gas sales, and the business carries a market value of about CA$2.8b.
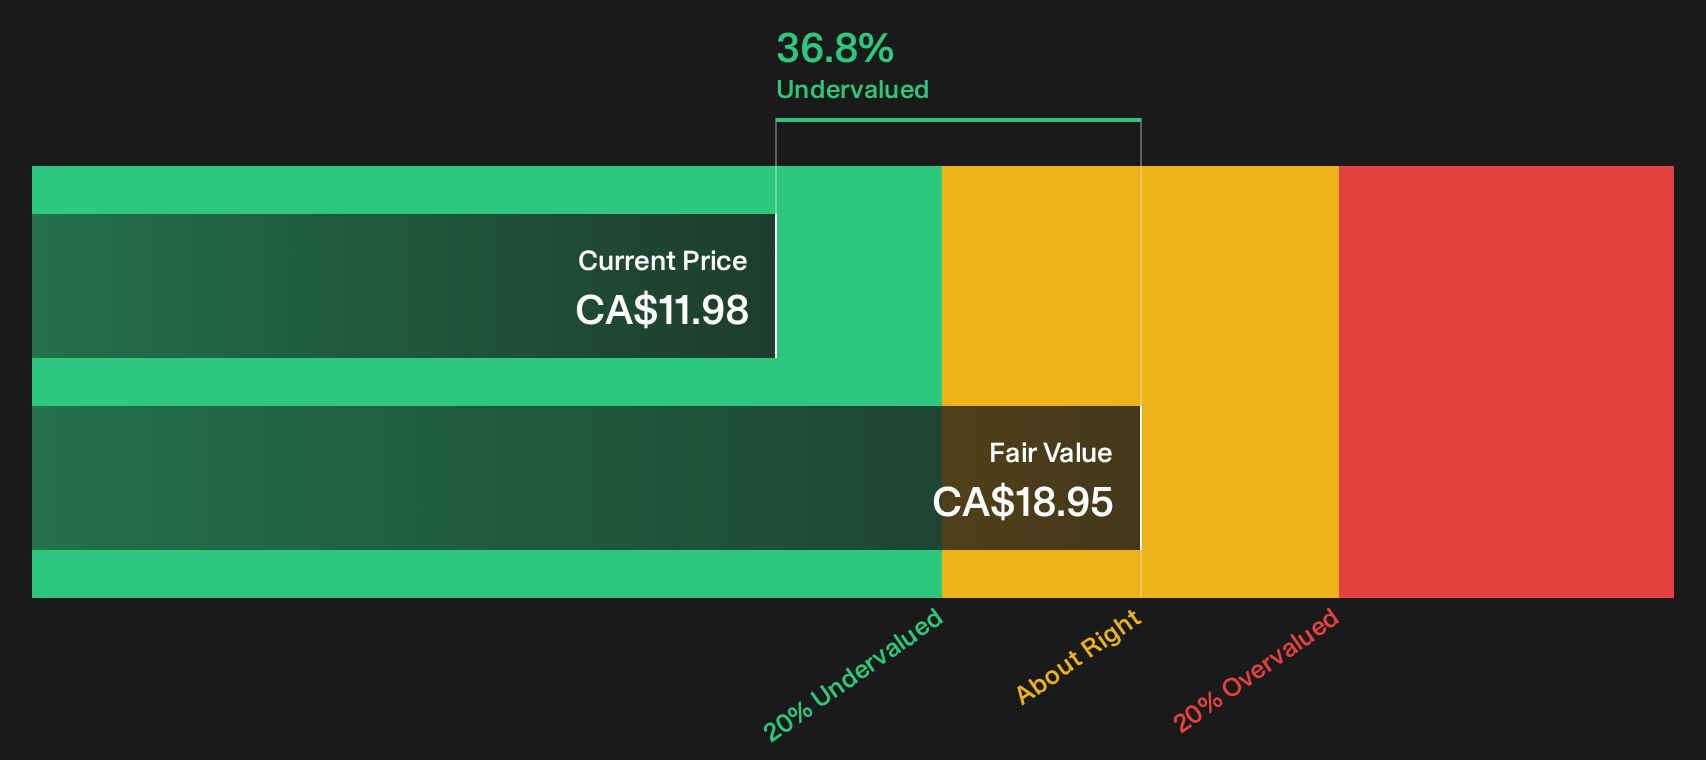
Headwater Exploration screens as undervalued on future cash flows, trading 36.8% below SWS’s DCF estimate with a 13.1x P/E against a 15.3x industry average. Strong profitability, including a 33.8% net margin and 25.4% ROE, supports that gap, depending on how one pressure point around dividend cash coverage plays out.
If you want to see whether that dividend coverage concern is already priced into Headwater Exploration, start with the DCF valuation analysis for Headwater Exploration to see what the cash math implies.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum shows on every chart, the early gap can already be closing. Scan these curated shortlists while they are still under the radar for now and get in early.
- Explore early breakout potential across cash generative businesses by running the 7 high quality undervalued stocks before the crowd reacts to any new momentum.
- Look for resilient cash payers that continue rewarding patient holders across different market conditions with the 3 dividend fortresses while yields still compensate you for the risk.
- Focus on miners with production strength linked to a metal that investors often approach at different points in the cycle using the curated 33 elite gold producer stocks list.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com