


EN
Upcoming Earnings Might Change The Case For Investing In AZZ Stock (AZZ)
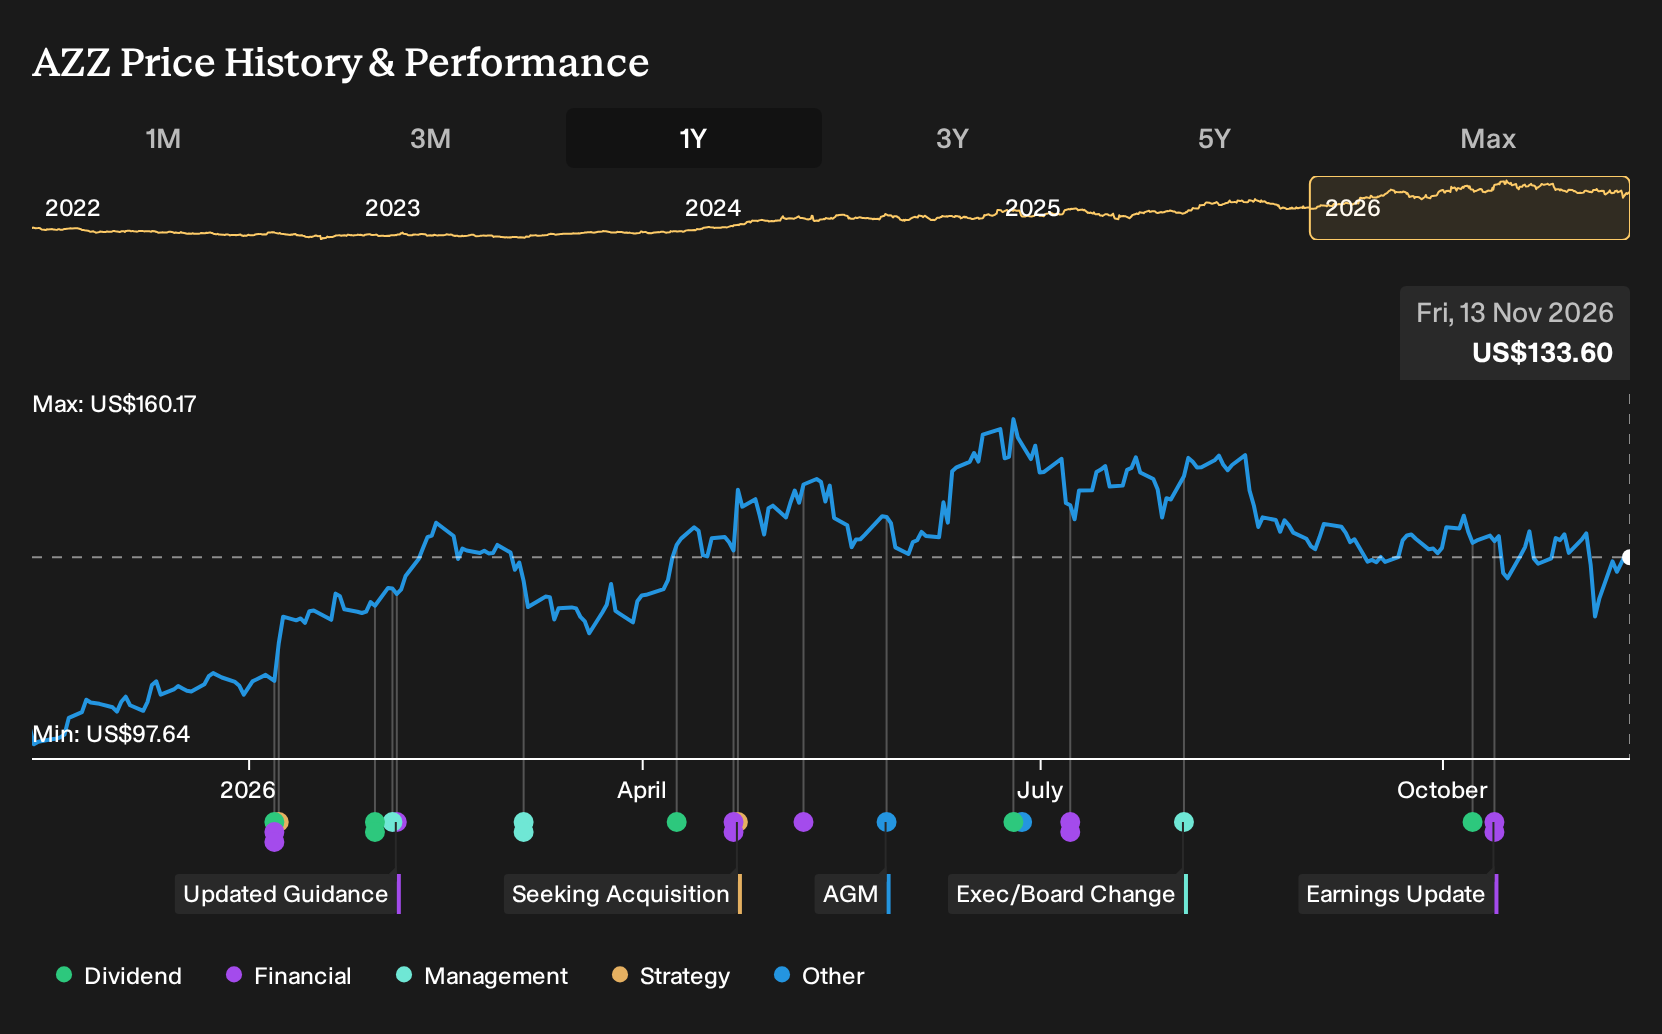
- AZZ has recently drawn attention as analysts highlight expectations for earnings of $1.82 per share in the next release, alongside consensus forecasts for full year earnings and revenue growth supported by its Metal Coatings and Precoat Metals operations.
- The focus on bringing projects like the Washington, Missouri Precoat facility toward target utilization, integrating acquisitions such as Seattle Galvanizing, and rolling out digital platforms to improve plant efficiency underscores how operational execution is central to AZZ's current story.
- We will now explore how AZZ's expected earnings strength, built on more efficient Metal Coatings and Precoat Metals operations, might reshape its investment narrative.
Look beyond AZZ and see how other metal coating and infrastructure linked businesses are positioning with our hand picked 43 power grid technology and infrastructure stocks
AZZ Investment Narrative Recap
To own AZZ, you need to be comfortable with a story built on getting more out of existing plants rather than chasing headline revenue. The emphasis is on Metal Coatings and Precoat Metals running cleaner, with better utilization at sites like Washington, Missouri and steadier throughput supported by digital tools. The expected $1.82 per share in the upcoming print keeps execution in the spotlight rather than changing the core thesis.
The main near term catalyst is how smoothly these facilities run over the next few quarters, particularly through tougher winter conditions that previously cut roughly 200 production days. The biggest risk remains operational hiccups, including weather, underused capacity or integration challenges at acquisitions such as Seattle Galvanizing, which could keep margins and cash generation uneven.
The analyst consensus narrative on Simply Wall St highlights Washington, Missouri moving toward target utilization as a key operational swing factor, and that context matters alongside the expected $1.82 in upcoming earnings. That plant shifting from ramp up mode to more normalized output would spread fixed costs across higher volumes and support steadier profitability from Precoat Metals.
Digital Galvanizing System and CoilZone rollouts fall into the same category of practical catalysts. They are aimed at lifting throughput and trimming unit costs rather than changing AZZ’s end markets. At the same time, investors still need to monitor familiar risks, including weather exposure, raw material pricing and the timing of new kettle and greenfield capacity reaching planned performance.
AZZ's narrative projects US$2.0b revenue and US$227.8 million earnings by 2029. This assumes 6.0% yearly revenue growth and an earnings increase of about US$29.4 million from US$198.4 million today.
Uncover how AZZ's fair value indicates a 23% potential upside to its current price before the discount to AZZ closes.
Exploring Other Perspectives
One bullish twist on AZZ leans hard into infrastructure demand. The most optimistic analysts were penciling in revenue of about US$2.1b and earnings near US$285.8 million by 2029, well above the consensus path. Those forecasts were set before this earnings news, so views may change as fresh data becomes available.
Explore 2 other AZZ fair value estimates, including one that suggests as much as 23% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AZZ research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AZZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AZZ's overall financial health at a glance.
Looking for more investment ideas beyond AZZ?
Once you have a view on AZZ, it often helps to compare it with other opportunities that fit different objectives, from value hunting to income or resilience. The Simply Wall St Screener can narrow that universe quickly so you can focus on a short list that actually matches your priorities.
- For investors who want potential value with quality fundamentals, start with a curated set of 32 high quality undervalued stocks that may warrant a closer look.
- If portfolio resilience matters most to you, you can filter for steadier balance sheets through a focused list of solid balance sheet and fundamentals (24 results) that may help support that goal.
- Those targeting returns from income rather than price moves can source yield ideas from a hand picked group of 6 dividend fortresses that clear a 5% hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com