


EN
Rigetti Computing (RGTI) Could Be 13% Undervalued After 2026 Revenue Guidance
Rigetti Computing (RGTI) is back in focus after its third quarter 2026 report paired softer sales with a sharply smaller net loss, followed by fresh full year 2026 revenue guidance of about $20 million.
The latest earnings and guidance landed into a weak tape for Rigetti Computing, with the share price down 18.13% over the past week and 48.88% over 90 days, and the year to date share price return down 59.24% despite a very large 3 year total shareholder return that still sits far above the listing level. This pattern points to fading near term momentum as investors reassess both growth potential and execution risk around the new 2026 revenue target at a current price of $9.62.
Scan beyond Rigetti Computing and see how other quantum and advanced computing plays are setting up right now with the hand picked 25 quantum computing stocks.
Bulls see Rigetti Computing as a discounted way into quantum computing growth, while bears point to ongoing losses and sharp share price declines. Which side do the current valuation markers support next?
Most Popular Narrative: 13% Undervalued
Rigetti Computing last closed at $9.62, while the leading narrative fair value sits at $11.09, which points to a modest discount that keeps attention on how near term contract timing feeds into that gap. According to DanielOliveira, an investor in the Simply Wall St Community who wrote the narrative, the immediate debate is less about distant quantum potential and more about how the next couple of quarters line up against expectations.
The revenue build. Rigetti said three systems would ship in 2026: two 9-qubit Noveras and a 108-qubit machine for C-DAC in India. Both Noveras shipped in the first half, which is why revenue jumped to $4.4 million in Q1 and $5.1 million in Q2 after under $2 million a quarter through 2025. The $8.4 million C-DAC order is booked for Q4. That leaves Q3 with no planned system delivery. I model $0.8 million of hardware and parts, $0.9 million of research and $0.1 million of cloud access. That''s $1.8 million, against a $3.68 million consensus (12 analysts, October 5 snapshot).
See why 2 investors see Rigetti Computing as 13% undervalued.
Result: Fair Value of $11.09 (UNDERVALUED)
Still, the narrative could crack if the C DAC acceptance test timing shifts, or if fresh Novera contracts alter the short term revenue mix.
Find out about the key risks to this Rigetti Computing narrative.
Another View On Rigetti Computing’s Valuation
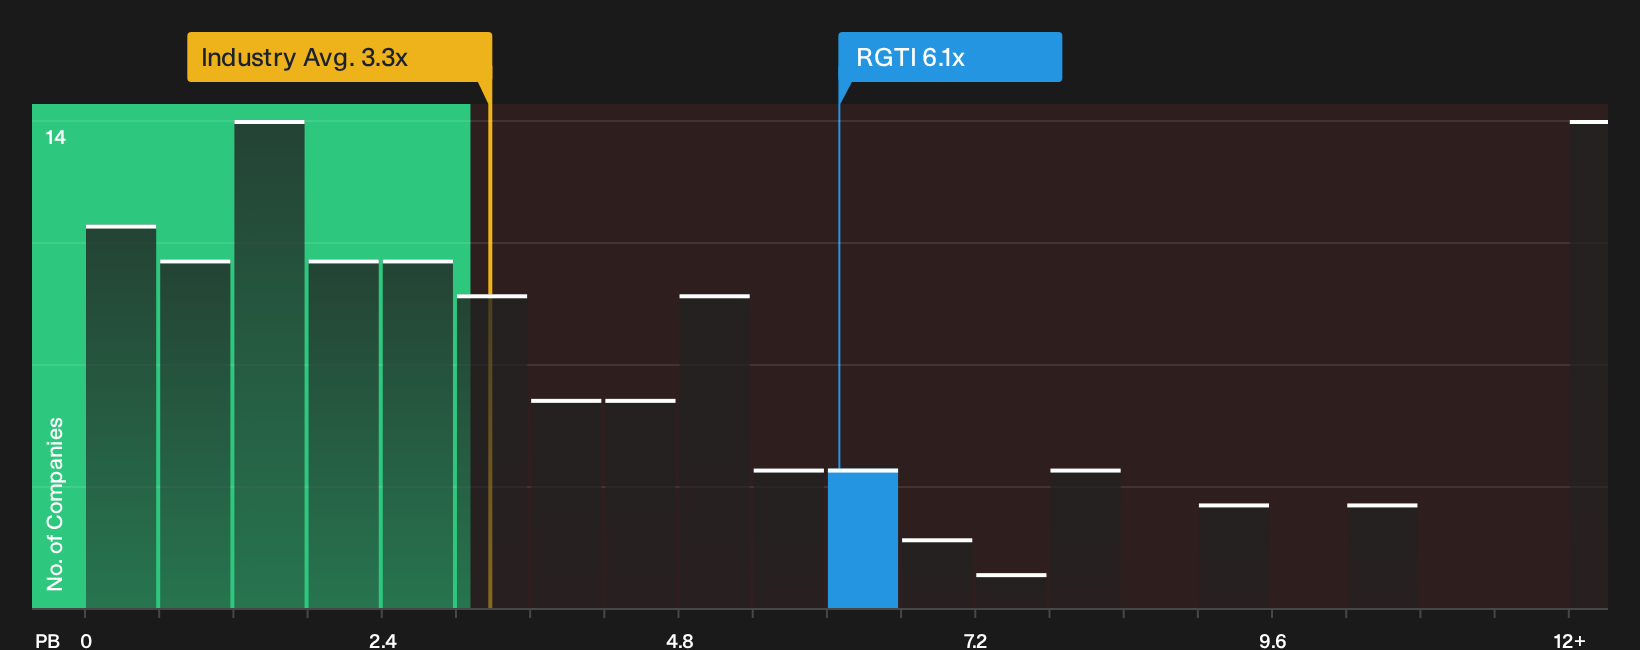
There is a different signal once you look at Rigetti Computing through a simple P/B lens instead of the $11.09 fair value from the community narrative. The stock trades around 6.1x book value, while the US semiconductor group averages 3.3x and close peers are near 4.9x.
That higher ratio suggests investors are already paying a premium for a business that is still loss making and not forecast to turn profitable over the next three years. For anyone weighing the 13% discount to narrative fair value against a richer balance sheet multiple, the key question is which anchor matters more for the next decision point.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Rigetti Computing can feel messy, so move quickly, test the numbers for yourself, then weigh the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Rigetti Computing?
If Rigetti Computing has you rethinking your watchlist, now is the moment to widen the search before the next wave of opportunities gets crowded.
- Target resilient balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that many investors overlook until the market turns.
- Hunt for quality at a discount with the 32 high quality undervalued stocks so you are not chasing moves after the rerating has already happened.
- Spot less crowded opportunities early by tracking the 20 high quality undiscovered gems before they attract broad attention and tighter pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com