


EN
Is ABM Industries (ABM) Fully Priced After Expanding Its Phoenix Suns Partnership?
ABM Industries (ABM) just expanded its three-year partnership with the Phoenix Suns and Phoenix Mercury, extending facility services to team headquarters and practice sites. This move puts fresh attention on how this sports footprint fits into the wider business.
Over the past year, ABM Industries has quietly built momentum, with the share price delivering a 28.02% year to date return and a 13.53% 90 day share price gain, while total shareholder return sits at 33.39% over one year and 42.32% across three years. This suggests investors are gradually pricing in both recent wins like the Suns and Mercury partnership and a changing view on the business’s long term prospects.
Scan how ABM Industries compares to other facilities and infrastructure operators gaining traction in high-traffic venues with the curated 31 resilient stocks with low risk scores.
After a 28% year to date run and a new high profile sports contract, the key tension is simple: Is most of ABM Industries’ upside already in the rearview, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 2% Undervalued
On the analyst consensus Narrative on Simply Wall St, ABM Industries screens as modestly undervalued, with a fair value of about $55.93 against the latest close of $54.64. This puts more weight on technical infrastructure and cash generation than on headline sports deals.
The strong growth in ABM Industries semiconductor, microgrid, and data center activities, which generated nearly US$775 million of year to date revenue in FY26 at a double digit blended operating margin and now exceed 11% of company revenue, points to a larger share of earnings coming from technical infrastructure end markets that could lift consolidated margins and earnings power.
See why 11 investors see ABM Industries as 2% undervalued.
Result: Fair Value of $55.93 (UNDERVALUED)
Still, the ABM Industries story depends heavily on higher margin semiconductor and microgrid contracts converting from pipeline to revenue, and on current free cash flow levels proving repeatable.
Find out about the key risks to this ABM Industries narrative.
Another View On ABM Industries Valuation
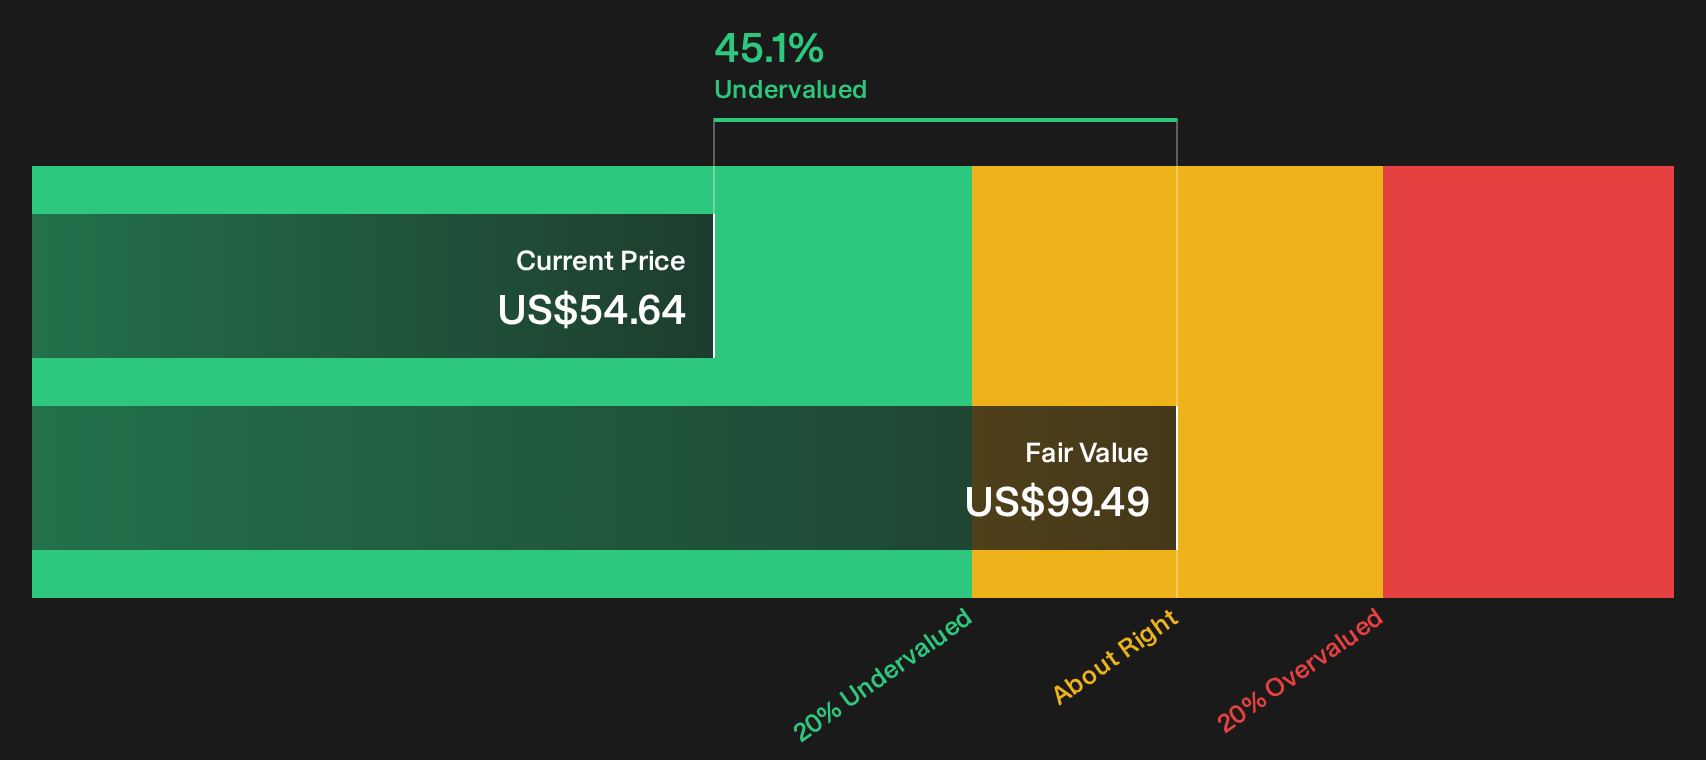
While the analyst narrative pegs ABM Industries at a fair value of $55.93, the SWS DCF model paints a different picture. On that cash flow view, ABM at $54.64 screens as significantly undervalued relative to an estimated future cash flow value of $99.49. Which lens do you trust more when real money is on the line?
Our DCF model is fully transparent if you want to test how sensitive this gap is to your own assumptions about margins, contract wins, and discount rates. Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed messages so far, right. If you want to move quickly and build your own view on ABM Industries, start with the balance between risk and upside that other investors are already weighing, then compare those against its sports and infrastructure contracts using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ABM Industries
If ABM Industries has your attention, do not stop here. The best opportunities often sit just off your radar, and a few minutes of focused screening can surface ideas you would otherwise miss.
- Target dependable compounding by reviewing companies that appear mispriced on quality and valuation through the 32 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by filtering for robust balance sheets and durable fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Get an early look at potential future leaders by scanning a focused set of underfollowed opportunities via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com