


EN
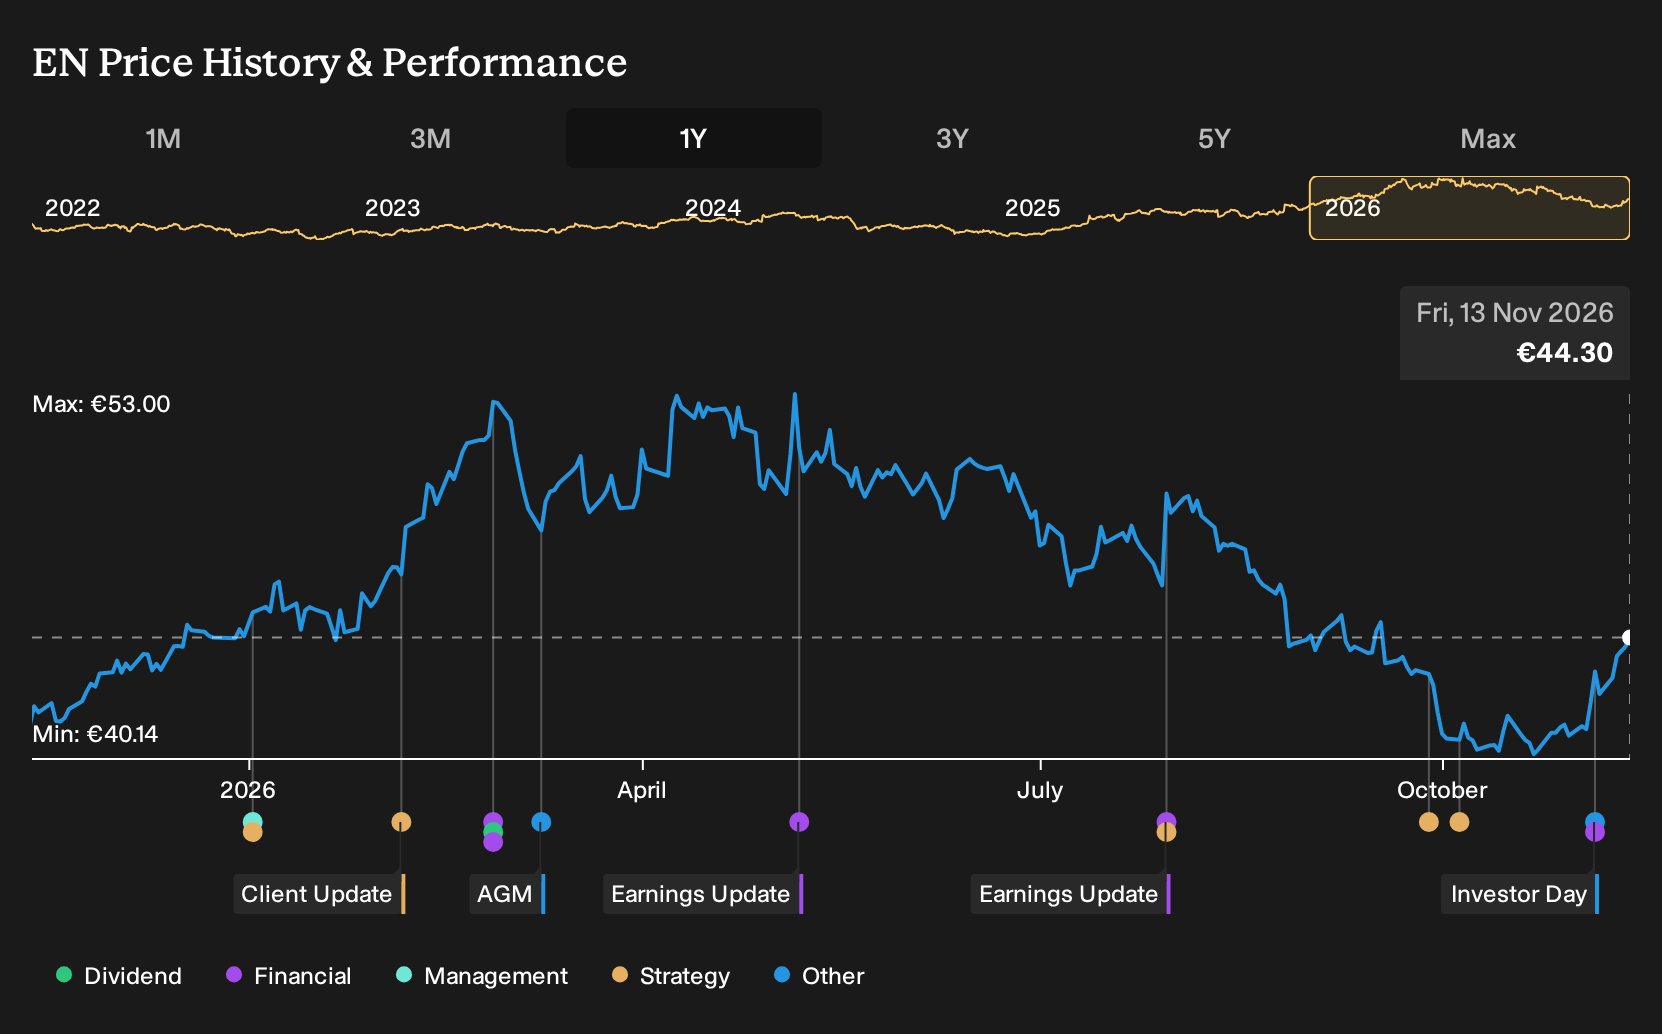
How Weaker Earnings At Bouygues Shares Has Changed Its Investment Story
- Bouygues reported third quarter 2026 sales of €15,343 million and net income of €19 million, with basic earnings per share from continuing operations at €0.05.
- The nine month 2026 figures show sales of €41,635 million but net income of €306 million and basic EPS of €0.79, indicating earnings pressure despite broadly steady activity levels.
- This article now examines how Bouygues’ sharply lower quarterly net income may influence the longer term investment narrative around the group.
Bouygues Investment Narrative Recap
To stay invested in Bouygues, you need to be comfortable with a diversified group where construction, Equans, telecom and media each pull earnings in different directions. The analyst consensus Narrative on Simply Wall St leans heavily on Equans’ higher margin order book and disciplined execution to support group profitability. The latest quarter shows that one off items and softer profitability can still swamp that story in the short term.
For now, the key near term swing factor remains how reliably Equans converts its record €27.6b order book into cash flow while French construction and telecom pricing stay competitive. The biggest risk is that weak margins, combined with high debt and a dividend not fully covered by earnings, limit financial flexibility if another low profit quarter appears.
The most relevant recent development is Equans lifting its COPA margin to 5.2% in the first half of 2026 and raising full year guidance to the same level. That operational progress sits in sharp contrast with the third quarter 2026 group net income of €19 million and puts even more weight on Equans as a stabiliser for Bouygues.
If Equans continues to execute on that high quality order book in areas such as data centres, solar and storage, it can partially offset earnings pressure from Bouygues Telecom’s competitive market and TF1’s linear advertising headwinds. Your decision comes down to how comfortable you are with that mix of improving operations in one segment and compressed profitability at group level after these results.
Bouygues’ analyst narrative points to revenues of €60.7b and earnings of €1.6b by 2029, based on 2.5% yearly revenue growth and an earnings increase of about €300m from current earnings of €1.3b.
Discover why Bouygues' fair value indicates a 35% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts treat Bouygues’ Equans cash conversion as the real catalyst. They were pencilling in revenue of about €63.3b and earnings of €1.9b by 2029, much higher than the baseline. After a quarter where net income came in at €19 million, you can see how those upbeat forecasts might be revisited. Use this gap in expectations as a prompt to compare several viewpoints before deciding how you feel about the story.
Explore 2 other Bouygues fair value estimates, including one that suggests there could be as much as 65% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bouygues research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bouygues. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bouygues' overall financial health at a glance.
Looking for more investment ideas beyond Bouygues?
If Bouygues has sharpened your focus on earnings quality, balance sheets and income resilience, it can help to line it up against a wider set of opportunities using the Simply Wall St Screener.
- For investors who want potential mispricings with strong fundamentals, widen your search through 559 high quality undiscovered gems and see which businesses share a similar quality profile.
- If capital preservation and stability matter most to you, filter for stocks with stronger financial buffers by reviewing the list of solid balance sheet and fundamentals (198 results) to see which balance sheets look more robust on key metrics.
- When you care about smoother portfolio returns, scan the 210 resilient stocks with low risk scores to identify companies with risk profiles that may better match your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com