


EN
How Strong Earnings At Farmer Mac (AGM) Has Changed Its Investment Story
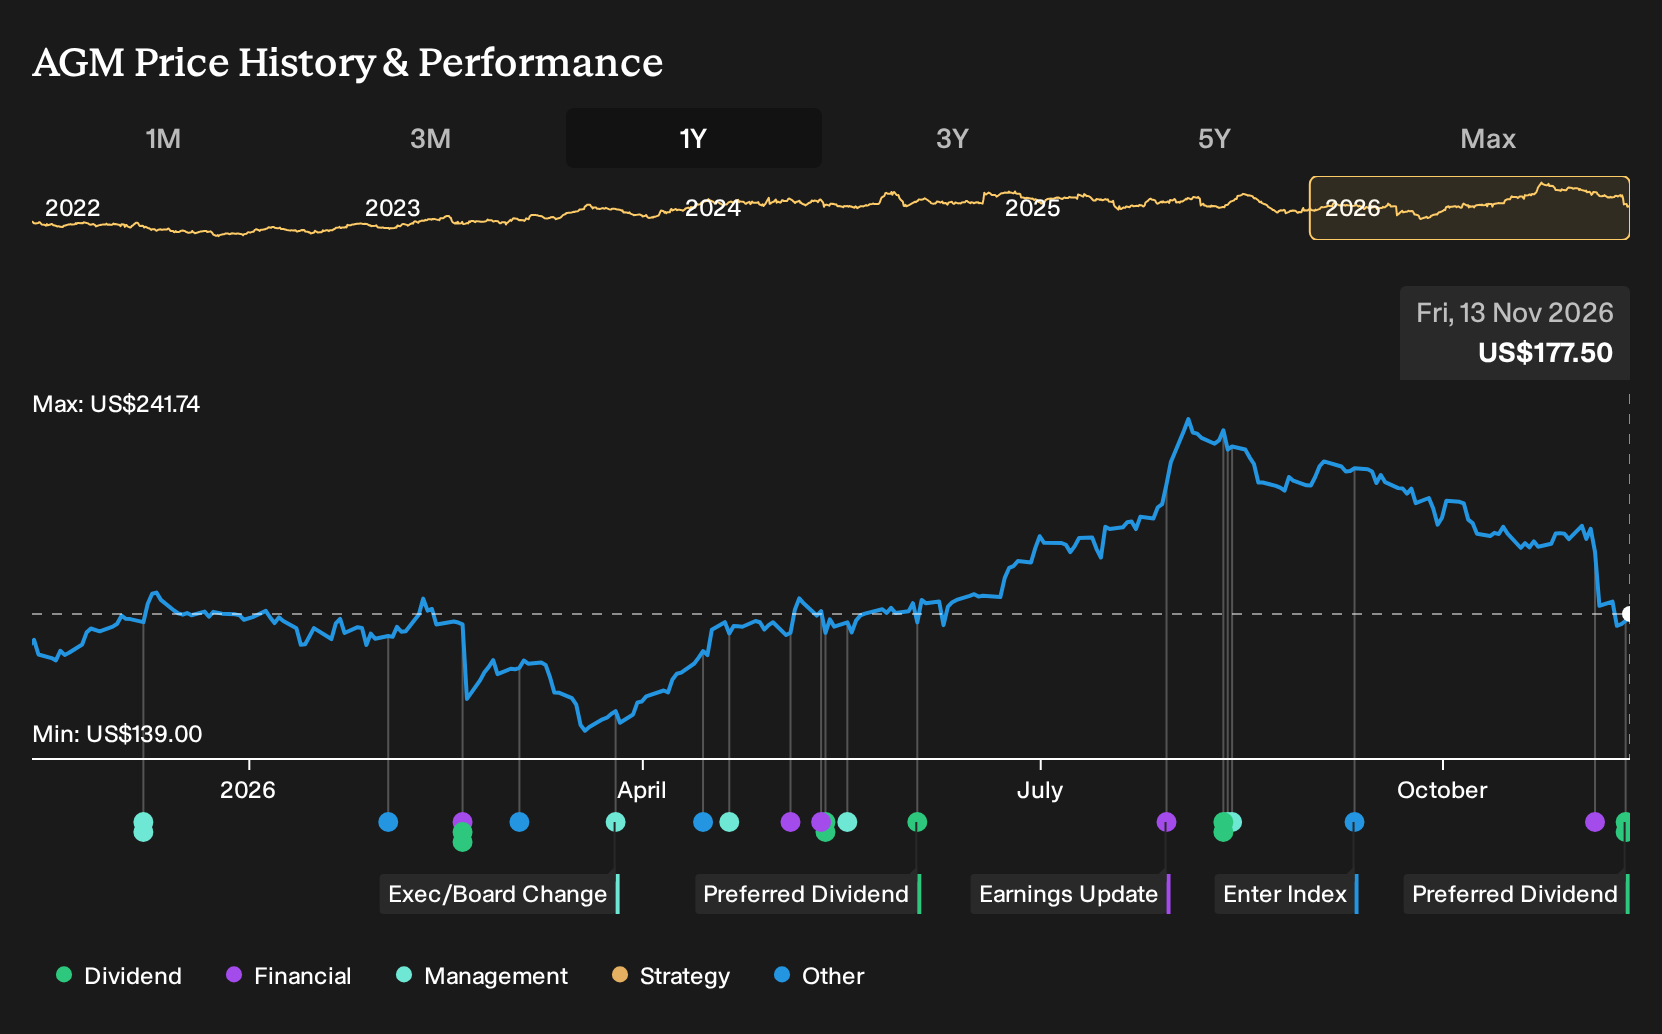
- Federal Agricultural Mortgage reported third quarter 2026 net income of US$64.21 million and basic EPS from continuing operations of US$5.06, alongside a declared fourth quarter common dividend of US$1.60 per share and scheduled preferred dividends for six preferred series in early 2027.
- The combination of higher year to date earnings and continued cash returns across both common and preferred stock indicates that Farmer Mac is currently balancing profit generation with ongoing capital distribution commitments.
- The next area of attention is how Federal Agricultural Mortgage's investment narrative aligns with this profitability and sustained dividend commitment.
Scan how Federal Agricultural Mortgage's mix of earnings strength and cash returns compares with other dividend focused plays by reviewing our hand picked list of 6 dividend fortresses.
Federal Agricultural Mortgage Investment Narrative Recap
To own Federal Agricultural Mortgage, you need to be comfortable with a secondary market lender that focuses on turning its Farm & Ranch and infrastructure pipelines into profitable volume while keeping credit costs under control. The analyst consensus narrative on Simply Wall St assumes earnings growth, but rising provision expenses and pockets of borrower stress in agriculture remain the key operational overhang.
The most important short-term swing factor is whether credit quality stays manageable as the business increases exposure to rural infrastructure, broadband and renewable projects. The latest earnings and dividend news do not materially change that; they simply reinforce that profitability and capital returns are currently running in parallel to those credit and funding risks.
The recent decision to declare a US$1.60 per share fourth quarter dividend on each common class is the clearest new data point. For an investor, it connects the story to the earlier point that earnings and dividends are moving alongside record business volume in areas such as renewable energy and broadband, where capital demand is high.
That payout, together with the scheduled preferred dividends, also shifts focus back to funding and balance sheet resilience, which analysts already flag as an area to watch. With debt not well covered by operating cash flow and all liabilities tied to external borrowing, execution on credit discipline and funding costs still matters more for the Federal Agricultural Mortgage thesis than the latest dividend declaration itself.
Federal Agricultural Mortgage's analyst narrative points to forecast 2029 revenues of US$621.5 million and earnings of US$286.8 million. This implies yearly top line growth of 15.0% and an earnings increase of US$86.8 million from US$200.0 million today to reach that 2029 consensus level.
Discover how Federal Agricultural Mortgage's fair value indicates a 45% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value estimates for Federal Agricultural Mortgage from 2 private investors in the Simply Wall St Community span roughly US$257 to about US$282 per share. This relatively tight band still reflects different conviction levels. Options pricing, credit costs and renewable policy risk pull expectations in different directions, so explore these contrasting views before forming your own stance.
Explore another Federal Agricultural Mortgage fair value estimate, including one that suggests as much as 59% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Federal Agricultural Mortgage research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Federal Agricultural Mortgage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Federal Agricultural Mortgage's overall financial health at a glance.
Looking for more investment ideas beyond Federal Agricultural Mortgage?
Once you have formed a view on Federal Agricultural Mortgage, it can help to set it alongside other opportunities that fit different goals, whether that is income resilience, balance sheet quality, or under the radar potential. The Simply Wall St Screener lets you scan for stocks that match those angles in a structured way rather than relying on headlines or hunches.
- If capital preservation sits high on your list, start with companies that screen well for stability and risk control using the 31 resilient stocks with low risk scores to see which ones fit.
- For investors searching for strong fundamentals at prices that still look reasonable, widen the lens with our hand picked set of 32 high quality undervalued stocks that pass both quality and value checks.
- Those who prefer underfollowed opportunities with solid financial footing can scan a curated pool of 20 high quality undiscovered gems that may not yet be widely watched.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com