


EN
VeriSign (VRSN) Stock May Be 43% Above Fair Value As .Web Launch Nears
VeriSign has delivered a strong run over the past few years, which puts a sharper spotlight on whether the current share price lines up with the cash the business is expected to generate. With fresh news around its future .web domain and a long track record in .com and .net, the question is how much of that potential is already reflected in today's valuation.
- Over the last 3 years, VeriSign has returned 51.7%, so a lot of investor optimism is already riding on how durable its future cash flows prove to be.
- The planned rollout of the .web top level domain, following years of dispute and a US$135 million auction bid, can influence expectations for future domain related cash generation and the timing of those inflows.
- What if you looked at VeriSign through its earnings instead? See what VeriSign's 33.0x P/E says about the price.
The issue now is whether VeriSign's current share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) estimate.
If you want to test the same cash flow question beyond VeriSign and this .web launch story, review companies in the 32 high quality undervalued stocks.
Does VeriSign Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash VeriSign can return to shareholders over time. Latest twelve month free cash flow sits at about $1.03b, and the projections assume that this stream grows steadily rather than swinging wildly or shrinking. That kind of profile tends to fit a mature, cash generative operation, where the key question is how much investors are paying for each dollar of expected future cash.
In this case, those cash flow projections point to an estimated intrinsic value that is substantially below the current share price of $313.02. The planned .web rollout, with its phased launch and premium domain potential, may help explain why enthusiasm in the market is running ahead of what the DCF implies for long term cash returns. Find out what VeriSign could be worth using our Discounted Cash Flow (DCF) estimate.
The VeriSign Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle around VeriSign leaves off and explain what path for future growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today’s price, all housed on the Community page. Rather than relying on a single multiple or DCF output, each Narrative lays out the assumptions behind its view of fair value so you can later compare those inputs with the figures VeriSign reports.
Bulls and bears are reading VeriSign's domain franchise and legal risk very differently right now.
Bull case: 7% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which compiles analysts' forecasts into a single storyline.
"The main thing that has to go right is that VeriSign continues to convert AI driven domain demand, new TLDs such as .web, and security focused products into durable growth while managing contract renewal and regulatory risks around its .com and .net registries..."
Discover why this Narrative puts VeriSign at 7% undervalued.
Bear case: 90% overvalued
According to ValueInvestor_2026, an investor in the Simply Wall St Community, internal and legal risks dominate the VeriSign story.
"Overall, while VRSN continues to benefit from exceptionally strong revenue expectations due to the repeatedly renewed monopoly over the .com and .net TLDs, the mismanagement described above non-trivially jeopardizes the continuation of this natural monopoly..."
Explore why this Narrative puts VeriSign at 90% overvalued.
One more VeriSign signal worth checking before you move on
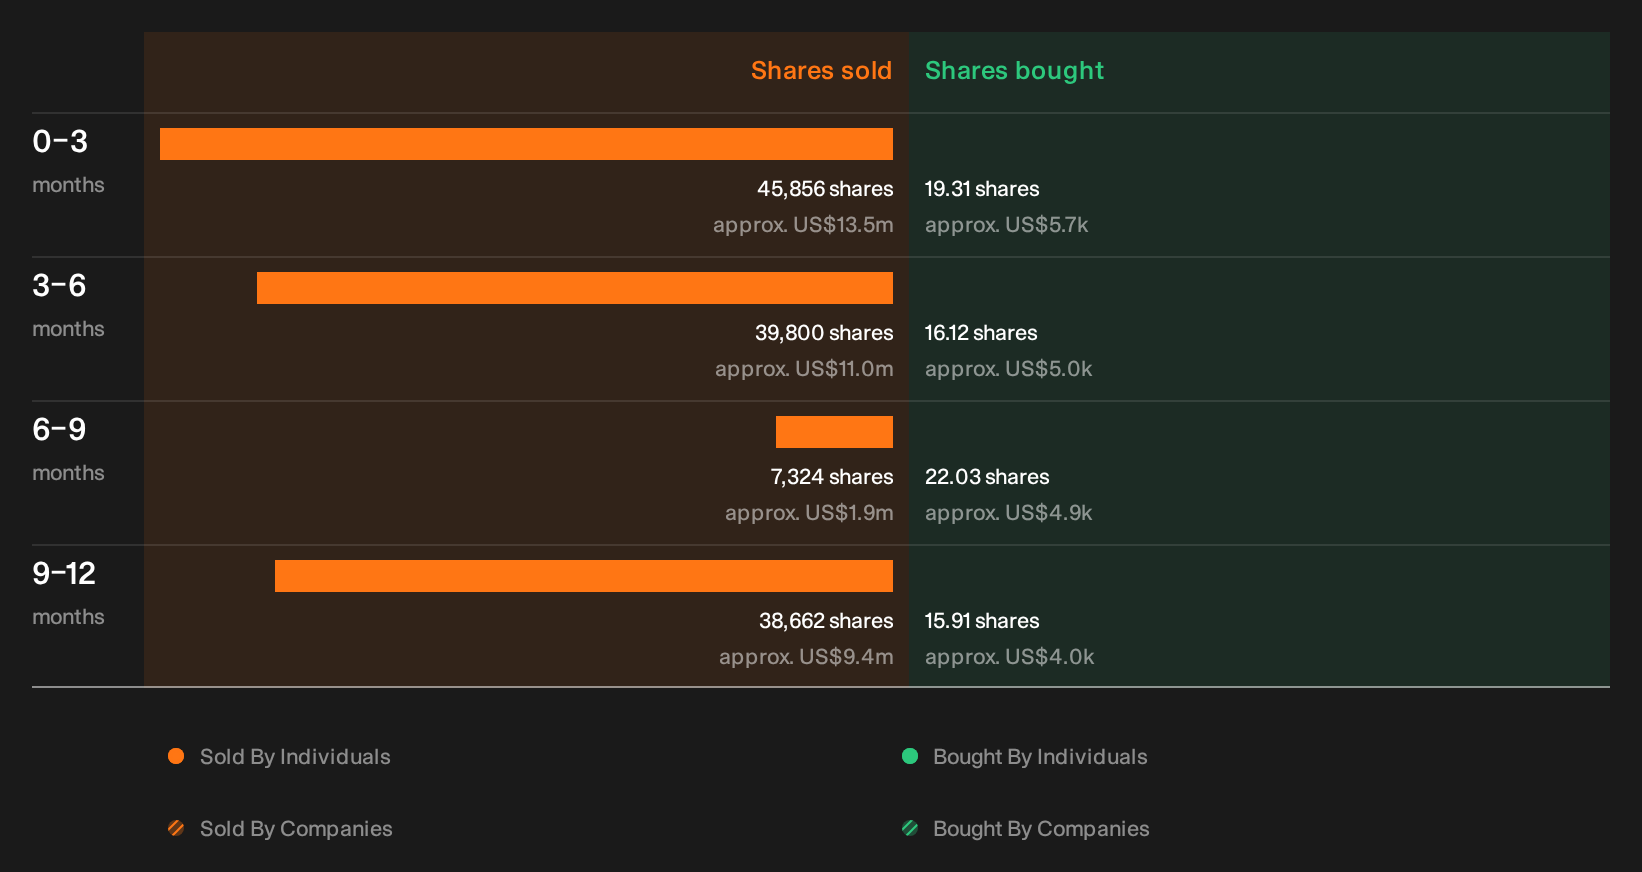
Before calling it a day on VeriSign, it is worth pausing on the recent trading activity by its own executives and directors, since the specific sellers, deal sizes and possible read-throughs are sitting in one place. See the recent insider selling flagged for VeriSign.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com