


EN
How Earnings Cuts At Baidu (BIDU) Have Changed Its Investment Story
- Baidu is heading into its November 16, 2026 earnings release with analysts expecting earnings per share to decline even as revenue is forecast to rise, while recent results showed weaker conditions in AI and legacy online marketing alongside securities class action filings tied to earlier AI disclosures.
- Fresh launches like ERNIE 5.5, the Token Exchange AI marketplace and an expanded Apollo Go footprint highlight Baidu’s push to turn heavy AI investment into concrete enterprise services, at the same time as earnings forecasts and ad market softness test how resilient that shift really is.
- We will look at how Baidu's investment narrative is tested by earnings downgrades that question the pace of AI monetisation.
Baidu Investment Narrative Recap
To stay invested in Baidu, you need to believe its heavy spending on AI Cloud, ERNIE models and Apollo Go can eventually outweigh pressure in legacy online marketing and the impact of past impairments. In the near term, the key issue is still earnings quality. Cash generation and operating leverage matter more than headline revenue growth for this story.
The upcoming November 16 earnings report now sits directly on that pressure point. Recent estimate cuts and the EPS decline expected by analysts increase scrutiny on whether AI services are scaling fast enough and whether ad weakness is stabilising. The biggest risk remains further write downs or prolonged softness in core advertising that keeps reported profit under strain.
The most relevant recent announcement for this earnings setup is Baidu’s rollout of ERNIE 5.5 and the Token Exchange AI marketplace. That launch moves the AI pitch beyond broad narratives and into a product set that enterprises can buy and measure, from model APIs to AI agents for specific workflows.
For you as a shareholder, the key operational question is simple. Do ERNIE 5.5, Token Exchange and the upgraded AI agents start to show up in AI Cloud Infrastructure metrics that have already been growing, and do they offset weaker marketing activity without requiring fresh heavy impairments? Execution on that bridge from AI usage to monetisation is the core catalyst to watch.
Baidu's narrative projects CN¥151.8b revenue and CN¥15.6b earnings by 2029. Analysts assume revenue will grow by 6.0% per year and earnings would need to move from a loss of CN¥4.7b today to CN¥15.6b, which is an improvement of about CN¥20.3b in total earnings.
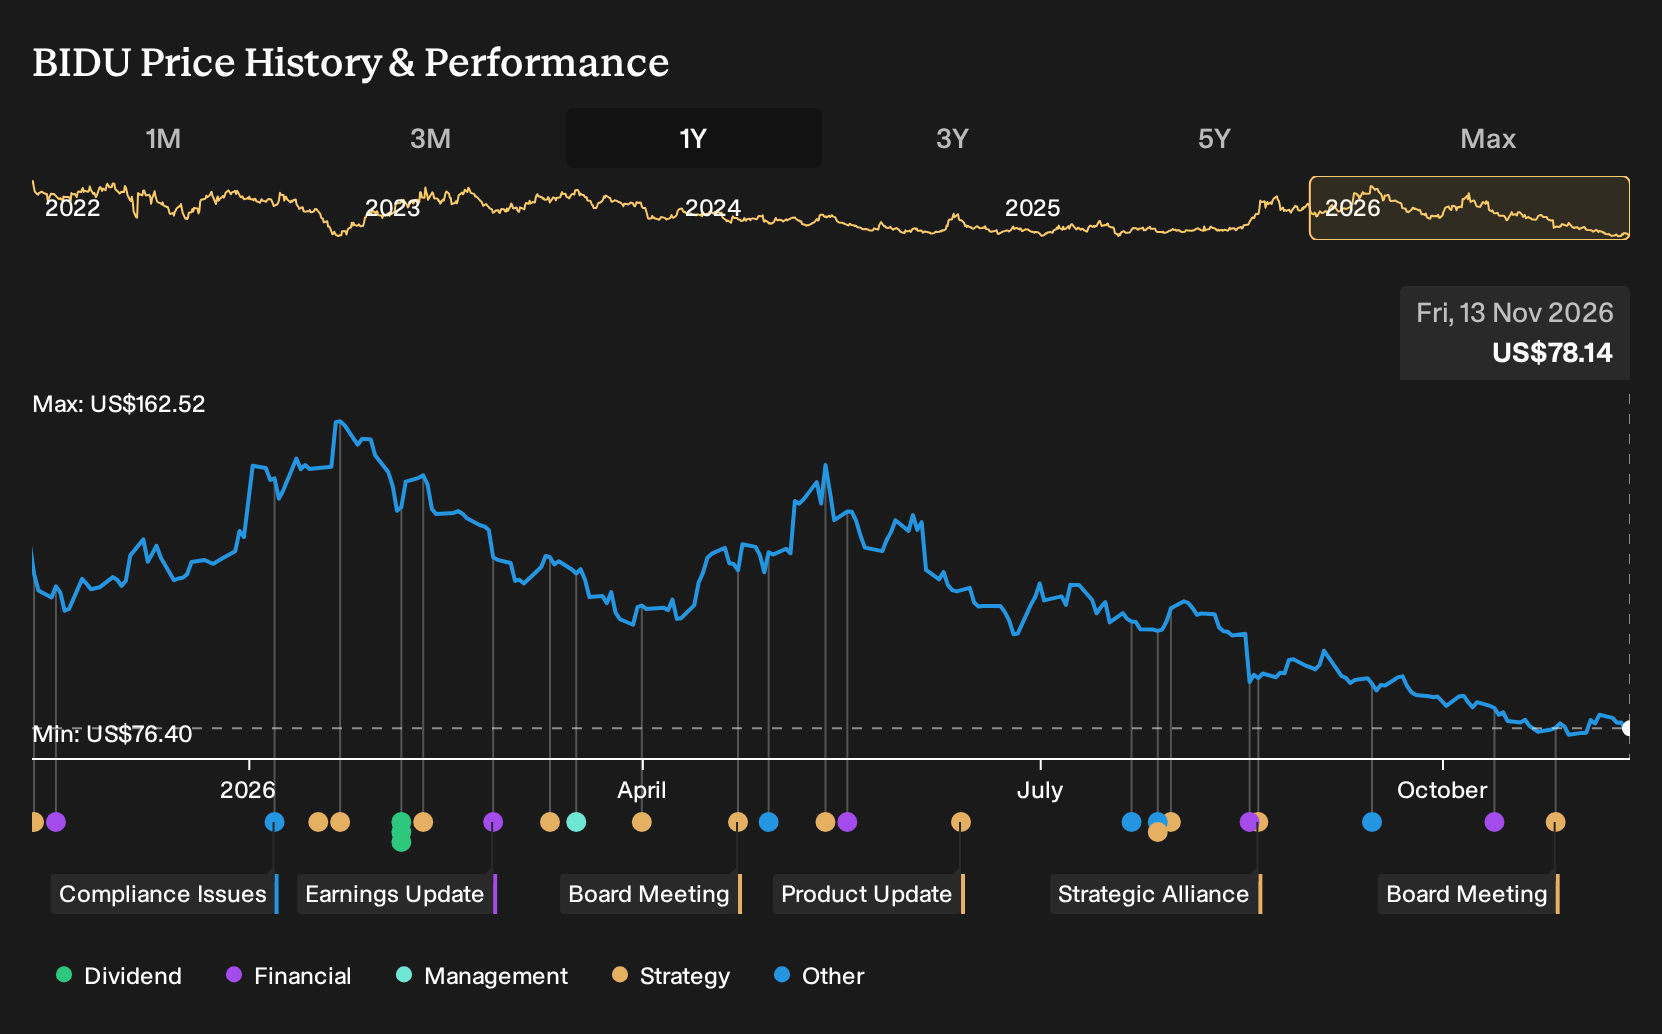
Discover how Baidu's fair value indicates a 72% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take on Baidu leans hard into Apollo Go. The most optimistic analysts were modelling revenue of CN¥185.6b and earnings of CN¥32.3b by 2029, assuming stronger ride hailing economics. That is far more upbeat than the consensus path, and it was set before the latest earnings cuts and AI product news, so you may want to compare both stories side by side.
Explore 4 other Baidu fair value estimates, including one that indicates potential upside of up to 147% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Baidu research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Baidu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baidu's overall financial health at a glance.
Looking for more ideas beyond Baidu?
Once you have a view on Baidu, it can help to compare that thesis with other businesses that share similar qualities, whether you care more about value, resilience or balance sheet strength.
- For investors who want quality at a sensible entry point, start with a focused set of value opportunities through the 32 high quality undervalued stocks.
- If capital preservation sits high on your checklist, filter for companies that have historically scored well on stability metrics by using the 31 resilient stocks with low risk scores.
- When you care most about financial resilience, stress test your watchlist against a list of solid balance sheet and fundamentals (24 results) and see which businesses still pass your hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com