


EN
How Investors May Respond To Callaway Golf Stock After Raised Outlook
- Callaway Golf reported third quarter 2026 sales of US$436.9 million and net income of US$45.7 million, raised full year revenue guidance, and committed US$15 million to a new titanium focused 3D printing facility in Fort Worth to support future product development and U.S. production.
- The combination of stronger profitability, higher full year sales guidance, and a long term 3D printing build out links Callaway Golf’s margin work directly to onshore manufacturing capacity and product differentiation efforts.
- This article examines how Callaway Golf’s investment narrative is shaped by stronger earnings and the new titanium 3D printing facility.
Scan how Callaway Golf’s titanium 3D printing push compares with other potential standouts by reviewing our curated list of 20 high quality undiscovered gems in adjacent sectors.
Callaway Golf Investment Narrative Recap
For a Callaway Golf shareholder, the core belief is that a focused golf equipment and apparel platform can keep turning current margin work into steadier earnings, even if top line growth runs in the low single digits, as the analyst consensus Narrative on Simply Wall St suggests. The latest quarter delivered US$436.9 million in sales and US$45.7 million in net income, so the near term catalyst is continued execution on that profitability trend.
The biggest near term risk still sits with discretionary demand for clubs, balls, and apparel, along with pressure from input costs. The titanium 3D printing build out and higher full year revenue guidance do not remove those issues, but they signal that management is focusing on product differentiation and cost control rather than chasing volume at any price.
The US$15 million Fort Worth titanium 3D printing facility is the announcement that most directly ties into Callaway Golf’s current story. It connects seven years of additive manufacturing research to a physical U.S. production base that is scheduled to become operational in 2027 and to support part of U.S. product needs from 2028, initially in custom titanium products.
For you as an investor, that project matters because it sits alongside guidance for 2026 consolidated net sales of US$2.065b to US$2.078b and ongoing gross margin work. Execution risk is real if capital is tied up in capacity that is slow to ramp. If the facility hits its timelines and quality goals it could support the margin and product mix improvements that analysts already build into the consensus narrative.
Callaway Golf’s current analyst story points to US$2.2b in revenue and US$213.5 million in earnings by 2029, with revenue expected to stay broadly flat and earnings rising by about US$132.9 million from US$80.6 million today, as margin assumptions do more of the heavy lifting than top line growth.
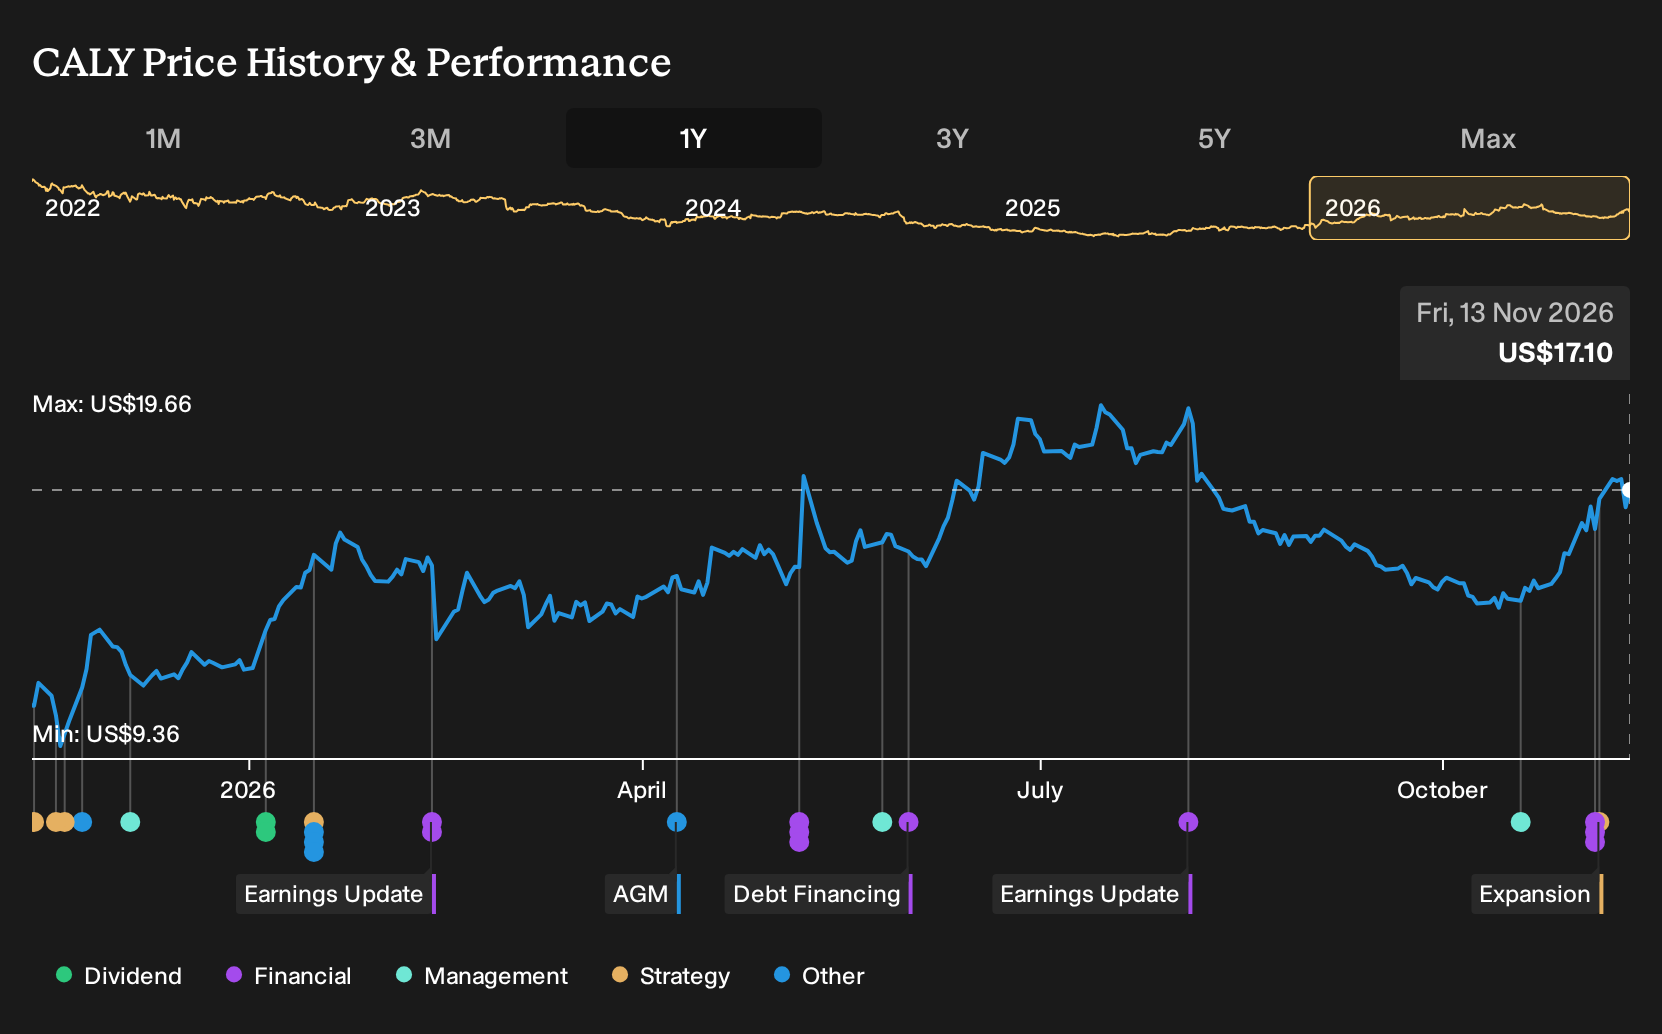
Uncover why Callaway Golf's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Callaway Golf storyline leans hard into earnings power rather than factory buildout. The most optimistic analysts were already penciling in revenue of about US$2.3b and earnings of US$180.6 million by 2029 before this 3D printing plan, and they tag on a higher P/E of 26.9x. That is a much more upbeat script than consensus, so treat it as one possible lens and compare it with more cautious views before deciding how this new facility changes your own thesis.
Explore 2 other Callaway Golf fair value estimates, including one that suggests as much as 68% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Callaway Golf research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Callaway Golf. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Callaway Golf's overall financial health at a glance.
Looking for more Callaway Golf style investment ideas?
If the Callaway Golf story has you thinking about what else might be hiding in plain sight, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- For investors who want potential value with quality fundamentals on their side, scan our curated set of 32 high quality undervalued stocks that may warrant a closer look.
- If resilience is top of your checklist, filter for companies with steadier risk profiles by reviewing a 31 resilient stocks with low risk scores suited to cautious capital.
- When balance sheet strength matters most, zero in on businesses backed by strong finances using our list of solid balance sheet and fundamentals (24 results) to anchor your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com