


EN
Earnings Upgrades Could Be A Big Deal For Axogen Stock (AXGN)
- Axogen recently presented at Canaccord Genuity's MedTech, Diagnostics and Digital Health & Services Forum in New York, sharing its latest progress in peripheral nerve repair and commercial execution with institutional investors.
- The most material angle is how upwardly revised earnings expectations intersect with Axogen's push to scale new procedures and products without diluting margins.
- We will now look at how Axogen's earnings upgrades and momentum might reshape the investment narrative built around nerve repair growth.
Scan the wider nerve repair space by comparing Axogen with a curated group of high momentum healthcare names, screened for quality and valuation using our 20 high quality undiscovered gems.
Axogen Investment Narrative Recap
To hold Axogen, you need to believe the business can keep expanding peripheral nerve procedures in breast, extremity and future prostate indications while protecting already pressured margins. The analyst consensus Narrative on Simply Wall St leans on broader payer coverage and higher account productivity to support that view. The key near term catalyst is execution on procedure growth without further erosion in gross margin or a step up in operating costs.
The recent Canaccord forum appearance matters mainly as a check in on that execution, not a change in direction. Management reiterated progress on payer access, account penetration and BioCircuit integration. The main risk still sits in cost discipline, given Q3 2026 gross margin softness and a sharp increase in general and administrative spending.
The most relevant recent datapoint for this conference is the BioCircuit acquisition and the role of NerveTape. Axogen paid US$200 million for a product with about US$24 million in annualised revenue and an approximately 80% gross margin, which management expects to support adjusted EBITDA margin from 2027 while staying free cash flow positive.
For you, the operational question is whether Axogen can actually extract that profile once integration costs, purchase accounting and cross selling friction show up. That acquisition also raises the bar for management commentary at events like the Canaccord forum. Investors will likely focus on early signals around procedure pull through, margin mix and whether NerveTape adoption helps offset underlying product cost pressure in the core portfolio.
Axogen's current narrative assumes revenue will grow by 24.3% a year, taking revenues to US$512.7 million and earnings to US$32.0 million by 2029, compared with a loss of US$31.9 million today, which implies an earnings swing of about US$63.9 million.
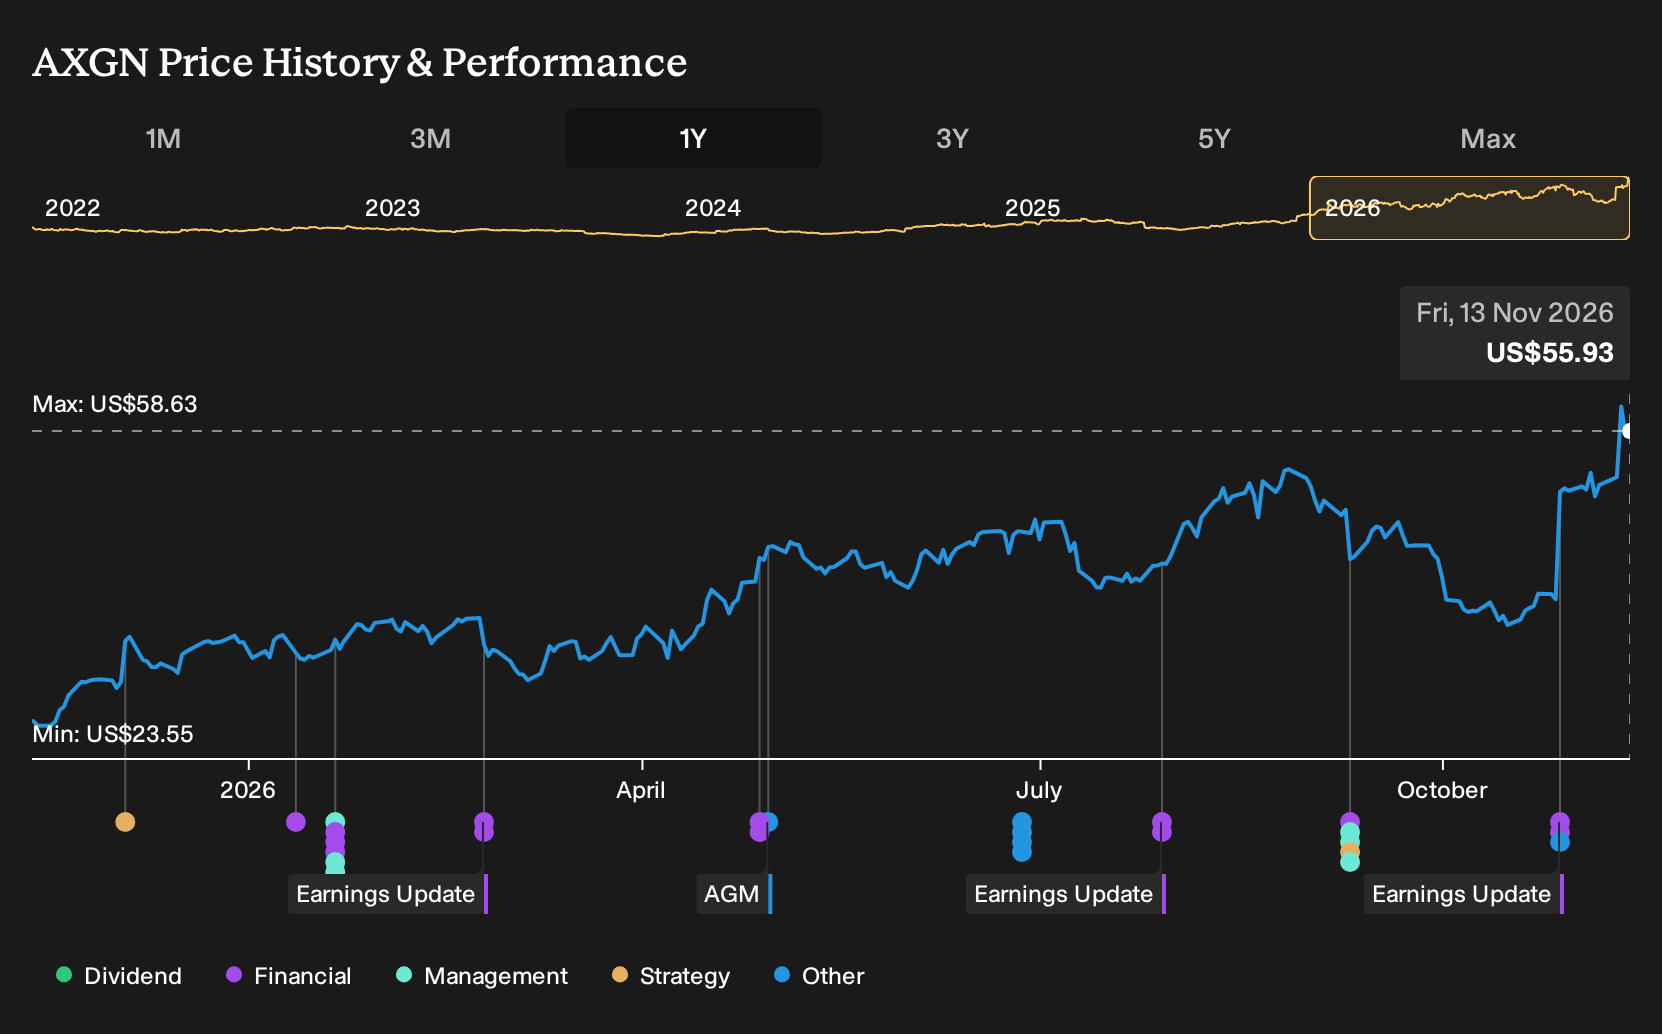
Discover how Axogen's fair value points to a 6% potential upside from its current price before investors eliminate the existing discount.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$48.16 and US$59.27 per share, which still reflects views formed before Axogen’s November forum appearance and recent momentum signals. When you factor in rising earnings expectations, margin pressure risks and the BioCircuit integration, you can see why opinions differ sharply. Explore the full range.
Explore 2 other Axogen fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Axogen research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Axogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axogen's overall financial health at a glance.
Looking for more Axogen investment ideas?
If Axogen has sharpened your interest in healthcare and beyond, it can help to cross check your thesis against other stocks that share similar qualities or offer a different risk and income profile.
- For investors who want income to be a meaningful part of total return, review companies described as 6 dividend fortresses that may offer more dependable cash payouts.
- If capital preservation matters most to you right now, focus on businesses highlighted in the 31 resilient stocks with low risk scores to see which ones score well on financial resilience.
- When you want quality fundamentals without paying up for widely followed tickers, scan our 20 high quality undiscovered gems and see which under followed stocks match your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com