


EN
How Investors May Respond To Trupanion (TRUP) Improved Earnings Guidance
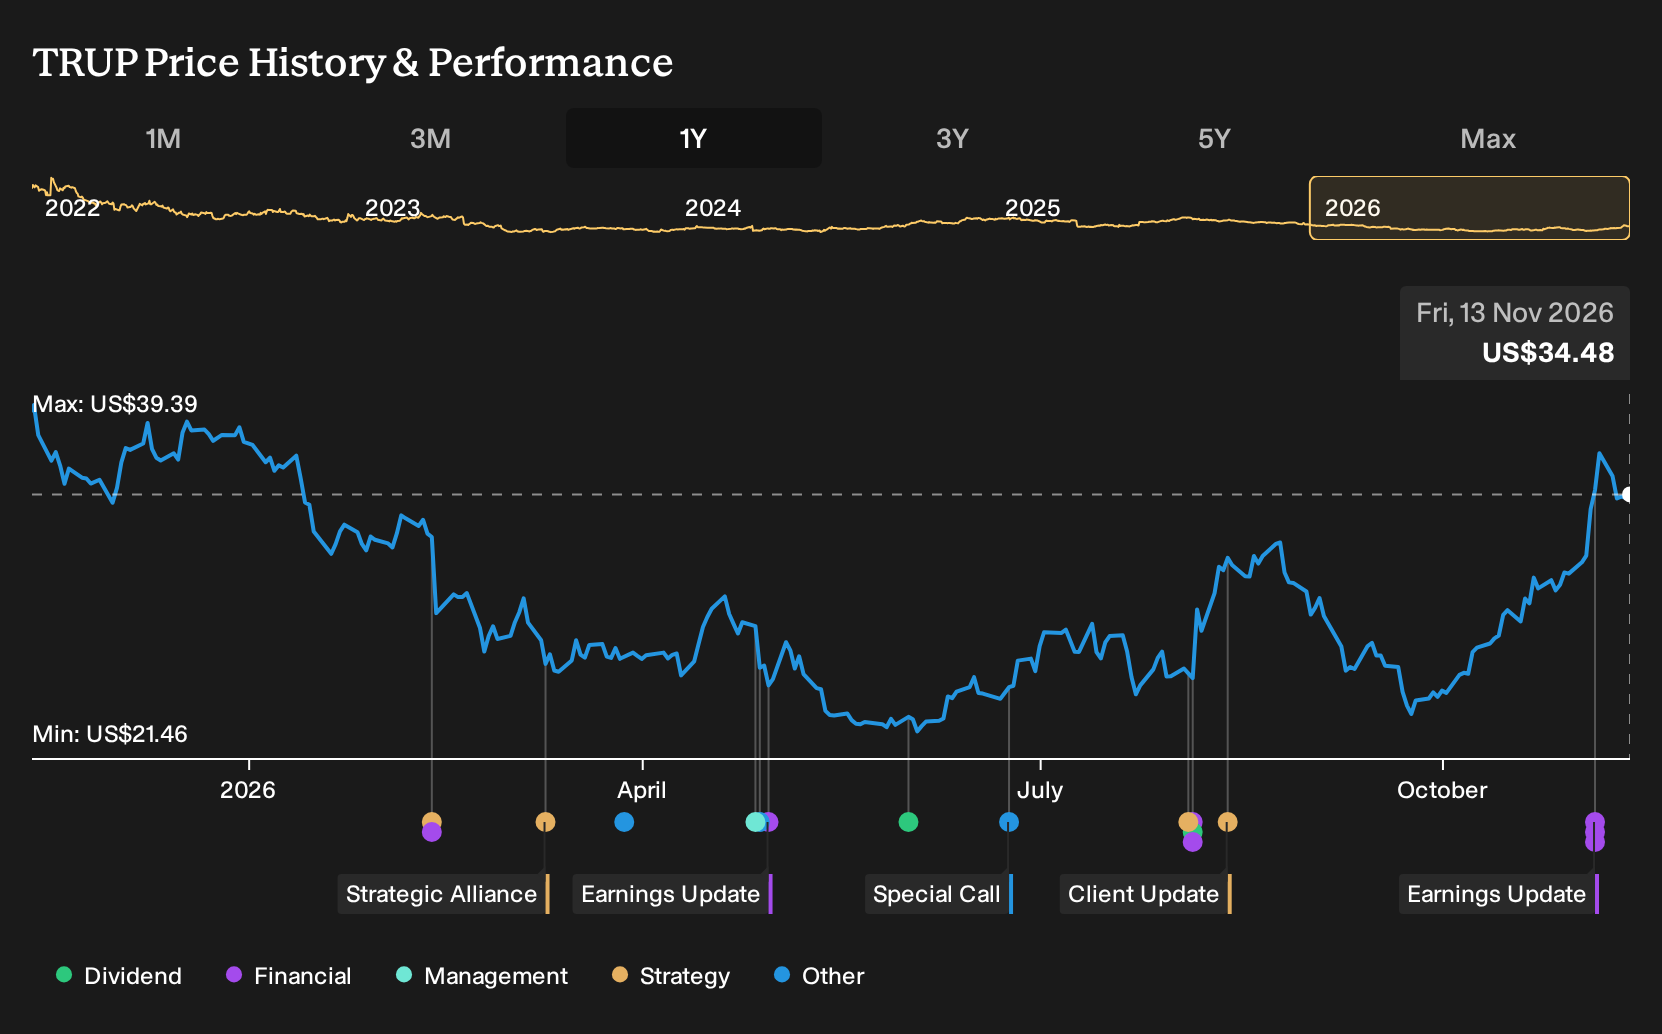
- Trupanion reported third quarter 2026 net income of US$9.28 million and earnings per share of US$0.21, alongside updated fourth quarter and full year revenue guidance.
- The firm combined higher profitability with capital moves, completing a US$25 million share repurchase while also filing a US$122.44 million common stock shelf registration.
- The following section examines how Trupanion's reported earnings and updated revenue guidance may influence the broader investment narrative around the business.
See how Trupanion's earnings story compares with other companies demonstrating resilient fundamentals and disciplined capital use across our curated 31 resilient stocks with low risk scores.
Trupanion Investment Narrative Recap
For a shareholder, the big picture in Trupanion is still about whether subscription economics can stay attractive as veterinary costs move. The analyst consensus Narrative on Simply Wall St focuses on converting recurring free cash flow and adjusted operating income into efficient pet acquisition and product development. The latest quarterly profit of US$9.28 million and earnings per share of US$0.21 point to that engine working for now.
The near term catalyst remains execution on revenue and margin guidance for Q4 and the full year of 2026. Investors will likely watch how any premium adjustments track against claim costs and customer retention. The main operational risk is that persistent vet cost inflation or weaker pet adoption trends push loss ratios higher, which could squeeze already modest net margins.
The new revenue outlook is probably the most relevant announcement for that thesis. Management guided to total revenue of US$407 million to US$414 million for Q4 2026 and US$1.59 billion to US$1.597 billion for the year. This provides a near term yardstick for subscription and other business activity.
Those figures sit alongside positive earnings over nine months of US$20.99 million. As a result, investors can now compare guidance with recent profit levels to gauge how much operating leverage Trupanion is achieving. For investors tracking catalysts, the guidance range helps frame how well claims automation, direct pay adoption and product mix are offsetting the risks from vet cost inflation and softer pet adoption.
Trupanion's current analyst narrative points to forecast revenue of US$2.0b and projected earnings of US$32.5 million by 2029, based on an expected 8.6% yearly revenue growth rate and a move in earnings from US$26.6 million today to that US$32.5 million level, which is an increase of about US$5.9 million.
Uncover how Trupanion's fair value indicates a 3% potential upside to its current price before the discount to Trupanion closes.
Exploring Other Perspectives
Some bullish analysts frame Trupanion around capital deployment rather than vet cost risk. Before this latest quarter, the most optimistic forecasts pointed to revenue of about US$2.1b and earnings of US$50.4 million by 2029, far above consensus. You can use this more upbeat scenario as a reference point and decide how fresh earnings, guidance and the new shelf registration might shift those expectations.
Explore another Trupanion fair value estimate, including one that suggests as much as 39% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Trupanion research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Trupanion. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Trupanion's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trupanion?
If the Trupanion story has sharpened your thinking about risk, cash generation and capital allocation, it can be useful to line that up against a broader watchlist of opportunities that share similar qualities or offer something completely different.
- For investors who care most about balance sheet strength and resilience, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks without constant refinancing worries.
- If you are hunting for companies that trade below what their fundamentals might justify, use our curated 32 high quality undervalued stocks to spot potential mispricings that warrant a closer look.
- Income focused readers who want yield plus staying power can scan a hand picked 6 dividend fortresses designed to highlight payouts that look more durable on current data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com