


EN
How Earnings Strength At Saputo (TSX:SAP) Has Changed Its Investment Story
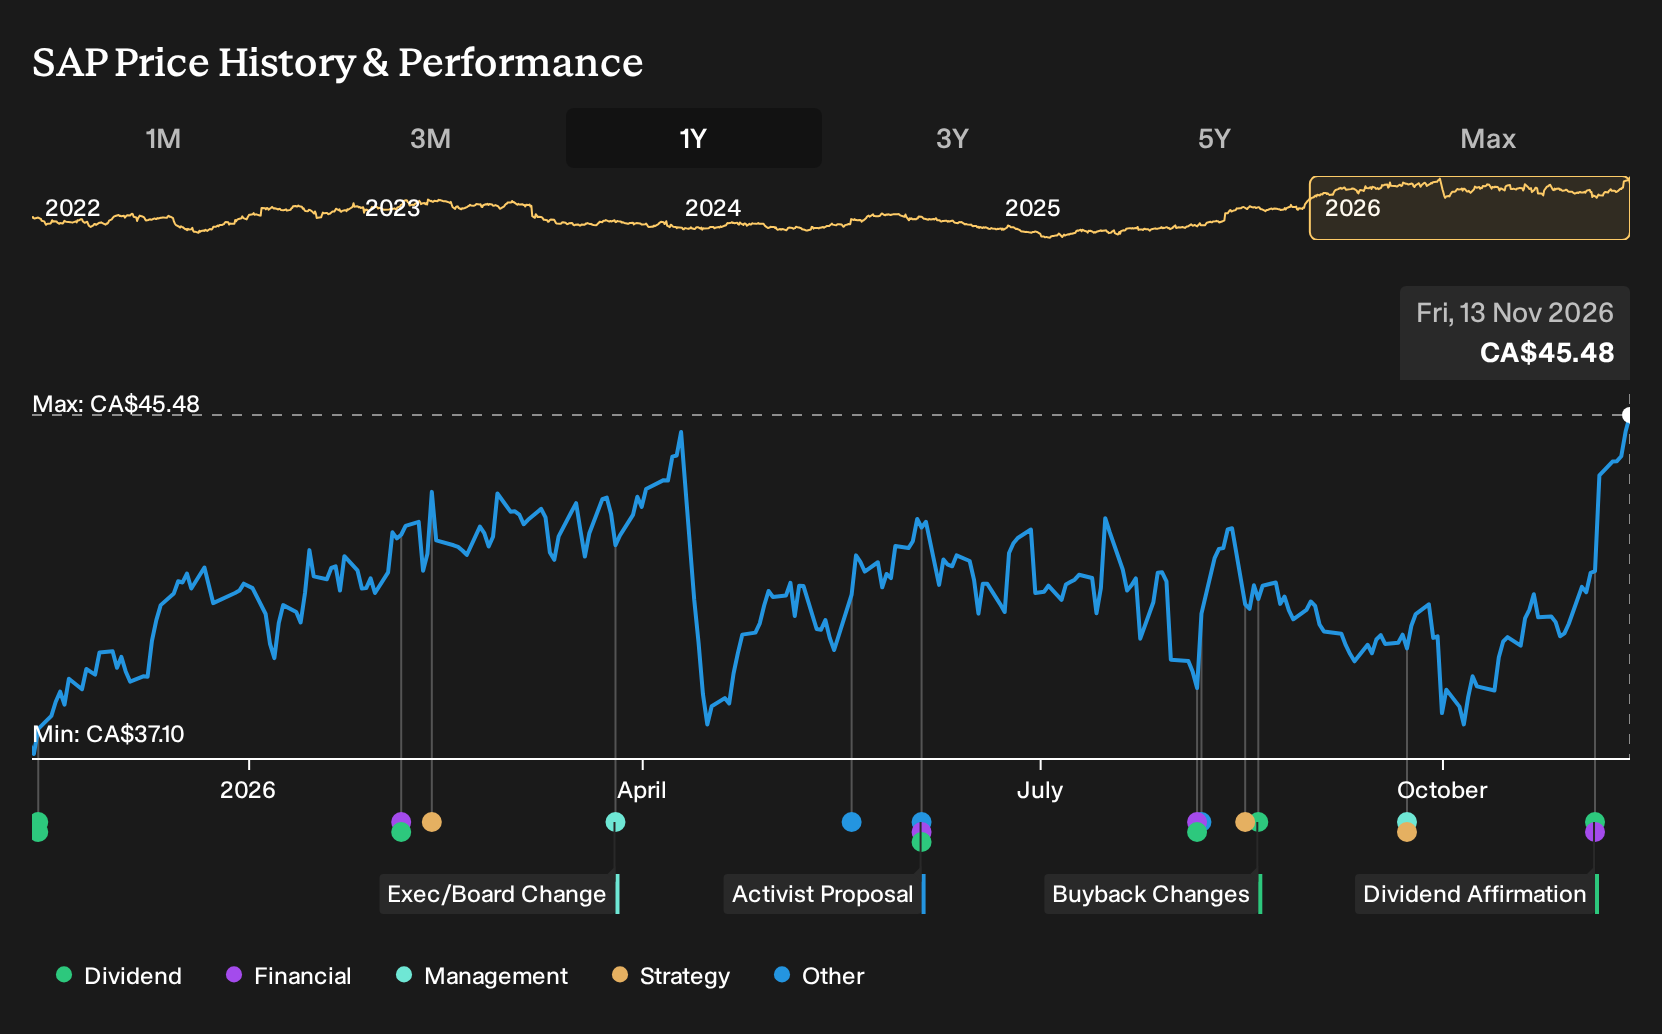
- Saputo reported second quarter sales of C$4,256 million and net income of C$259 million, approved a C$0.21 per share dividend payable in December 2026, and updated progress on its ongoing share repurchase program.
- The combination of higher quarterly earnings, an affirmed cash dividend, and completed buybacks totaling C$792 million highlights how Saputo is currently using its balance sheet to return capital while operating a large scale dairy business.
- We will now look at how Saputo's current quarterly earnings profile could influence the existing investment narrative around margins and cash returns.
Scan how Saputo's dividend and buyback moves compare with other companies returning cash to shareholders by checking the curated 3 dividend fortresses in the same income focused bracket.
Saputo Investment Narrative Recap
Saputo appeals to investors who believe its broad dairy portfolio and Ingredients Division can steadily convert efficiency projects into a more profitable mix, even while revenue expectations remain modest. The analyst consensus Narrative on Simply Wall St leans on that margin story. The latest quarterly results add fresh evidence on earnings strength, but they do not radically change the near term thesis.
In the short term, the main swing factor is whether cost inflation stays manageable so EBITDA margins can reflect past network and automation spending. The biggest risk is that higher capex planned for fiscal 2027 lifts costs without enough utilisation or mix improvement, which could pressure free cash flow and reduce room for future capital returns.
The most relevant update for that thesis is the second quarter earnings release. Saputo reported C$4,256 million in sales and C$259 million in net income, with basic EPS from continuing operations at C$0.54 and diluted EPS at C$0.53. Those figures give you a clearer read on how its large scale dairy operations are converting volume and mix into profit today.
For investors watching catalysts, that profit profile matters more than the headline dividend affirmation or completed buybacks on their own. It goes directly to whether the Ingredients Division buildout, premium dairy capacity and past supply chain projects are feeding into earnings in a way that can support ongoing dividends, periodic repurchases and the heavier spending planned for 2027 without stretching the balance sheet.
Saputo's narrative projects CA$18.0b revenue and CA$984.4 million earnings by 2029. This implies fairly flat top line expectations and an earnings increase of about CA$234 million from CA$750.0 million today, helped by the forecast move in profit margins from 4.2% to 5.5% over that period.
Uncover why Saputo's fair value indicates a 6% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Saputo’s capital spending plan as the real catalyst, not just the latest dividend and buyback headlines. Before this earnings release, that group was already modelling roughly C$18.2b in revenue and about C$960.3 million in earnings by 2029. You can use this fresh quarter to test whether you lean closer to that upbeat view or to more cautious expectations, and explore how these pre-news narratives might now evolve.
Explore 3 other Saputo fair value estimates, including one that suggests up to 7% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Saputo research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Saputo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Saputo's overall financial health at a glance.
Looking For More Saputo Style Investment Ideas?
If Saputo has you thinking about income, resilience, or hidden opportunities, it can be useful to line it up against other stocks with similar traits. The Simply Wall St Screener lets you do that in a few clicks, so you can build a wider watchlist that actually matches your goals rather than chasing headlines.
- If you want a shortlist of companies that combine quality metrics with what looks like a cheap entry point, start by scanning our 7 high quality undervalued stocks and see which ones deserve a spot on your radar.
- If capital preservation is higher on your priority list than shooting for the highest possible gain, filter for resilient businesses using the 9 resilient stocks with low risk scores so you can compare their profiles against Saputo's.
- If you are hunting for less crowded opportunities, use the 9 high quality undiscovered gems to surface stocks with solid fundamentals that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com