


EN
How New AI Equipment Tools Will Impact Samsara Stock (IOT)
- Samsara announced Samsara for Equipment and a patent pending 360-degree AI camera for operated equipment, offering unified monitoring, safety video, and equipment data on a single platform for harsh construction, warehouse, and industrial environments.
- The launch extends Samsara’s AI safety tools from road fleets into forklifts, excavators, and other operated equipment, which could influence customer spending on telematics, maintenance workflows, and liability management across large physical operations.
- We will now look at how Samsara’s new 360-degree AI equipment camera could influence the investment narrative discussed by long-term holders.
Scan beyond Samsara for other AI operations plays by reviewing the hand-picked 53 AI infrastructure stocks that could also benefit as physical workflows become more instrumented and data rich.
Samsara Investment Narrative Recap
To own Samsara, you need to believe connected operations software can keep pulling more budget from fleets, warehouses and industrial sites, and that the firm can turn that demand into durable, profitable subscription revenue. The launch of Samsara for Equipment and the 360 Camera broadens the platform, but the near term story still hinges on execution rather than this single product release.
The key short term catalyst is how efficiently Samsara converts strong forecast growth into cleaner earnings quality and improved return on equity, while managing a premium P/S multiple. The biggest risk sits on adoption friction and pushback on perceived surveillance, which Averagemike, an investor in the Simply Wall St Community, already flags around driver resistance.
The new Samsara 360 Camera for operated equipment looks most relevant here. It directly touches the concern Averagemike raised about workers feeling constantly watched, only now applied to forklifts, excavators and other gear. Take up from employers that want liability evidence is one side of the story. Acceptance from operators is the other.
On the positive side, the camera feeds into Samsara’s existing safety workflows, which can help customers close investigations on evidence and manage risk on one platform. For shareholders watching catalysts, the focus is on whether products like this deepen customer usage and justify the current valuation, or whether regulatory and workforce pushback slows deployment in high exposure environments.
Using revenue growth of 393.0% a year and a future profit margin of 3.3%, the narrative from Averagemike arrives at a fair value of $57,343 per share. This estimate is anchored on the belief that mandated adoption of Samsara style monitoring eventually supports that earnings power.
Uncover why Samsara's fair value indicates a 138543% potential upside to its current price that could narrow quickly.
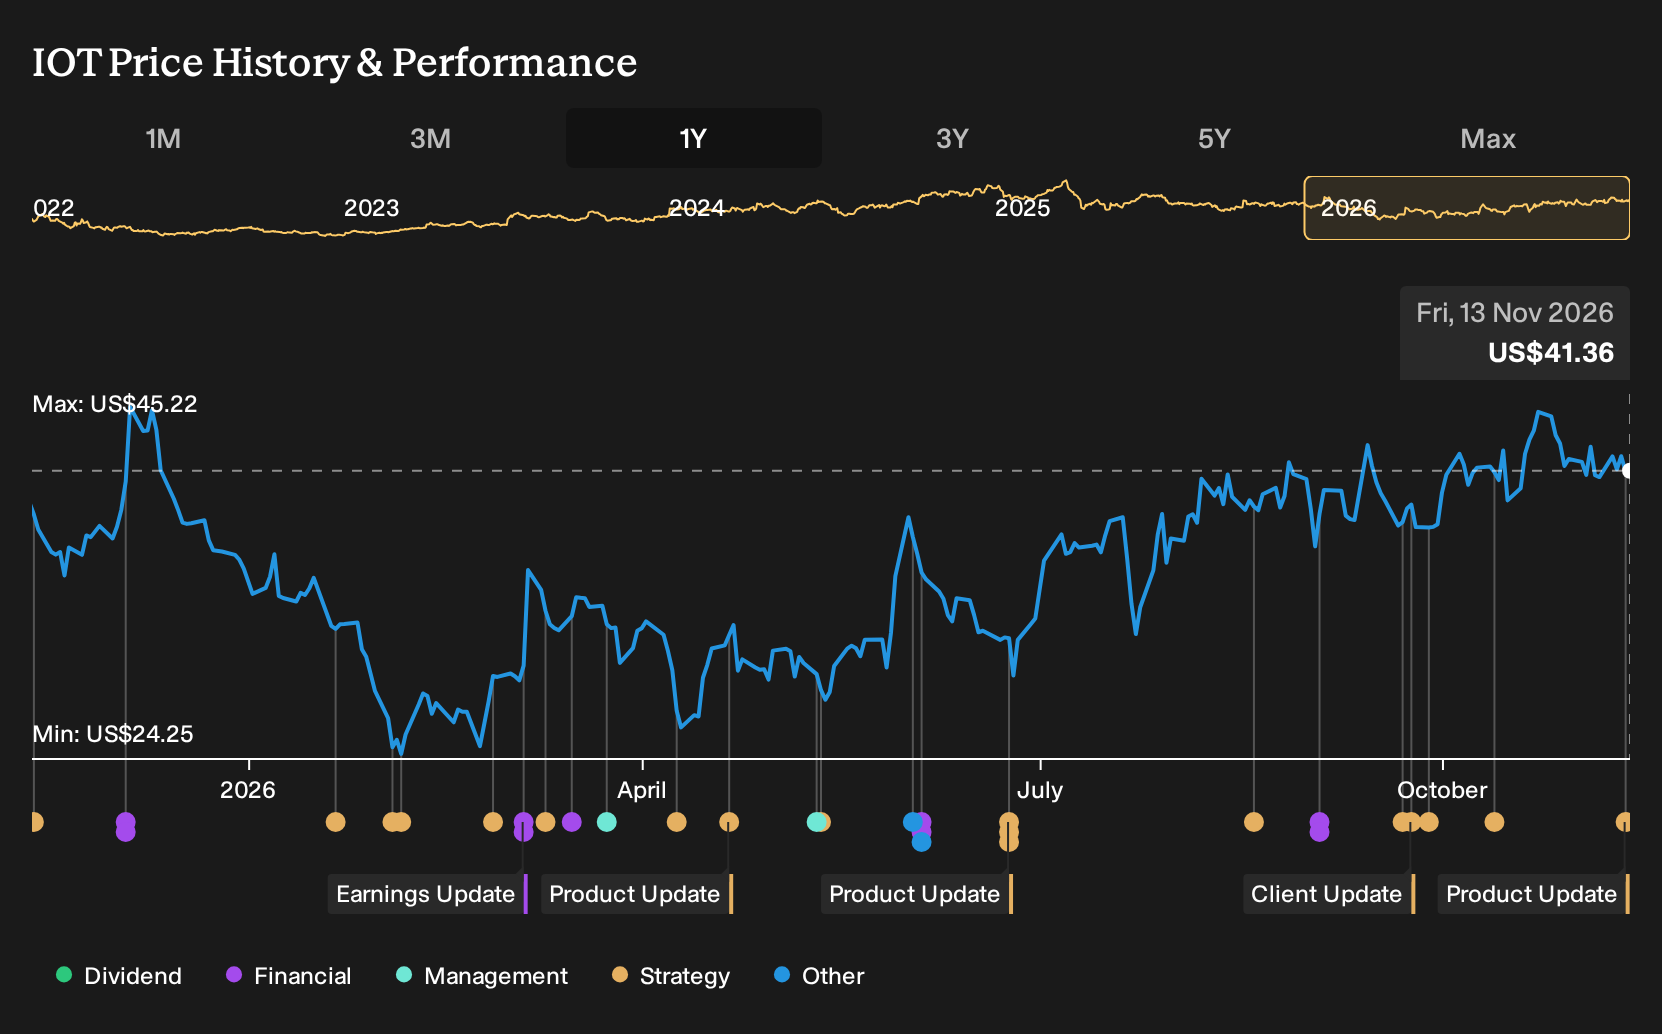
Exploring Other Perspectives
Lower ranked analysts worry most about demand, not surveillance. They expect Samsara’s revenue to reach about US$3.1b by 2029 and earnings of roughly US$272.4m, which they see as modest for today’s premium P/E. Those views were formed before this 360 equipment camera launch, so the story could shift.
Explore 8 other Samsara fair value estimates, including one that suggests as much as 31% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your Samsara research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Samsara. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Samsara's overall financial health at a glance.
Looking For More Ideas Beyond Samsara?
If Samsara has sharpened your thinking about connected operations and AI driven workflows, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- For investors who want income today rather than distant cash flows, consider a shortlist of companies with robust payouts by reviewing 6 dividend fortresses.
- If capital preservation and steadier balance sheets matter most to you, focus on financially resilient businesses through the 31 resilient stocks with low risk scores.
- When you are hunting for under followed opportunities with solid fundamentals, scan the 20 high quality undiscovered gems before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com