


EN
Is Earnings Guidance Altering The Investment Case For BGC Group (BGC)?
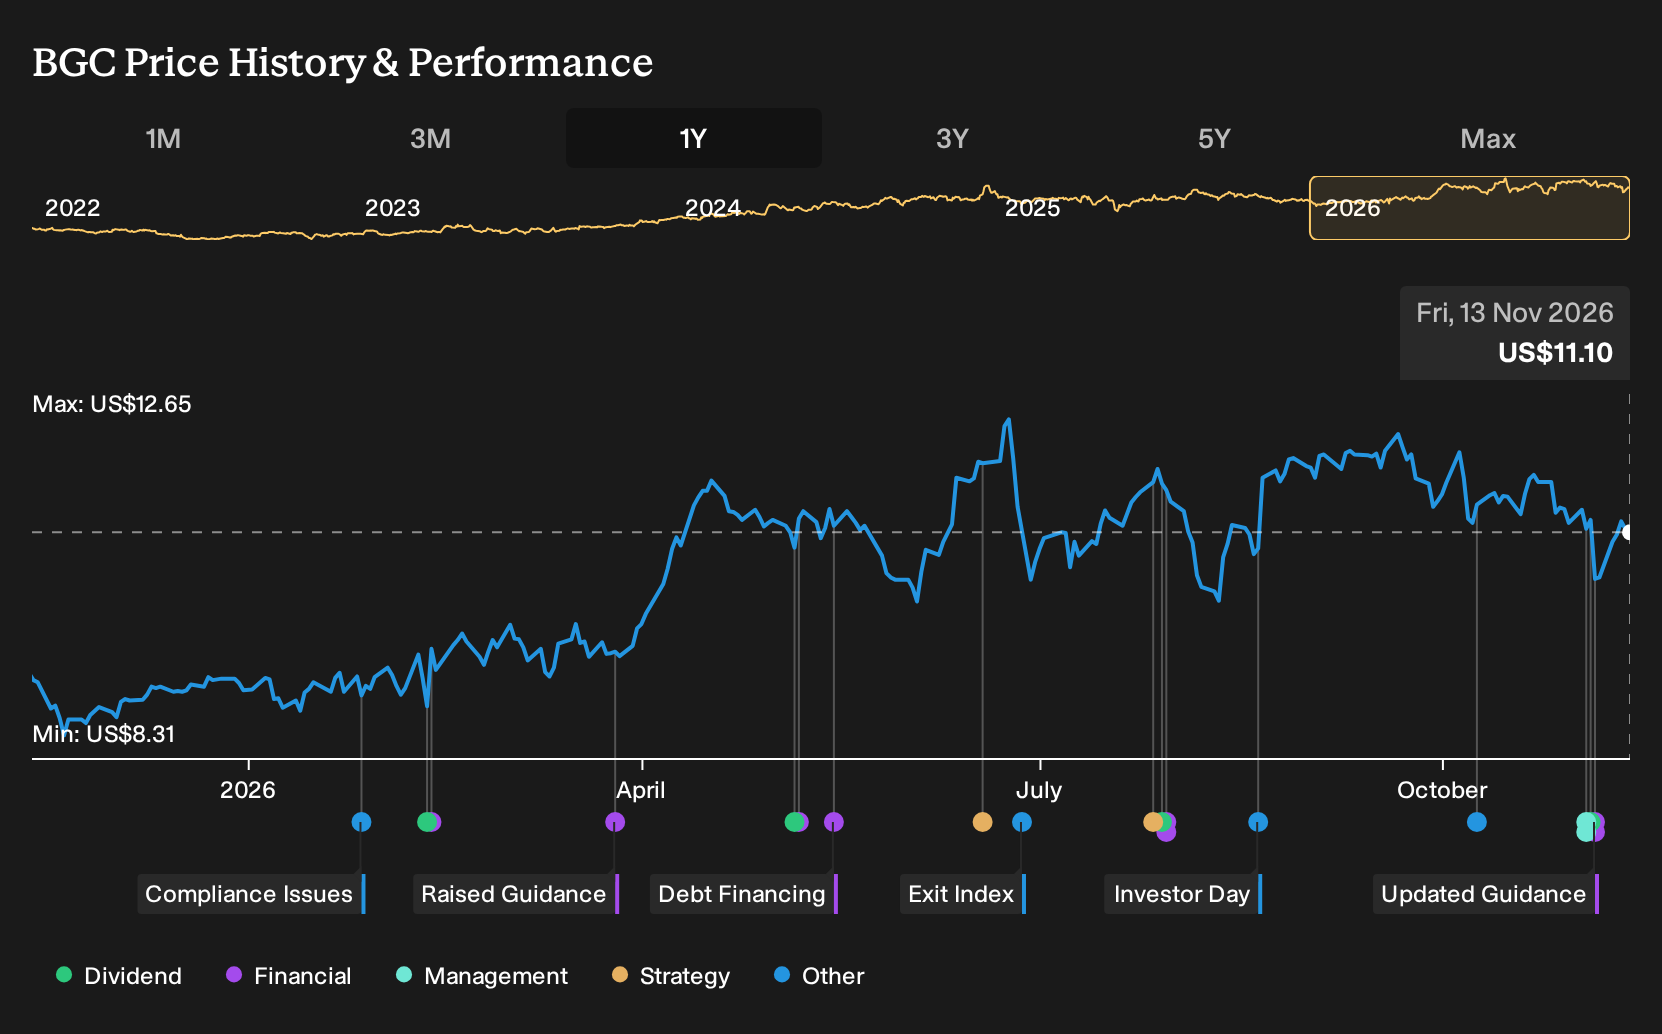
- BGC Group reported third quarter 2026 revenue of US$832.56 million and net income of US$71.29 million, alongside full year 2026 guidance that at the midpoint implies 10% fourth quarter and 18% annual revenue growth.
- The firm paired this earnings update with a US$0.02 quarterly dividend affirmation and a senior leadership reshuffle, indicating a parallel focus on capital returns, execution and longer term corporate stewardship.
- The focus now moves to how BGC Group's earnings profile might influence its broader investment narrative and risk reward balance.
What Is BGC Group's Investment Narrative?
BGC Group appeals to shareholders who buy into a fairly simple story. The broker leans on a broad, transaction driven platform across rates, credit, FX, commodities and related services. Recent third quarter figures, with US$832.56 million in revenue and US$71.29 million in net income, show that the engine can throw off earnings when activity is there. The new guidance for the fourth quarter and full year of 2026 anchors expectations and keeps the focus on execution rather than reinvention.
In the short term, the key swing factors are trading volumes, pricing power in brokerage, and how efficiently BGC Group converts that flow into profit while servicing its debt load. The affirmed US$0.02 quarterly dividend and leadership reshuffle signal that management is trying to balance near term capital returns with longer term stewardship. The guidance update fits into that picture as a test of whether recent earnings, including one off gains, translate into a steadier run rate rather than a single spike.
That said, the more interesting question for anyone looking at BGC Group now is whether the combination of leverage, one off items and valuation metrics leaves the business more exposed if ...
There's only one way to know the right time to buy, sell or hold BGC Group. Head to Simply Wall St's company report for the latest analysis of BGC Group's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your BGC Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BGC Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BGC Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond BGC Group?
If BGC Group has sharpened your focus on earnings quality, balance sheets and risk, it can be useful to line it up against a broader watchlist. The Simply Wall St Screener lets you filter companies by fundamentals so you can build a short list that fits your own risk tolerance and income or growth priorities.
- For investors who want to combine upside potential with a margin of safety, start with a curated set of companies screened for attractive valuations and solid fundamentals through the 32 high quality undervalued stocks.
- If capital preservation and resilience matter most to you, concentrate on businesses with stronger finances by scanning our list of solid balance sheet and fundamentals (24 results) to see which stocks carry sturdier balance sheets.
- Those seeking income ideas can focus on stability and yield together by reviewing a hand picked group of higher yielding payers in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com