


EN
Is Higher Service Spending Altering The Investment Case For Las Vegas Sands (LVS)?
- Sands China announced in early November 2026 that it amended its shared services agreement with Las Vegas Sands, lifting annual caps on marketing and transportation services through 2028 to reflect higher business volume, a tighter competitive environment, service quality goals and increased fuel costs.
- The revised caps, set on a cost allocation basis and backed by detailed invoicing, highlight how Las Vegas Sands is tying support services spending directly to actual operational intensity and service standards across its properties.
- We will now look at how this higher shared services capacity reshapes Las Vegas Sands' investment narrative around demand, costs and execution.
Las Vegas Sands Investment Narrative Recap
To own Las Vegas Sands, you basically need to believe its Macau and Singapore resorts can keep attracting higher value tourism and business traffic despite softer Macau data, intense competition and recent earnings misses highlighted in the analyst consensus Narrative on Simply Wall St. The bigger near term swing factor remains how premium mass and VIP play hold up relative to promotional intensity and cost inflation.
The expanded shared services caps in Macau look incremental for that near term story. They point to higher operating throughput and service ambitions, but they largely formalise cost pass through. The more acute risk still sits with Macau demand softness and any further earnings disappointments that could keep pressure on sentiment and limit room for mis execution.
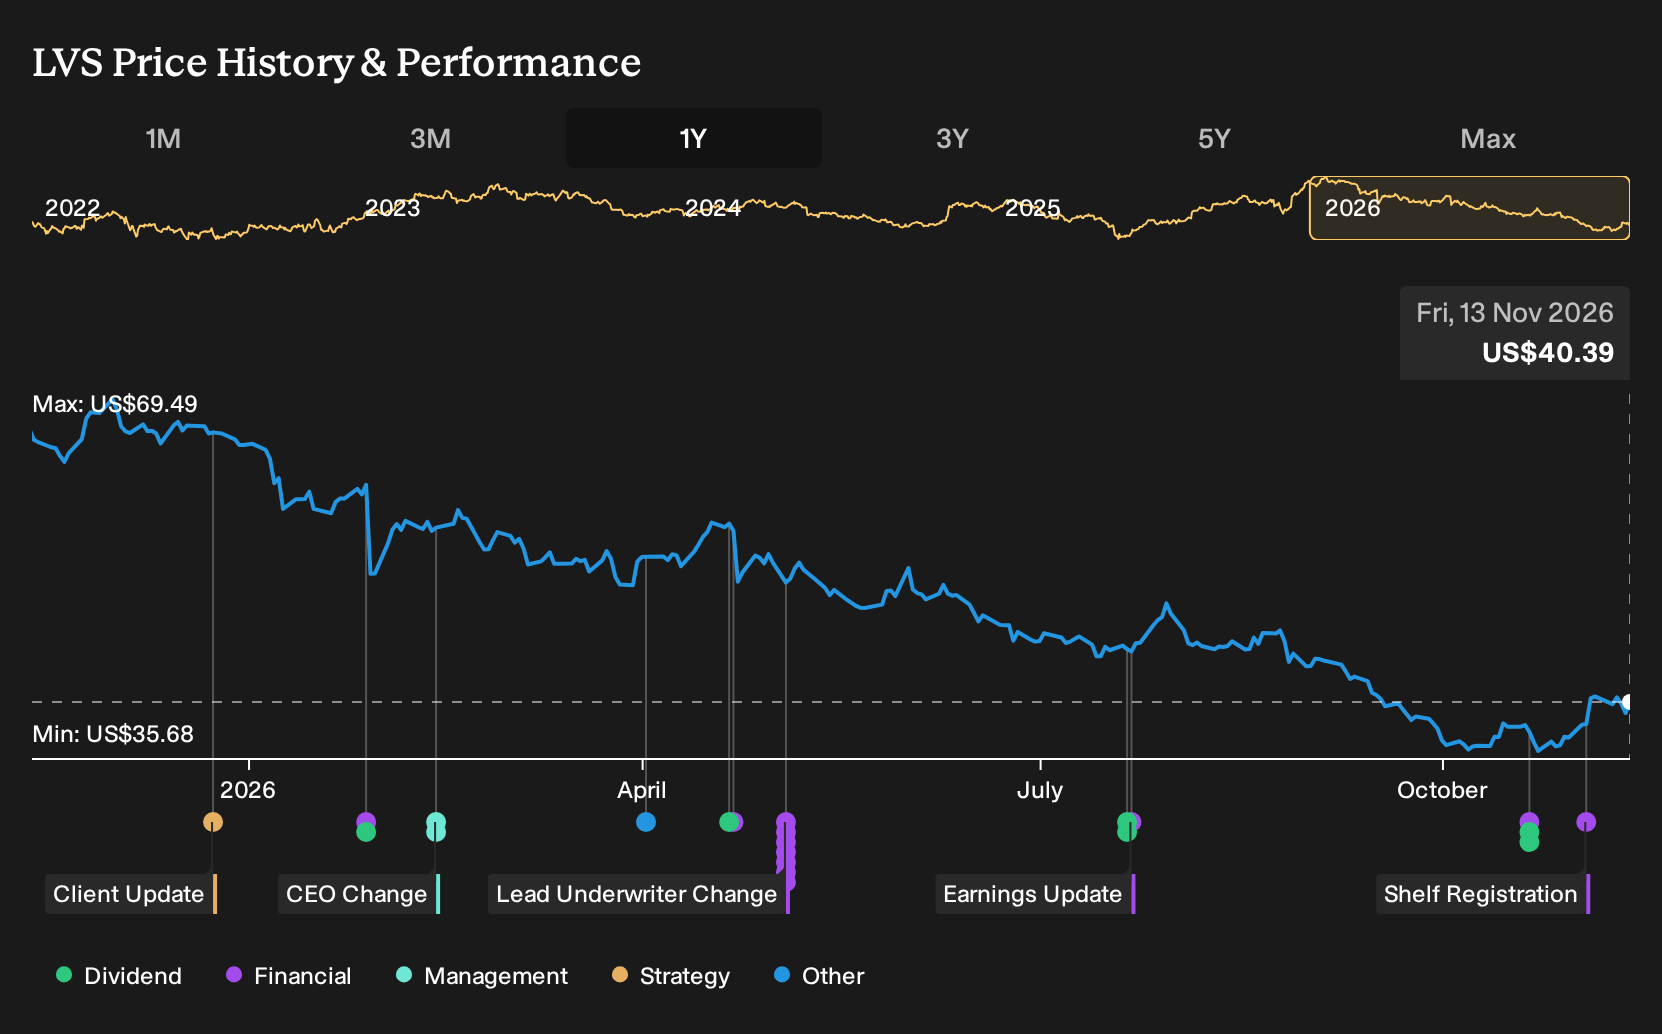
The universal shelf registration filed in early November is the announcement that matters next to this services amendment. It gives Las Vegas Sands flexibility to issue debt, equity or hybrids if large projects such as Marina Bay Sands IR2 or Macau refurbishments require extra funding or if refinancing needs change.
For you, the link to catalysts is straightforward. Execution on premium positioning and large capex programs already carries timing and budget risk. The shelf simply adds another financing lever. That can support long term investment capacity, while still leaving investors to watch leverage, funding costs and the impact on per share metrics if new securities are eventually issued.
Las Vegas Sands' current analyst narrative points to US$15.4b in revenue and US$2.2b in earnings by 2029, based on 4.2% yearly revenue growth and an earnings increase of about US$600m from the US$1.6b reported today.
Uncover why Las Vegas Sands' fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist you might explore is the optimistic take on Las Vegas Sands using its investment grade balance sheet more aggressively. Top analysts were already penciling in about US$15.8b of revenue and US$2.3b of earnings for 2029 before this shared services news, so their more upbeat story on future projects and funding flexibility could shift further as these higher cost caps feed through updated models.
Explore another Las Vegas Sands fair value estimate, including one that suggests as much as 24% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Las Vegas Sands research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Las Vegas Sands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Las Vegas Sands' overall financial health at a glance.
Looking for more Las Vegas Sands style ideas?
If you want to put Las Vegas Sands in context and round out your watchlist, it helps to see how other businesses stack up on value, quality and resilience. The Simply Wall St Screener lets you move from a single ticker to a full bench of candidates tailored to the kind of risk and return profile you prefer.
- For investors hunting for mispriced quality, start with companies that pair healthy fundamentals with appealing valuations through the 32 high quality undervalued stocks.
- If capital preservation comes first for you, focus on businesses that score well on balance sheet strength and financial resilience using the list of solid balance sheet and fundamentals (24 results).
- Those looking for under followed opportunities with solid underpinnings can scan for quieter stories with strong metrics via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com