


EN
How Quarterly Revenue Jump And Wider Loss Will Impact Sonida Senior Living (SNDA) Investors
- Sonida Senior Living reported third quarter 2026 revenue of US$210.2 million compared to US$98.04 million a year earlier, and a net loss of US$34.3 million with basic and diluted loss per share from continuing operations of US$0.72 compared to US$1.56.
- Across the first nine months of 2026, Sonida Senior Living generated US$540.48 million of revenue compared to US$283.49 million a year earlier. Over the same period, the net loss widened to US$100 million and loss per share from continuing operations reached US$3.01 compared to US$2.50, highlighting pressure on profitability despite the higher top line.
- We will look at how Sonida Senior Living's investment narrative lines up with this revenue increase alongside a deeper nine-month loss.
Compare Sonida Senior Living's widening loss profile with peers by scanning a curated list of 31 resilient stocks with low risk scores that may offer tighter risk controls and steadier fundamentals.
Sonida Senior Living Investment Narrative Recap
For Sonida Senior Living, the simple belief you would need as a shareholder is that a larger portfolio can eventually support healthier unit economics. The latest quarter shows this is far from proven. Revenue for the first nine months reached US$540.48 million, yet the net loss widened to US$100 million, so the near term story is still about loss containment.
The key short term catalyst remains operational execution on the expanded footprint from prior acquisitions and community pruning plans outlined in the analyst consensus Narrative on Simply Wall St. The biggest risk is that integration, labor costs or pricing pressure keep eating into margins. This earnings update does not resolve that concern and keeps profitability risk very present.
The most relevant disclosure is the third quarter 2026 earnings report itself. It confirms revenue for the quarter of US$210.2 million and a net loss of US$34.3 million. Loss per share from continuing operations of US$0.72, compared with US$1.56 a year earlier, points to some per share improvement, but the business is still far from breakeven.
Across the first nine months of 2026, Sonida Senior Living posted US$540.48 million in revenue and a US$100 million net loss. That sits against an analyst consensus Narrative on Simply Wall St that already flagged ongoing losses and integration, labor and funding costs as central issues. For catalysts to matter, investors will likely watch how quickly these headline losses begin to shrink from here.
Sonida Senior Living's analyst narrative points to revenues of US$1.1b and earnings of US$68.9 million by 2029, based on an assumed 31.6% yearly revenue growth rate and an earnings swing of roughly US$214 million from current earnings of a US$145.4 million loss to the forecast 2029 profit figure.
Uncover why Sonida Senior Living's fair value indicates a 44% potential upside to its current price before that gap starts to close.
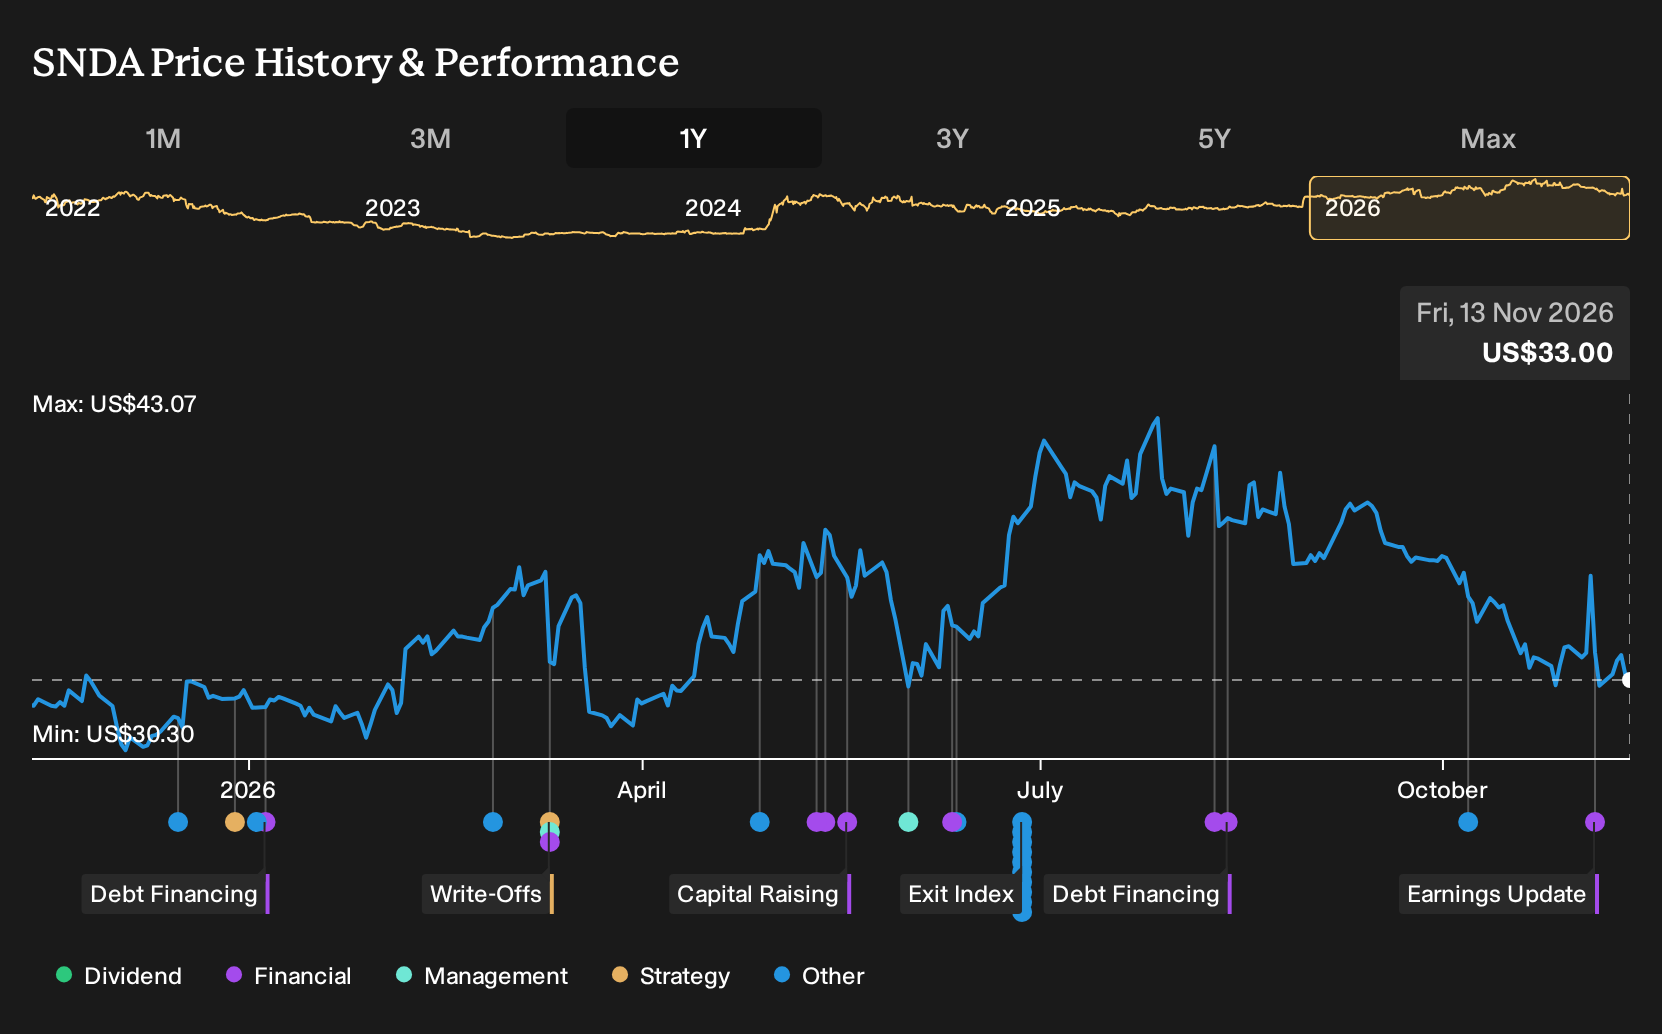
Exploring Other Perspectives
Some of the most optimistic analysts focus on Sonida Senior Living’s SPIN data platform as a potential earnings lever, with prior forecasts pointing to about US$1.1b of revenue and US$27.1 million of earnings by 2029. Those projections were set before this earnings release, so you may see views shift as new results filter through.
Explore another Sonida Senior Living fair value estimate, including one that suggests as much as 44% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sonida Senior Living research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sonida Senior Living. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonida Senior Living's overall financial health at a glance.
Looking for more investment ideas beyond Sonida Senior Living?
If the Sonida Senior Living story has you thinking about portfolio balance, use the Simply Wall St Screener to line up alternatives with different risk and return profiles in a few minutes.
- For investors who want potentially steadier price swings, review a group of 31 resilient stocks with low risk scores that score well on resilience and risk controls.
- If value is your priority, scan a curated 32 high quality undervalued stocks that combine solid fundamentals with pricing that may appeal to disciplined buyers.
- Income focused readers can focus on cash returns by checking a set of 6 dividend fortresses built around higher-yield payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com