


EN
Wolverine World Wide Stock Has The Bull Case Changed After Raised Guidance
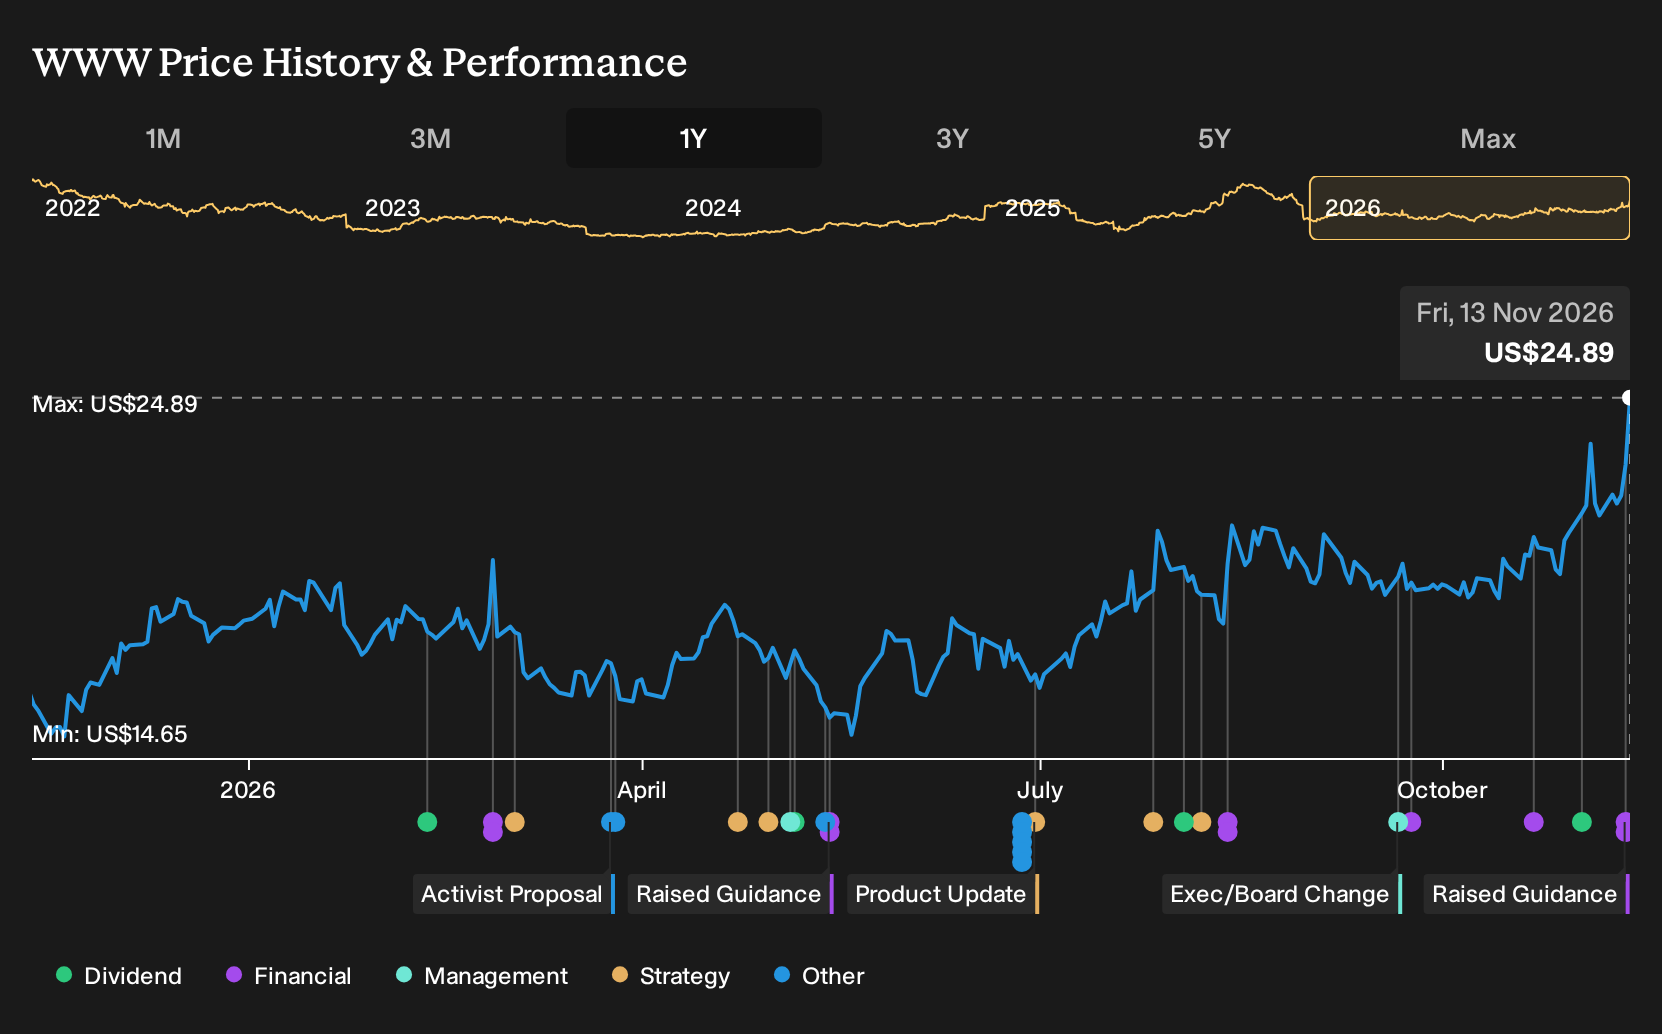
- Wolverine World Wide reported third quarter 2026 revenue of US$505.4 million and net income of US$65.8 million, then raised full year guidance for revenue, operating margin and earnings, while its board affirmed a US$0.10 quarterly dividend payable in early 2027.
- The updated outlook now includes expected 2026 revenue of US$2.0b to US$2.01b, higher operating margin of about 11.5% and projected net earnings of US$160 million to US$163 million, supported in part by IEEPA tariff refunds that lifted recent profitability.
- Investors can now assess how Wolverine World Wide's revised earnings outlook and higher margin guidance may influence the broader investment narrative.
Wolverine World Wide Investment Narrative Recap
To own Wolverine World Wide, you need to believe the core footwear franchises keep pulling more weight than the weak spots. Saucony and Merrell are doing a lot of the heavy lifting, while Sweaty Betty and the Wolverine brand still look like repair jobs. The raised 2026 guidance signals confidence in margin structure and cash conversion, not just headline revenue.
The key short term catalyst is execution on cleaner inventories, full price selling and supply chain efficiencies that support the higher 11.5% operating margin outlook. The biggest risk sits in wholesale concentration and the slow direct to consumer progress, which could bite if retail partners reduce orders or push harder on terms.
The analyst consensus Narrative on Simply Wall St already leaned on Merrell and Saucony, premium pricing and better inventory discipline as the main engines. The Q3 print fits that script. Reported sales of US$505.4 million and net income of US$65.8 million for the quarter, plus US$117.2 million of profit for the first nine months of 2026, back up that operational story.
The raised 2026 guide looks most relevant for your catalyst map. Management now forecasts US$2.0b to US$2.01b of revenue, around 11.5% operating margin and US$160 million to US$163 million of net earnings, helped by IEEPA tariff refunds. Those refunds are a tailwind today, but the real test for Wolverine World Wide is sustaining margins as that benefit rolls off.
Analysts currently frame Wolverine World Wide's setup around revenue that is projected to reach about US$2.3b by 2029, with consensus earnings of roughly US$182.7 million in that same year. This path assumes yearly top line growth of about 5.5% and an earnings increase of about US$77 million from the US$105.6 million reported today.
Discover why Wolverine World Wide's fair value appears to be essentially aligned with its current price.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between US$22.75 and about US$33, which shows how far apart retail views on Wolverine World Wide can be. When you set that against tariff refund support, wholesale dependence and the Sweaty Betty reset, you get very different conclusions about how resilient future performance might look. Explore those contrasting lenses before deciding where you land.
Explore 3 other Wolverine World Wide fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Wolverine World Wide research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wolverine World Wide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wolverine World Wide's overall financial health at a glance.
Looking for more investment ideas beyond Wolverine World Wide?
Once you have a view on Wolverine World Wide, it can help to widen the lens and compare it with other businesses that share similar strengths or risk profiles. The Simply Wall St Screener lets you move from a single ticker to a watchlist built around the traits you care about most.
- If you care most about undervalued quality, start with companies that combine robust fundamentals with attractive pricing through the 32 high quality undervalued stocks.
- If balance sheet strength comes first for you, filter for businesses with healthier leverage and liquidity profiles in the list of solid balance sheet and fundamentals (24 results).
- If you want ideas that the market might have overlooked, search for under the radar opportunities with strong fundamentals using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com