


EN
Learn Why The Bull Case For Wynn Resorts Stock Could Change Following Weaker Quarterly Earnings
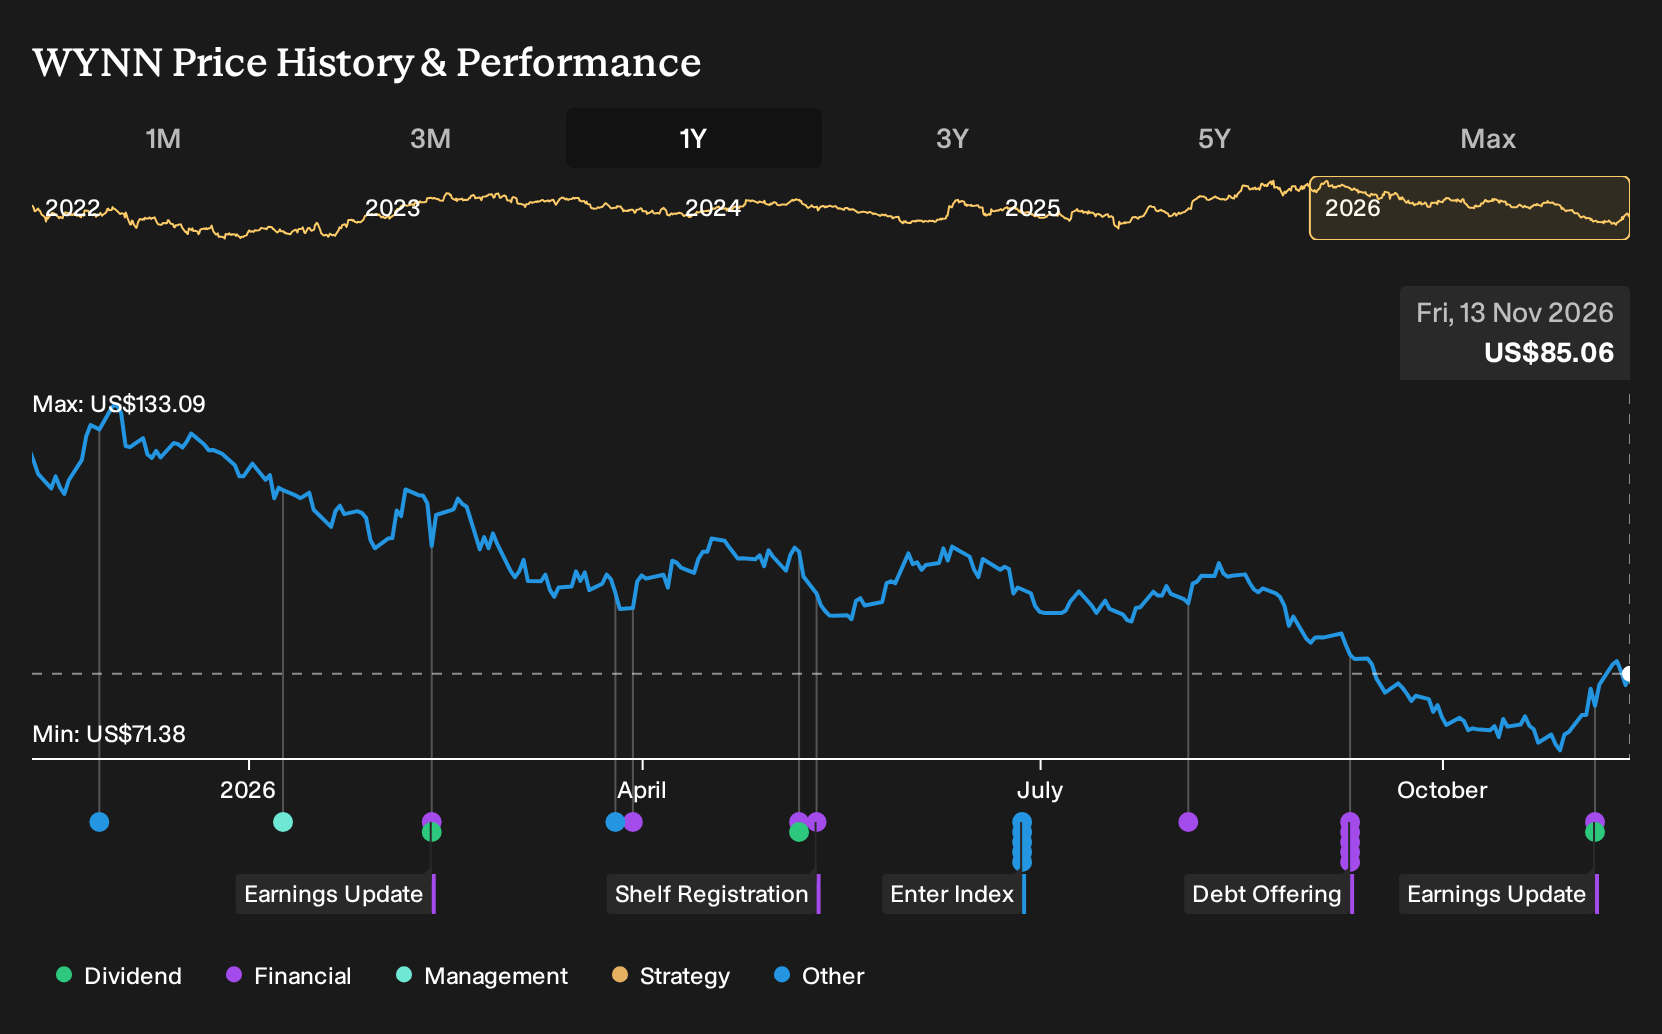
- Wynn Resorts reported third quarter 2026 revenue of US$1,689.05 million and net income of US$17.32 million, both lower than the same period a year earlier, and affirmed a US$0.25 per share dividend payable on November 30, 2026.
- The contrast between softer quarterly profitability and continued cash returns to shareholders highlights management’s confidence in the balance sheet and near term cash generation profile.
- Next, the focus shifts to how Wynn Resorts’ softer quarterly profit, alongside ongoing dividends, may reshape its broader investment narrative.
Scan beyond Wynn Resorts and see how other potential dividend payers with stronger recent profitability stack up using our curated list of 6 dividend fortresses to stress test your income ideas.
Wynn Resorts Investment Narrative Recap
To own Wynn Resorts, you need to be comfortable with a premium tourism story that leans heavily on Macau, Las Vegas and future projects like Wynn Al Marjan Island. The analyst consensus Narrative on Simply Wall St leans on that build out and premium guest mix. Softer Q3 profit, with net income at US$17.32 million, puts more pressure on execution but does not rewrite that long project pipeline.
The near term swing factor is still how well existing properties absorb higher labor and operating costs while rooms come out of service for remodels. The biggest risk is that cost inflation and development overruns, including the higher Al Marjan budget and interest expense on new notes, erode future returns if demand momentum softens.
The most relevant update here is Wynn Resorts reaffirming a US$0.25 per share dividend payable on November 30, 2026, despite quarterly net income dropping compared to last year. That decision, alongside nine month earnings of US$277.84 million and diluted EPS from continuing operations of US$2.58, keeps the focus on cash generation through the cycle.
For you as a shareholder, that payout links directly to the catalysts analysts are watching, such as the Enclave tower in Macau and Wynn Al Marjan Island. The key question is whether future EBITDAR from these projects, and ongoing high end guest spend in Las Vegas and Macau, can comfortably cover higher interest, construction costs and continued dividends.
Wynn Resorts' narrative projects US$9.2b revenue and US$544.0 million earnings by 2029. That profile assumes 7.3% yearly revenue growth and an earnings increase of roughly US$95.1 million from US$448.9 million today.
Uncover why Wynn Resorts' fair value indicates a 43% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One more optimistic angle on Wynn Resorts comes from analysts who put most weight on Wynn Al Marjan Island. They were pencilling in about US$9.8b of revenue and US$564.1 million of earnings by 2029 before this quarter. That is far above the cautious camp, and the latest results and dividend decision could shift those stories in very different directions. You can compare these contrasting views to see which assumptions you find more realistic.
Explore 2 other Wynn Resorts fair value estimates, including one that suggests as much as 79% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Unusual investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Wynn Resorts research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wynn Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wynn Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Wynn Resorts?
Once you have formed a view on Wynn Resorts, it can help to compare that thesis with a few different types of opportunities pulled from the same toolkit.
- If capital preservation matters most to you, start by reviewing a 31 resilient stocks with low risk scores that score well on resilience so you can pressure test ideas against steadier options.
- For those who prefer quality at a reasonable price, scan through a 32 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- If you enjoy spotting earlier stage potential, broaden your watchlist with a 13 elite penny stocks with strong financials that already show healthier financial traits than many peers in the same price range.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com